The end of IBKR + VT: a cheaper, safer, less US-dependent alternative

Oh yeah, most retail investors in Greece investing between 1998 and 2012 will likely never get their money back. It caused generational PTSD and suspicion/hatred of the stock markets. That’s what legal insider trading and extremely aggressive marketing combined with FOMO does, you had literal goatherders chatting about stocks in mountain villages which barely had steady electricity, yet every coffee house had stock tickers floating above their heads.

I just came back from holiday there in fact, and can report that youngsters (15-20 years old) are constantly talking about trading and stuff they most likely don’t understand, as they’ve been taken in my incessant social media marketing. Personally I can’t tell if this is a bubble of Greek stocks or not, time will tell.

Other than that I agree with you!

First of all thank you to the original poster. As IBKR and VT is a big part of my portfolio, this post is really triggering me to take action to spare my loved ones from dealing with the burden of US Estate taxes. And attending a funeral recently of a distant relative reinforced it.

So I was trying to figure out what can I do with minimal effort to mitigate this risk rather quickly. Could switching VT to European domiciled ETFs in IBKR help?

To avoid U.S. Estate taxes, the goal is to stay under the USD 60k limit for “U.S. situs” assets. Apparently cash held in a deposit account (not sure if IBKR qualifies as a deposit account) is exempted from the definition of U.S. situs assets. Most importantly, it seems UCITS ETFs are not considered to be U.S. situs assets (source: UCITS vs US ETFs: Tax, Withholding & Estate Tax Compared ).

So looking for feedback on the following two assumptions:

  1. Cash held in IBKR is not considered as a U.S. Situs Asset
  2. UCITS ETFs are not considered as U.S. Situs Asset
3 Likes

Correct, the assets matter, not the broker. An IE-ISIN on IBKR isn’t in scope. An US-ISIN on Swissquote is.

5 Likes

I am very sorry for your loss. These moments make us reflect on life, love and death, and what’s a life well-lived. They also remind us how ridiculously absurd it would be to focus on tiny amounts of money instead of the well-being and the peace of mind of our loved ones :pensive_face:

Assuming you are a Swiss resident, you probably contracted with IBKR UK, meaning that the underlying custodian is the US entity IB LLC. It would have been a different story with Irish accounts because the custodian would be IB IE, an Irish MiFID firm.

I’m no lawyer but you might want to read IRC §2105(b). Did I mention that the US tax system is horrendous?

In a nutshell, it excludes bank deposits from US-situs for non-resident aliens’ estate tax purposes.
I repeat: that exclusion applies to deposits at banks. A brokerage cash balance is generally viewed as a debt/receivable owed to you by the broker.

Except in very niche cases, I don’t see a reason to hold uninvested foreign cash, returning a negative yield in Swiss francs on average. The general Swiss public is better off holding Swiss francs at a regular bank, with a guaranteed positive yield so far.

Yes, you can just sell US-situs assets and get some UCITS instead. If you want to do it at the same broker, they will take 5 bps in transaction fees. There is a fee cap for larger amounts though.

Yesterday’s conversation was about new trackers being generally cheaper than established ones, which is confirmed by this morning’s new listing of iShares FTSE All World UCITS in Swiss francs.

3 Likes

Cool, I requested them to list it in CHF at Six when they launched it

3 Likes

Thank you! Could you please negotiate with Amundi as well :grimacing: ?
Only the distributing version of Prime All Country is listed in Swiss francs.

If I was able to do it, you can do it, too :+1: just reach out to them

They already listed WEBG in CHF on Six upon request (wasn’t me)

1 Like

Yes your assumptions are correct

I got PTSD when I revisited the formula in the sheet. It’s a bit complicated. But here goes:

The main formula

The main formula is FV. Because we want to be able to model monthly contributions, we use monthly values for its arguments. Those are:

  1. monthly return
  2. investment duration in months
  3. monthly contributions (× −1, as amounts deposited need to be input as negative)
  4. starting sum (× −1, as amounts deposited need to be input as negative)

1. Monthly return

The average yearly stock market return is 7%. From this, we subtract:

  • TER
  • irrecoverable withholding tax (see below)
  • income tax (see below)

This gives us the average yearly net return. Then we need to convert this value to a monthly return:
(1 + yearlyNetReturn)^(1 ÷ 12) - 1 = monthlyNetReturn

Irrecoverable withholding tax

  • For this we assume the index contains 62% US companies.
  • US dividend yield is 1.2%, and ex-US dividend yield is 2.5%.
  • Level 1 (L1) withholding tax is what is withheld when dividends get transferred from the companies to the fund, and L2 WHT is what is withheld when dividends are transferred from the fund to us.
US-domiciled

There are two things reducing recovery of WHT: lost ex-US L1 WHT and DA-1 losses.
lostWHT = lostexUSL1WHT + lostDA1

ex-US dividends have an average level 1 withholding tax of 10% for funds based in the US, which is lost forever:
lostexUSL1WHT = exUSWeight × exUSDividendYield × exUSL1WHT_USFund
0.38 × 0.025 × 0.1 = 0.00095

We also get US withholding tax credited via DA-1. We don’t get any credit if the amount isn’t at least CHF 100 (ignored in this calculation), or, depending on our financial situation (mortgage, average tax rate etc.), we may not get the full amount credited. And we don’t get the credit immediately, so we lose out on stock market returns on that money:
lostDA1 = (USWeight × USDividendYield + exUSWeight × exUSDividendYield × (1 − exUSL1WHT_USFund)) × USL2WHT × (DA1CreditRate × yearlyStockMarketReturn × yearsUntilDA1Received + (1 − DA1CreditRate))
If we get 100% credited after 1 year (the optimum), we get:
lostDA1 = (0.62 × 0.012 + 0.38 × 0.025 × (1 − 0.1)) × 0.15 × (1 × 0.07 × 1 + (1 – 1)) = 0.000167895
And if we get the 90% credited after 1½ years, we get:
lostDA1 = (0.62 × 0.012 + 0.38 × 0.025 × (1 − 0.1)) × 0.15 × (0.90 × 0.07 × 1.5 + (1 – 0.90)) = 0.00046650825

IE-domiciled

For funds based in IE, US dividends have a level 1 withholding tax of 15% and ex-US dividends have an average level 1 withholding tax of 12%, both of which are lost forever:
lostWHT = USWeight × USDividendYield × USL1WHT + exUSWeight × exUSDividendYield × exUSL1WHT_IEFund
0.62 × 0.012 × 0.15 + 0.38 × 0.025 × 0.12 = 0.002256

Income tax

US-domiciled

lostToTaxes = (USWeight × USDividendYield + exUSWeight × exUSDividendYield × (1 − exUSAverageL1WHT)) × marginalTaxRate

IE-domiciled

lostToTaxes = (USWeight × USDividendYield × (1 − USL1WHT) + exUSWeight × exUSDividendYield × (1 − exUSL1WHT)) × marginalTaxRate

2. Investment duration in months

This should be self-explanatory. If not, let someone else handle your finances :upside_down_face:

3. & 4. Monthly contributions and starting sum

Here, we subtract the buying fee and stamp tax.

IBKR

For simplicity’s sake we use automatic currency conversion (fee of 0.03%) and fixed pricing, although the calculation is still a bit complicated, as fixed pricing is at least USD 1 and at most 1% of trade value, but still depends on the number of shares (USD 0.005 per share). I left out the “max 1%” part as it only triggers with shares under USD 0.50.
netContribution = contribution × (1 − 0.0003) − MAX(1, (contribution × exchangeRateCHFUSD × (1 − 0.0003)) ÷ approximatePriceOfVT × 0.005) ÷ exchangeRateCHFUSD

Saxo

This can be cheaper if you are on a higher customer level. On the lowest level, the fee is 0.08%, but at least CHF 3. Stamp tax is 0.15%. I assumed we are buying ETFs in CHF on SIX, feel free to change this if you prefer to buy funds in other currencies.
netContribution = (contribution − MAX(3, contribution × 0.0008)) × (1 − 0.0015)

Putting it all together

The final formula now is:
FV((1 + (yearlyStockMarketReturn - TER - lostWHT - lostToTaxes))^(1 ÷ 12) - 1, investmentDurationInMonths, netMonthlyContribution × −1, netStartingSum × −1)

7 Likes

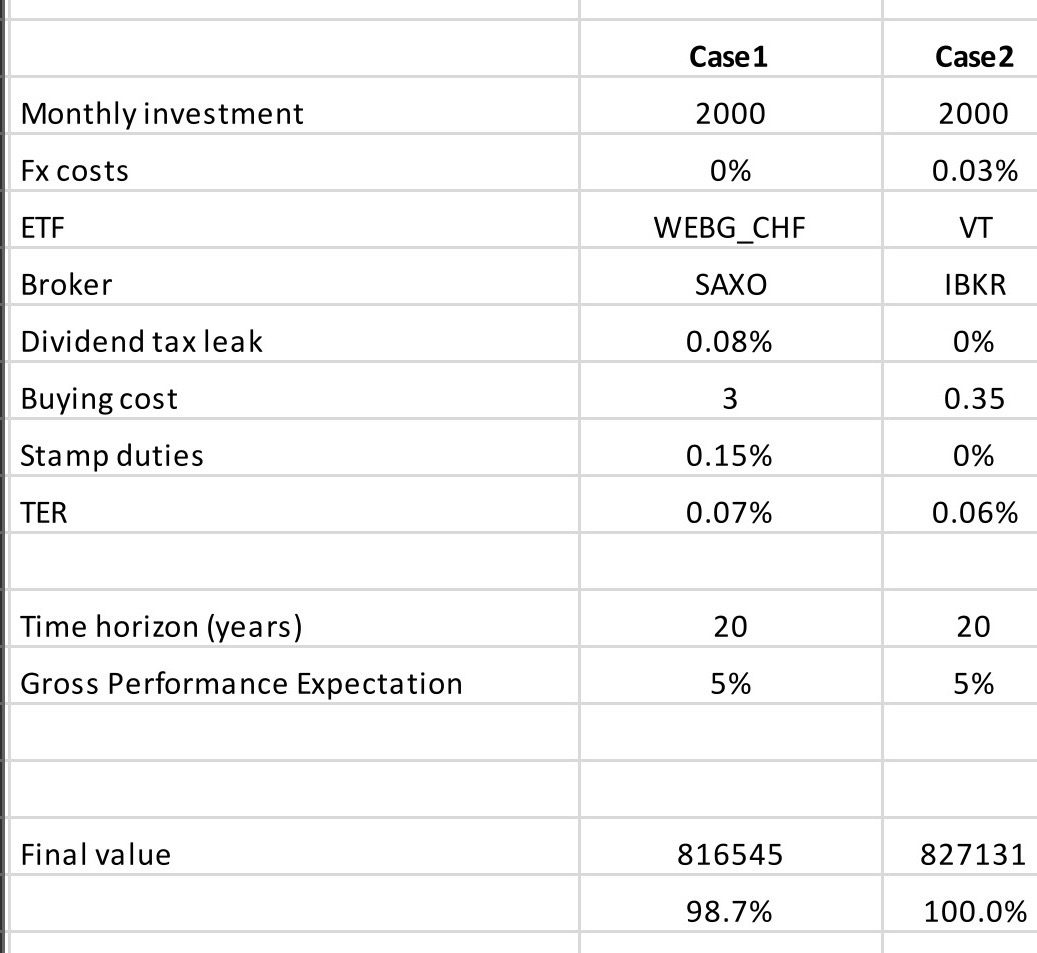
I did similar calc for WEBG_Saxo vs IBKR_VT and the difference in Final value after 20 years of investment (monthly contributions) was 1.3%.

Simply put WEBG_Saxo would achieve the final value (after 20 years of investments) of 98.7% vs 100% for VT at IBKR. This can be seen as „huge“ or „not much“. Depends on perspective of the investor. But we need to recognise that 1-2% could be move in price of ETF over a week.

I assumed 5% gross annual return as we are looking at CHF based investor.

2 Likes

btw, aren’t dividends in USD? (tho likely FX cost of that is negligible)

1 Like

Yes. I ignored that.
For a portfolio of 1 million CHF, dividend FX conversion would be 37.5 CHF on Saxo assuming people will convert back to CHF and not simply buy WEBG_USD with dividends.

Great, thank you! I kept your assumptions:

Market/return assumptions

  • Gross stock market return: 7% p.a. before costs and taxes
  • Global indices assumed to perform identically
  • Index composition: 62% US / 38% ex-US
  • Dividend yield: US 1.2%, ex-US 2.5%, blended gross dividend yield 1.694%
  • Swiss marginal income tax rate: 25%
  • Horizon: 20 years

Net annual return per fund

Fund Broker Exchange Currency TER Lost to WHT Lost to Swiss income tax Net return
VT IBKR NYSE Arca USD 0.06% 0.112% 0.400% 6.428%
XALL Saxo SIX CHF 0.07% 0.226% 0.367% 6.337%
ALLC Degiro SIX CHF 0.06% 0.000% 0.423% 6.517%

Broker/transaction cost assumptions

  • IBKR: Fixed pricing, 0.03% currency-conversion fee + max(USD 1, USD 0.005/share), converted at USD/CHF ≈ 1.24 (VT price ≈ USD 160) for every contribution and every dividend reinvestment.
  • Saxo: max(CHF 3, 0.08%) commission + 0.15% Swiss stamp duty, for every contribution.
  • Degiro: flat CHF 2.80/transaction (CHF 1 handling fee + EUR 2 transaction fee), no stamp duty, no FX fee, no custody fee, for every contribution.

Estate/legal fee assumption: CHF 15’000 (25h × CHF 600), applied only to the IBKR+VT column

Scenario IBKR + VT Saxo + XALL Degiro + ALLC
CHF 100’000 lump-sum CHF 336’511 (−4.8%) CHF 340’968 (−3.5%) CHF 353’448
CHF 1’000/month CHF 464’420 (−3.6%) CHF 471’211 (−2.2%) CHF 481’701
CHF 100’000 lump-sum + CHF 1’000/month CHF 816’059 (−2.3%) CHF 812’178 (−2.7%) CHF 835’149
CHF 250’000 lump-sum + CHF 2’500/month CHF 2’063’421 (−1.3%) CHF 2’032’572 (−2.7%) CHF 2’089’916
CHF 1’000’000 lump + CHF 10’000/quarter CHF 5’094’130 (−1.1%) CHF 4’991’911 (−3.1%) CHF 5’152’773
CHF 5’000’000 lump + CHF 50’000/quarter CHF 25’531’502 (−0.9%) CHF 24’959’554 (−3.1%) CHF 25’765’716

Didn’t we discuss above that the synthetic ETF have like a 10 bp loss from the gross index?

Also why put 0 in foreign wht. Sure US one doesn’t apply but are there evidence it’s also true for other countries? (Remember it tracks the net index)

XALL costs just 0.07%?

How are they able to undercut FWRA’s 0.15%, by more than half?

They both follow the same index, are IE based, accumulating, physical afaik.

Once the AUM gets bigger, sounds like a no brainer swap (unless it’s again just some “promotional” TER)

Can you explain how did you calculate “lost to WHT” & “lost to Swiss income tax” for each ETF?

Also what ETF is ALLC? I can’t find it on JUSTETF , is it some sort of synthetic one?

Btw one downside of those UCITS ETFs I haven’t seen mentioned is that at least on IB the margin requirements are not favorable.

Eg WEBG or XALL have a 100% margin requirement vs 25% for VT.

Have a look at the table below and feel free to input different assumptions from @assemblyrequired 's.
It’s calculated under certain assumptions but I like that we can collectively cross-check and reuse this kind of formula.

Good question! Maybe Vanguard is no better than European providers, after all :innocent:

Here is ALLC.

I used @assemblyrequired’s assumption of a 25% Swiss tax rate, identical across all three scenarios. What varies is the taxable base (how much dividend income Switzerland actually taxes) because that base depends on how much of the dividend is already lost to foreign level-1 withholding tax before it ever reaches the investor. That’s a function of fund domicile/replication method.

Here’s the taxable base for each, before applying the 25% rate:

Fund Taxable dividend base Why
VT (Physical, US) US div in full + ex-US div × (1 − 10%) = 0.62×1.2% + 0.38×2.5%×0.90 = 1.599% A US fund receives US-source dividends with no L1 leakage (they’re domestic to the fund). But ex-US dividends flowing into the US fund lose 10% to foreign L1 withholding before they arrive. Switzerland can’t tax money that never reached the fund.
XALL (Physical, Ireland) US div × (1 − 15%) + ex-US div × (1 − 12%) = 0.62×1.2%×0.85 + 0.38×2.5%×0.88 = 1.468% Ireland’s treaty network gives worse L1 rates on US dividends (15% vs the 10% the US fund effectively avoids on its own domestic income) and only slightly better on ex-US (12% vs 10%). Both legs leak before Switzerland sees the money, so the base is the smallest of the three.
ALLC (Synthetic, Luxembourg) US div + ex-US div, no reduction = 0.62×1.2% + 0.38×2.5% = 1.694% The swap counterparty delivers total-return performance: nothing is ever physically withheld anywhere, so nothing is lost before the base is computed. Switzerland taxes the whole notional yield.

So the ranking (XALL < VT < ALLC) is the mirror image of the WHT-drag ranking: the fund that loses the least to withholding tax (ALLC) pays the most to Swiss income tax, because a bigger fraction of its dividend income survives to be taxed in the first place.

Needless to say, I consider increasing the proportion of taxes staying in Switzerland instead of being paid out to the IRS as a very positive effect. Click here to see why.

Did anyone summarize how well major synthetic ETF track their respective index, and compare their performance it to their replicated counterparts? This should cover swap cost and general efficiency, as well as security lending or tax effects.

And does the result for S&P 500 or EM translate to an all world? Is that one separate swap, or rather the sum of the individual parts? Any impact on the counter-party risk?

I don’t understand swaps enough, maybe it’s obvious. But it looks a bit wild to compare trading cost down to the cent (great work though assemblyrequired), add legal fees for US estate but then assume those products perform identically and with the same risk.

For me, that would be the elephant in the room, before going into domicile, withholding taxes, or trading fees.

A few years ago, I compared iShares MSCI World swap ETF (IWDS) with its physical sibling (SWDA). Over the 12 months to Dec 2023, IWDS had a 0.33% tracking difference versus 0.46% for physical Irish-domiciled and 0.61% for physical Luxembourg-domiciled equivalents.

If you want to dive into it: An Overview of Physical and Synthetic ETF Structures* by Marco Corsi, PhD, Nusrath Hussain and David Hsu, published in December 2020.

It runs case studies on MSCI World, MSCI Emerging Markets, and S&P 500, and decomposes synthetic outperformance:

  • For the S&P 500 case (2014–2020), synthetic ETFs beat physical Irish ETFs in every one of six years, by 0.02–0.30 percentage points depending on the year.

  • For MSCI Emerging Markets, synthetic ETFs had lower tracking error (0.69% vs 1.21%) but worse tracking difference (−0.65% vs −0.39%) than physical over 2017–2020 meaning that synthetic tracked the index more consistently, but on average lagged it by more. TERs were similar (0.25% synthetic vs 0.21% physical), so swap spreads have been the main contributor.

  • Liquidity risk, return performance, and tracking error: Synthetic vs. Physical ETFs posted by @alby128 confirmed, using European ETFs 2009–2020, that synthetic ETFs offer additional returns within the low-liquidity group.

For ALLC specifically: The ETF replicates the performance of the underlying index with one swap, not a basket of regional swaps stitched together. BNP Paribas Asset Management works with a pool of eight or nine counterparties, and each counterparty’s swap exposure is capped (and collateralized) at 10% of the ETF’s NAV.

I like how this question was answered by @assemblyrequired 300 messages ago:

3 Likes