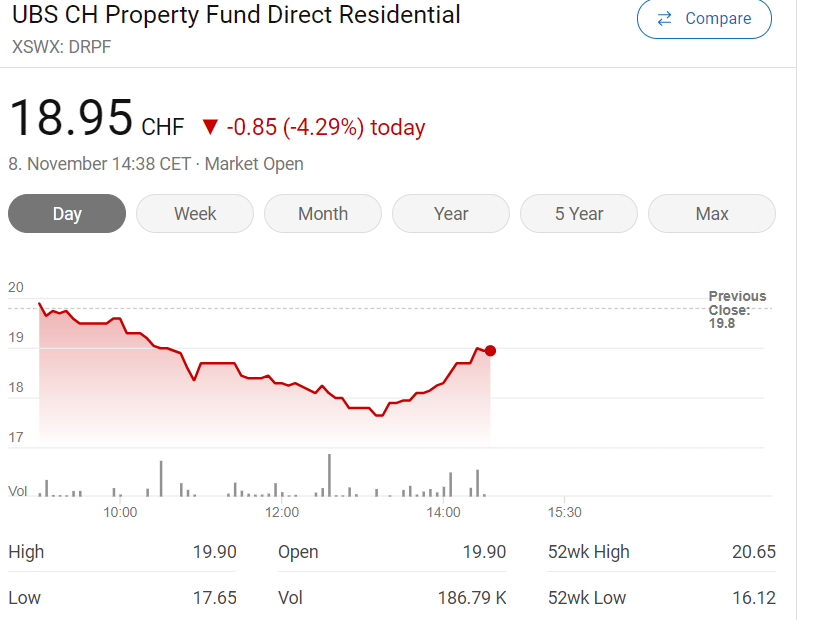
I agree. It’s a long game.
Anyways when I invest in Direct RE funds, it’s for 20 years time frame.
So it’s only a notional loss.
But its a good learning to understand how this process works
I agree. It’s a long game.
Anyways when I invest in Direct RE funds, it’s for 20 years time frame.
So it’s only a notional loss.
But its a good learning to understand how this process works
Every share or ETF you buy is not from the company or the fund manager directly.
But if a company make decisions which impact market value of the stock then it is responsibility of the company.
Let’s say you buy Google stock (in open market) and tomorrow they say they are going to invest in Tesla and buy it for 3 trillion dollars. This would tank Google stock , who is responsible? Google or person who sold you the Google stock on open market or you (the investor) ?
The investment atrategy can also change for passive index funds and they can be merged with other funds. The index can change, etc.
I think such a major strategy shift is just very bad business practice.
A good example is meme companies issuing more stock to benefit from the inflated price, I don’t think there’s anything illegal about it.
Also I guess being a closed end funds matters a lot, the investors should know that price distortions are more likely to happen and fund can trade away from fundamentals.
I think this is not a good example. DRPF was raising 70MM and they decided to issue X number of shares at 14.9. They could have also issued less than X shares at 20 CHF. In the end it had to add up to 70MM.
It does not matter what is the issue price, what matters is what is the worth of those shares. The assets they were going to buy were considered worth 70MM by market and that is why it was fully subscribed.
Are you sure they could? Not sure they can issue away from NAV. It’s not like a company trading in the stock market where the market decides.
I am not an expert but DRPF decided to issue 10% extra shares. What if they decided to issue 20% extra shares? would it also be at NAV? If they did, the subscription would be 0 because it would not be worth it…
NAV is reflecting value of the assets they have. Not the assets they want to buy. So i think the common practice is to issue shares at NAV and issue equivalent number of shares to match the fair value of assets being purchased.
And on the bright side, I can go to 25 hours hotel and ask for ownership discount next year;)
They would ussue subscription rights to the existing investors, which could be sold or executed.
So the existing investors wont be worse off than before.
I think they would always need to issue at fund NAV. Sometimes there are tiny levies for enter/exit.
But in this instance investors are mainly compensated through the value of the rights
Why wouldn’t it? They can’t raise money in the open market like a company would.
(which actually kinda sucks for them since it can leave a lot of money on the table compared to a company issuing shares, here it’s the existing shareholders that pocket the premium)
But they did issue shares and diluted the value. This is why the final value dropped about 5% from before the issuance. i really don’t think that anyone made money there. It was more or less a dilution.
If you fully executed your subscription rights, you were not diluted.
The price dropped because the new shares were issued at the NAV. But you also got the shares cheaper as existing holder.
I think everything went according to best practice.
The merge is another story… 
I have a theory question
Let’s say these 4 funds add up to a total NAV of 5 billion with ratio
65% CSLP + 15% DRPF + 5% RES + 15% HOSP
And total shares created of new fund is 1 billion shares (this means NEWFUND has NAV of 5 CHF/share)
if an investor owns 100 CHF of DRPF , would they be replaced with 20 shares of NEWFUND?
Second question, if the moves in market price of fund values are as follows
Minus a% for CSLP and p% for DRPF
Plus b% for RES and c% for HOSP
Would the market price of NEWFUND move by X% where
X = 0.05b% + 0.15c% - 0.65 * a% - 0.15*p%
If X= 0% then this means the merger resulted in no net value creation.
I would agree with both calculations.
Also, the market will probably price it correctly. I assume there wont be much arbitrage opportunity for the average joe.
I actually think I made one mistake
The number of replacement shares wouldn’t depend on actual value of DRPF shares but the NAV value of DRPF shares
So 100 CHF of DRPF would mean 75 CHF aid DRPF based on NAV and this results in 15 shares of NEWFUND
Thanks for sharing
I would be happy to see how shareholders of DRPF & CSLP react to this & if UBS would share any presentation publicly. I hope so
Since premium is not only market sentiment but also includes things life deferred capital gains, I think market already did the math for us and priced all these Funds where they should be.
Such mergers would need some sort of voting by shareholders , right?
Skimmed the prospectus, that doesn’t seem to be the case. The fund direction can do it (if the funds are similar enough and have the same direction, which I assume is the case for UBS/CS funds), I think it only needs finma approval after that.
Eg check §24 for GREEN.
Only the funds that are a SICAV have shareholders votes generally speaking. This is the case for Procimmo, Bonhote, Edmond de Rotschild and soon for Streetbox next year.
I still cannot comprehend though, how is following possible . A fund trading at premium to NAV is merged with a fund trading at Discount to NAV using NAV as exchange ratio.
To make is clear, let me try to explain a bit with an example.
How is this possible & am I understanding this whole situation correctly? It would be great if someone was expert in M&A and clarify how these things are possible.
In my mind, above will only make sense if NAV is the only real value & everything else is fictional number. But we know that every fund in Switzerland for real estate is traded at AGIO which is on average is higher than 20% (perhaps much higher for RESIDENTIAL funds). Does it mean that AGIO is a pure market premium and can disappear with actions like mergers ? This would make investing in these funds very risky.