It’s on swissfunddata (which is probably something you should subscribe to if you hold that kind of fund, that’s where all the communications get posted)
Isn’t hospitality just residential for the elderly?
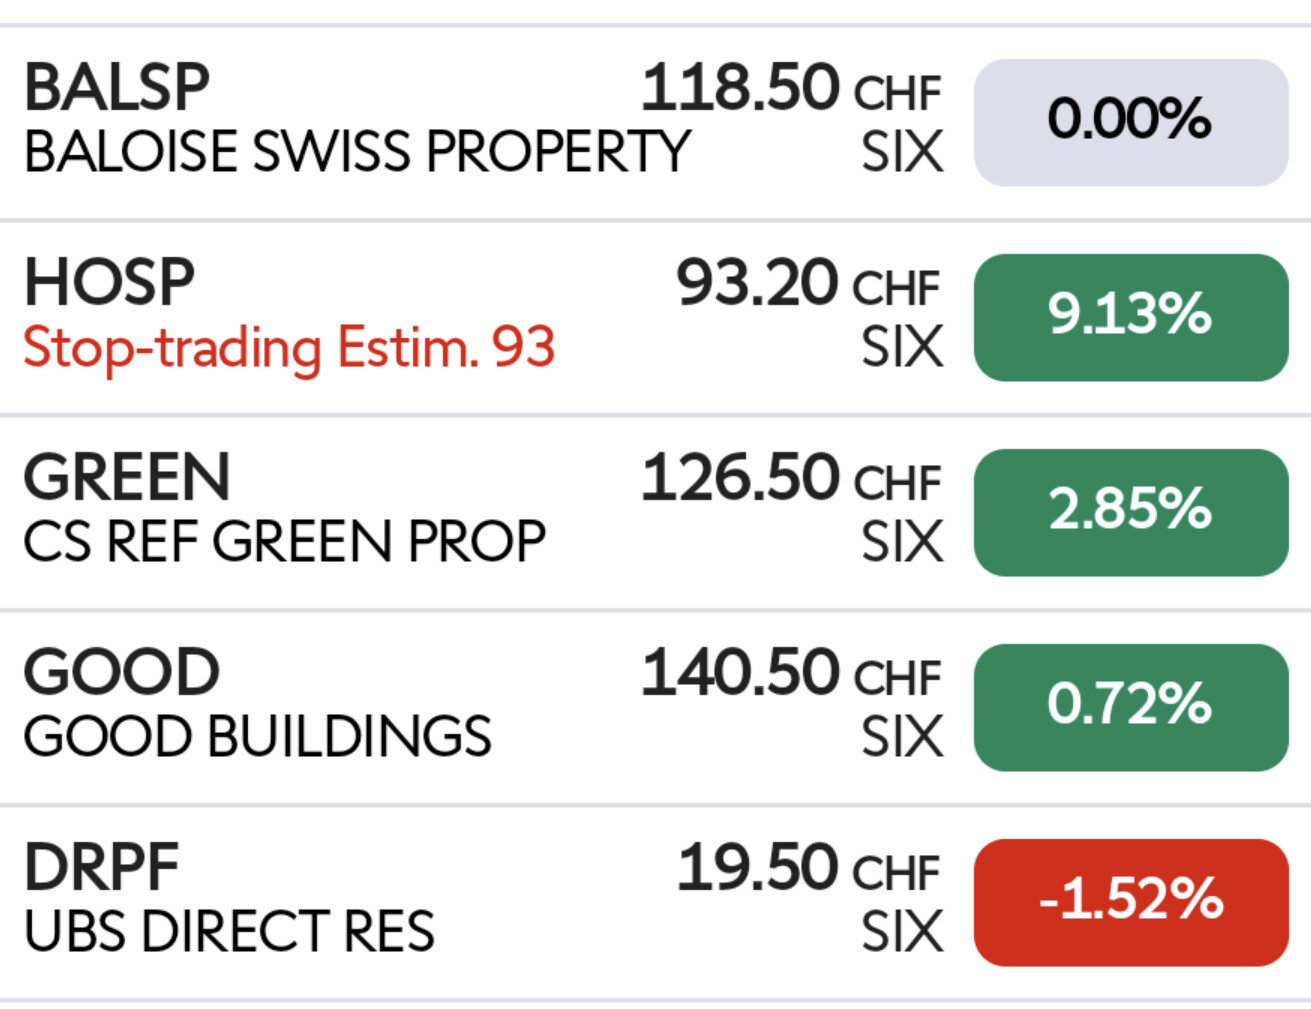
yep, look at those moves for “boring” RE this morning.
Market seems to “know” exchange will be by NAV, not market price. Agio’s narrowing between funds.
2 Likes
The “CS REF Hospitality Fund” is mainly Hotels (for example"25h Hotel" on Europaallee) and some “weird” private hospitals/clinics that one has never heard of (I haven’t, at least). No residential for elderly AFAIK.
1 Like
Not in the interest of the investor for sure.
Probably purely a business decision to extract the maximum of fees for as much AuM as possible
That’s CS REF Livingplus (CSLP)
Residentia is 50% residential , rest mixed use & commercial
Hospitality is <40% residential
1 Like
DRPF raised recently new capital. This got them new shareholders and average price was about 20 CHF after dilution
Now they announced this merger and don’t provide clear information. If it’s really based on NAV, it is a bit weird that people who own higher quality fund suffer loss versus people who own lower quality fund
I am waiting for details to come. But I think market reaction is simply based on certain assumptions. But how many shares of new company will be given to each investor is still not clear.
I wouldn’t be surprised that DRPF & CSLP share holders would get more shares of NEWFUND and then total value at investor level remains constant. Otherwise investors of CSLP & DRPF would simply lose money which cannot be the purpose of this merger.
Has anyone seen any conditions announced?
Ah, I mixed them up
I don’t think one can compare the average AGIO in Swiss real estate index . DRPF is a 82% residential fund and it also have older buildings. If a fund is completely commercial, the AGIO will be close to zero. Residential real estate is worth higher in CH and that is reflected into Agio.
The assets of CSLP & DRPF account > 80% of the new fund (based on NAV). I cannot imagine that this merger is designed to disappoint 80% of the owners and please <20% of the owners (of Residentia , HOSP)
I understand that NAV might be the logic for share distribution in the end. But I just find it a bit illogical.
If NAV is the eventual logic for distribution ratio , this whole merger would only make sense if the final entity is better than every individual entity. Or else this is a value destruction exercise for majority of shareholders & UBS should explain the rationale clearly.
P.S -: no wonder DRPF is the most hated stock today out of all four of them
By the way; your alias is called DRPF and you just joined the forum. Is it just coincidence?
My personal opinion is that DRPF is punished the most for two reasons
- they recently raised capital and never said anything about the merger. This is like pure misrepresentation of facts.
- UBS DRPF was the highest quality (before announcement) according to shareholders and now this merger makes it less interesting.
If your assumption of NAV is right; then final entity should trade at 31% agio and the outcome will be
- Residentia shareholders will be biggest winner
- DRPF shareholders will be biggest loser
And this merger makes no sense for most shareholders across the funds. I would really like to see official presentation
3 Likes
Ouch DRPF at -10% now.
That‘s crazy…. I would be very pissed at UBS if I held that fund.
HOSP owners partying right now probably.
1 Like
I hold DRPF … but I didn’t want to sell as I don’t quite understand what’s happening here
Very sad… and pissed at UBS.
I think eventually you will have 4-5% holding in Residentia and 15% in HOSP. So if they go up, it will compensate a bit
I will hold for now. But obviously if all details are out, i will reevaluate.
The residentia doesnt even bother me so much as its very small. And i was looking to add it anyways.
I just really dont like hospitality and value added in there.
And the CS livingplus is much bigger if i checked correctly.
1 Like
To be fair, it kinda does. The fund is much bigger and likely becomes more attractive if it’s marketed as “the global RE fund for CH”, it becomes a no brainer for anyone investing in RE funds. Currently for a retail investor you have to make a bunch of micro decision to decide among 5 similar fund (and then you might end up piling up in the biggest one, increasing the premium).
For time being it doesn’t seem like market participants agree to this idea
Although I also think the idea to do this must be to be a better option versus all four of them. UBS would need to sell this story very well to bring the price back up
I don’t think the price will really go back up (at least not in efficient markets), the premium should be arbitraged to become ~identical for all the funds (maybe not exactly but close to it, since there’s the risk of the merge not happening).
It would impact the long term price tho (but that’s a 5-10y horizon), if this becomes one of the most popular RE fund post merge.
I think we shouldn’t refer to NAV as NAV is an accounting number. The whole point of having a fund is to create higher value than the NAV through diversification , selection of investment and grouping them together.
Market value is what matters because that is the price people pay to buy the fund units. If DRPF was worth 20 CHF until 7 NOV, then UBS as a company managing the fund is responsible for making sure that their decisions do not destroy value.
If UBS decides to merge funds and it ends up being a value destruction exercise , then the management of UBS is responsible and no one else.
Now , having said that, I am pretty sure UBS is not crazy. They did it to deliver long term value to their shareholders (all of them). They should however explain this to people. For me it’s not clear what’s the point of merging a hospitality real estate with residential.
1 Like