Shop around. That sounds pretty bad indeed. Personally I would never accept a SARON with a lock-in larger than 6 months, and if requires a 6-month lock in, it should also allow you to amortize every 6 months minimum (if you so choose).
Aim for 0.6% margin if you go SARON
Check Hypotheke.ch and Moneypark.ch (I can’t recommend either of these personally as I have not yet tried them, but I am willing to try them when my renewal comes to term). But if you do try them please report back on how it all went.
I am currently 50/50 with Fixed 1.0% / SARON.
Also, 1.42 for 5yr also sounds bad to me. Swaps dropped again today so 1.18% - 1.24% is what moneypark / hypotheke are estimating for 5yr right now. I would want a 10yr for that rate.
For SARON - I think there were a lot of people saying that the banks raised the minimum from 0.5 to 0.6% on margin within the last 1-2 years.
I can tell you I was offered 0.6% margin in that timeframe.
So I’m guessing it is possible to still get 0.6% since both websites seem to show that. As for what specific bank and what requirements, income statements etc factor into that I’m not sure.
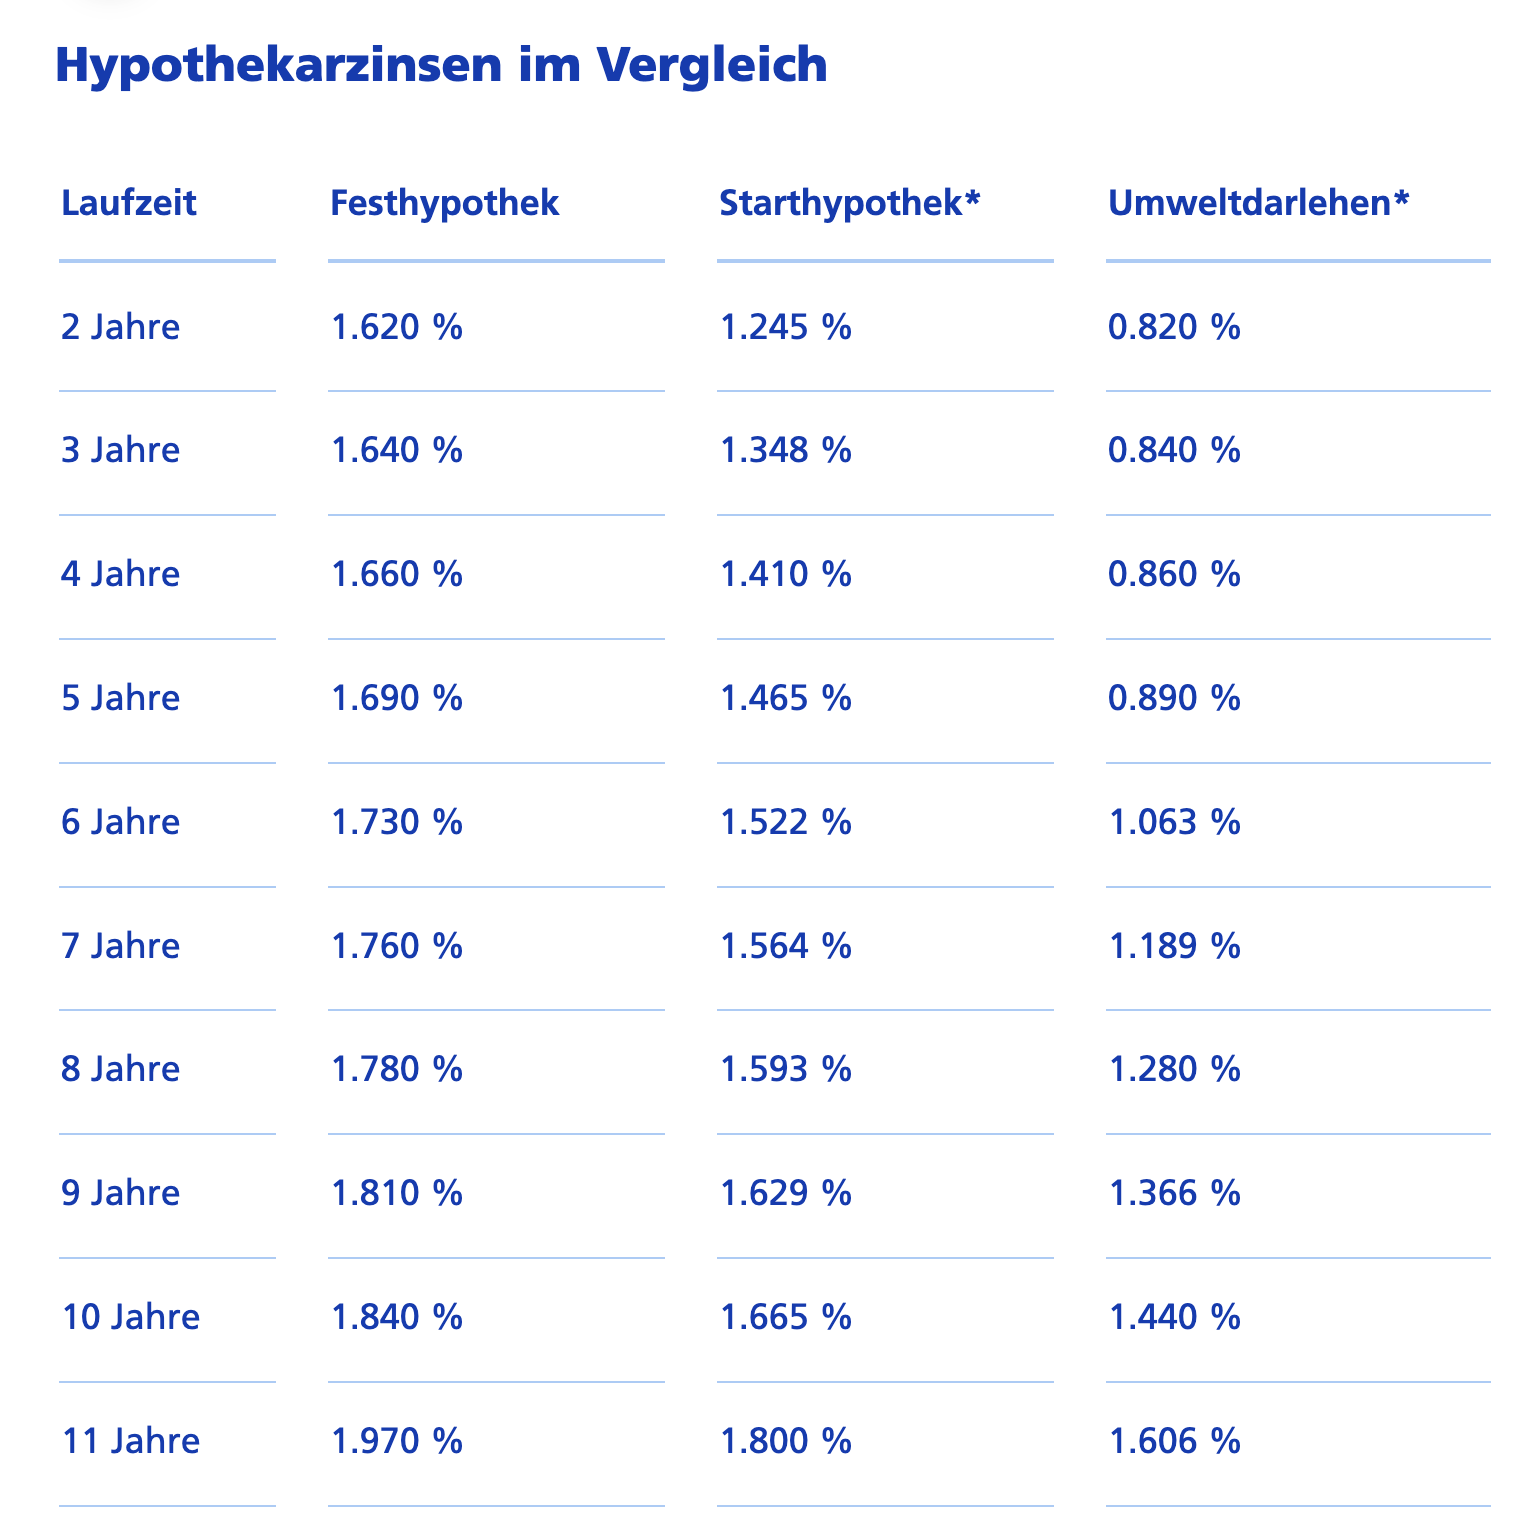
Quick question to all, why is ZKB interest rates so bad? It’s like 0,5% higher than the moneypark.ch and hypotheke.ch. I know that what is listed on these two websites are not achievable, for buy-to-let. Adding 0.1% or 0.2% I can understand, but ZKB, adding 0.5%, seems so bad…
fixing 10 years 1.84%
and saron margin is 1.1%
Is the bank known for this bad rate? It is our default bank and it would be nice to go with them, but this looks like “cannot-be-worse”. Any first hand experience interacting with ZKB for the mortgage rate?
My experience with ZKB is that they are that bad. Had direct discussion and showed also counter offers and the rate they were offering was a bit better than what they have on the website but still far from what others could offer. I think they just have so many “lazy” people that have them as their house bank and just use them by default that they are not interested in offering better rates.
thanks for the reply. In your experience, are they generous with the affordability, namely offering better LTV ratio? Or as strict as other banks? If LTV is better, then maybe that’s one good reason to go with them nevertheless. Otherwise, it is just hard to find an advantage.
These are their website “rates”, therefore only indicative (and pretty terrible). Pretty sure the website rate are a worse case scenario, or maybe it’s just to rope in anyone gullible enough to sign up cause that’s where they bank (without shopping around or asking for a competitive rate).
I’m sure if you were to talk to a rep. they would send you a pdf version of their daily “competitive” rates which will be better than the posted ones.
(still doubtful you will find rate leaner as what might be obtainable from a broker, since they have a good “brand” & customer service).
What this shows is that they have no appetite to finance old buildings which is actually a recent trend as renovation costs tend to explode and are therefore more risky to have as collateral for a bank. ZKB is not the only bank with different rates based on energy efficiency of properties… Their environment friendly building rates are in line with other banks published rates.
I talked with them when shopping around and the rates were competitive, even before these starter and energy-efficient offers.
Think about shopping online. I bet marketing people have a term for this.
For a flight or hotel room: You get teased by offers like “your desired location starting at 99,-“. Once you add your details, you end up at 299,-. Plus luggage and a convenience fee for booking online.
A toy: MSRP “99,-“. You might find the same thing for 79,- incl. shipping somewhere, or -59,- at a sale or using some discount.
ZKB’s published rates follow approach 2). At least they publish something, and you’d have to consider these rates minus your offered and then negotiated personal discount.
In both cases, you should go through the ordeal to get, compare and negotiate a personal offer.
It does appear like some lenders raised margins on the fixed rates too. The swap rates are lower now than in august, yet the fixed rates seem to be the same.
(therefore it seems lenders increased fixed margin of about 0.1 - 0.2% as shown in the graph).
“Basel III is leading to an increase in interest rates for some mortgage lenders”
“In addition, some lenders are currently a little less aggressive because they have already achieved their targets for 2024”
It seems to align well with my experience where SARON margins of 0.5-0.6 have been very hard to find in the past few months, and they are closer to 0.7-0.8 now.
“In addition, some lenders are currently a little less aggressive because they have already achieved their targets for 2024”
I’ve been explicitly told the same by multiple banks. They didn’t actually seem interested in my business.
This may be a very basic question, but can someone here please explain to me why banks anticipate an increase in interest rates for 10y fixed mortgages in December 2024, although the SNB is expected to lower the “policy rate” mid-December? Shouldn’t the mortgage interest rates for all durations go down in parallel to the SNB’s rate?
Not becessarily, the yield curve is upward sloping normally (and it has normalized for longer durations). Meaning longer terms have higher interest/yield, as you are taking term risk, and market participants demand to be comepsated for said term/duration risk.
The current curve already prices in future policy rate developments. But further out than a few years you‘ll generally have a different dynamic.
Mit dem Lesen und der Teilnahme an diesem Forum bestätigst du, dass du die Forum-Richtlinien gelesen hast und damit einverstanden bist sowie den Haftungsausschluss auf http://www.mustachianpost.com/de/ akzeptierst.