# Share your net worth progression
**URL:** https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798
**Category:** Investing / Portfolios
**Created:** [November 29, 2020, 3:07pm UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798 "2020-11-29T15:07:54Z")
**Posts on this page:** 20
**Page:** 47
### Author:  [@Abs\_max](https://forum.mustachianpost.com/u/Abs_max)
#### Post date: [December 30, 2024, 2:25am UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1004 "2024-12-30T02:25:27Z")
That’s the thing -: most significant returns in equity markets mainly come from concentration. But even a larger number of portfolios suffer due to concentrations. Mostly we talk about the first group 🙂
Folks who are heavily exposed to Mag 7 either by luck, Choice, rules, or ignorance must have significantly outperformed market over the last few years. The question is always at what point this changes and would they diversify in time.
---
### Author:  [@Joe\_Coconut](https://forum.mustachianpost.com/u/Joe_Coconut)
#### Post date: [December 30, 2024, 10:03am UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1005 "2024-12-30T10:03:50Z")
It can go either way…
I know guys who worked for citibank in 2007 and had been there for a long time (= lot of unlocked company stock)
The stock did horribly. But back then banks were the untouchable gods and the place to make money. So who could have expected this?
---
### Author:  [@arthur](https://forum.mustachianpost.com/u/arthur)
#### Post date: [December 30, 2024, 1:58pm UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1006 "2024-12-30T13:58:53Z")
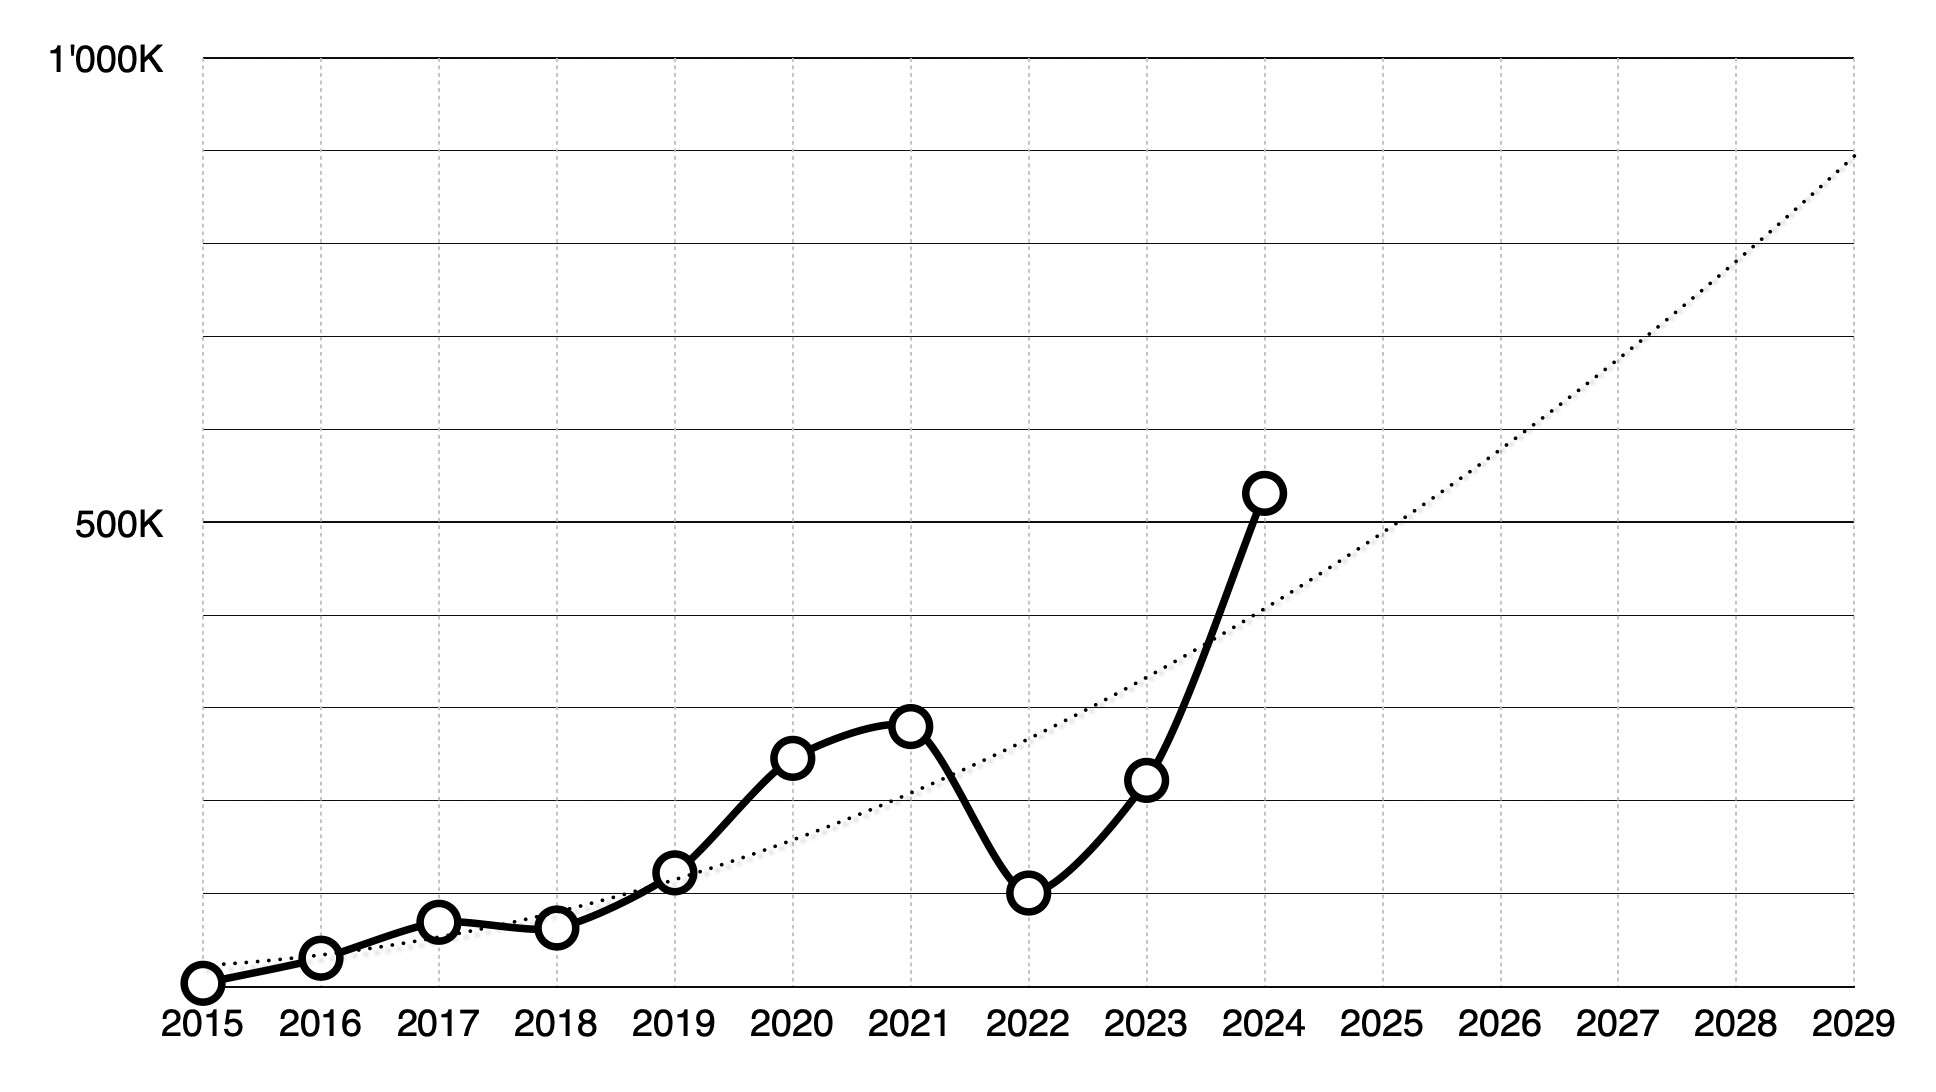
I set out to reach 500k EOY when I started investing ten years ago and thanks ot a stellar market it somehow worked out. I’ve given up on my timeline at some point after having had a terrible drop from 300k down to a low of 96k in 2021. I am equally glad and surprised to have recovered so swiftly! 80% stocks, 20% VT.
---
### Author:  [@Tony1337](https://forum.mustachianpost.com/u/Tony1337)
#### Post date: [December 30, 2024, 2:33pm UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1007 "2024-12-30T14:33:27Z")
> [@Abs\_max](#):
>
> Mostly we talk about the first group 🙂
Yep, as almost nobody will post the loser portfolios online. And if so, nobody cares for them (except the occasional yolo bets of wsb people).
This skews the picture a lot.
It‘s a big deal if I win the Lotto tomorrow, but nobody cares if I lose it.
---
### Author:  [@1742](https://forum.mustachianpost.com/u/1742)
#### Post date: [December 30, 2024, 2:50pm UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1008 "2024-12-30T14:50:25Z")
Congrats on reaching your target! When you say 80% stocks and 20% VT, do you mean 100% in equities with 80% in individual stocks? That is an impressive risk profile…
---
### Author:  [@arthur](https://forum.mustachianpost.com/u/arthur)
#### Post date: [December 30, 2024, 3:33pm UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1009 "2024-12-30T15:33:26Z")
It is indeed 100% equities, but no options. With quite a long investing timeframe in mind, I am hoping I should be fine and benefit from big years like this year.
---
### Author:  [@anon17469660](https://forum.mustachianpost.com/u/anon17469660)
#### Post date: [December 30, 2024, 6:03pm UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1010 "2024-12-30T18:03:42Z")
At my stage I am more forward looking than backward looking. Still, some recent and mostly\* current numbers, as I have just swung onto my horse to ride into a ~~Marlboro like~~ Altria-dividend-paying sunset:
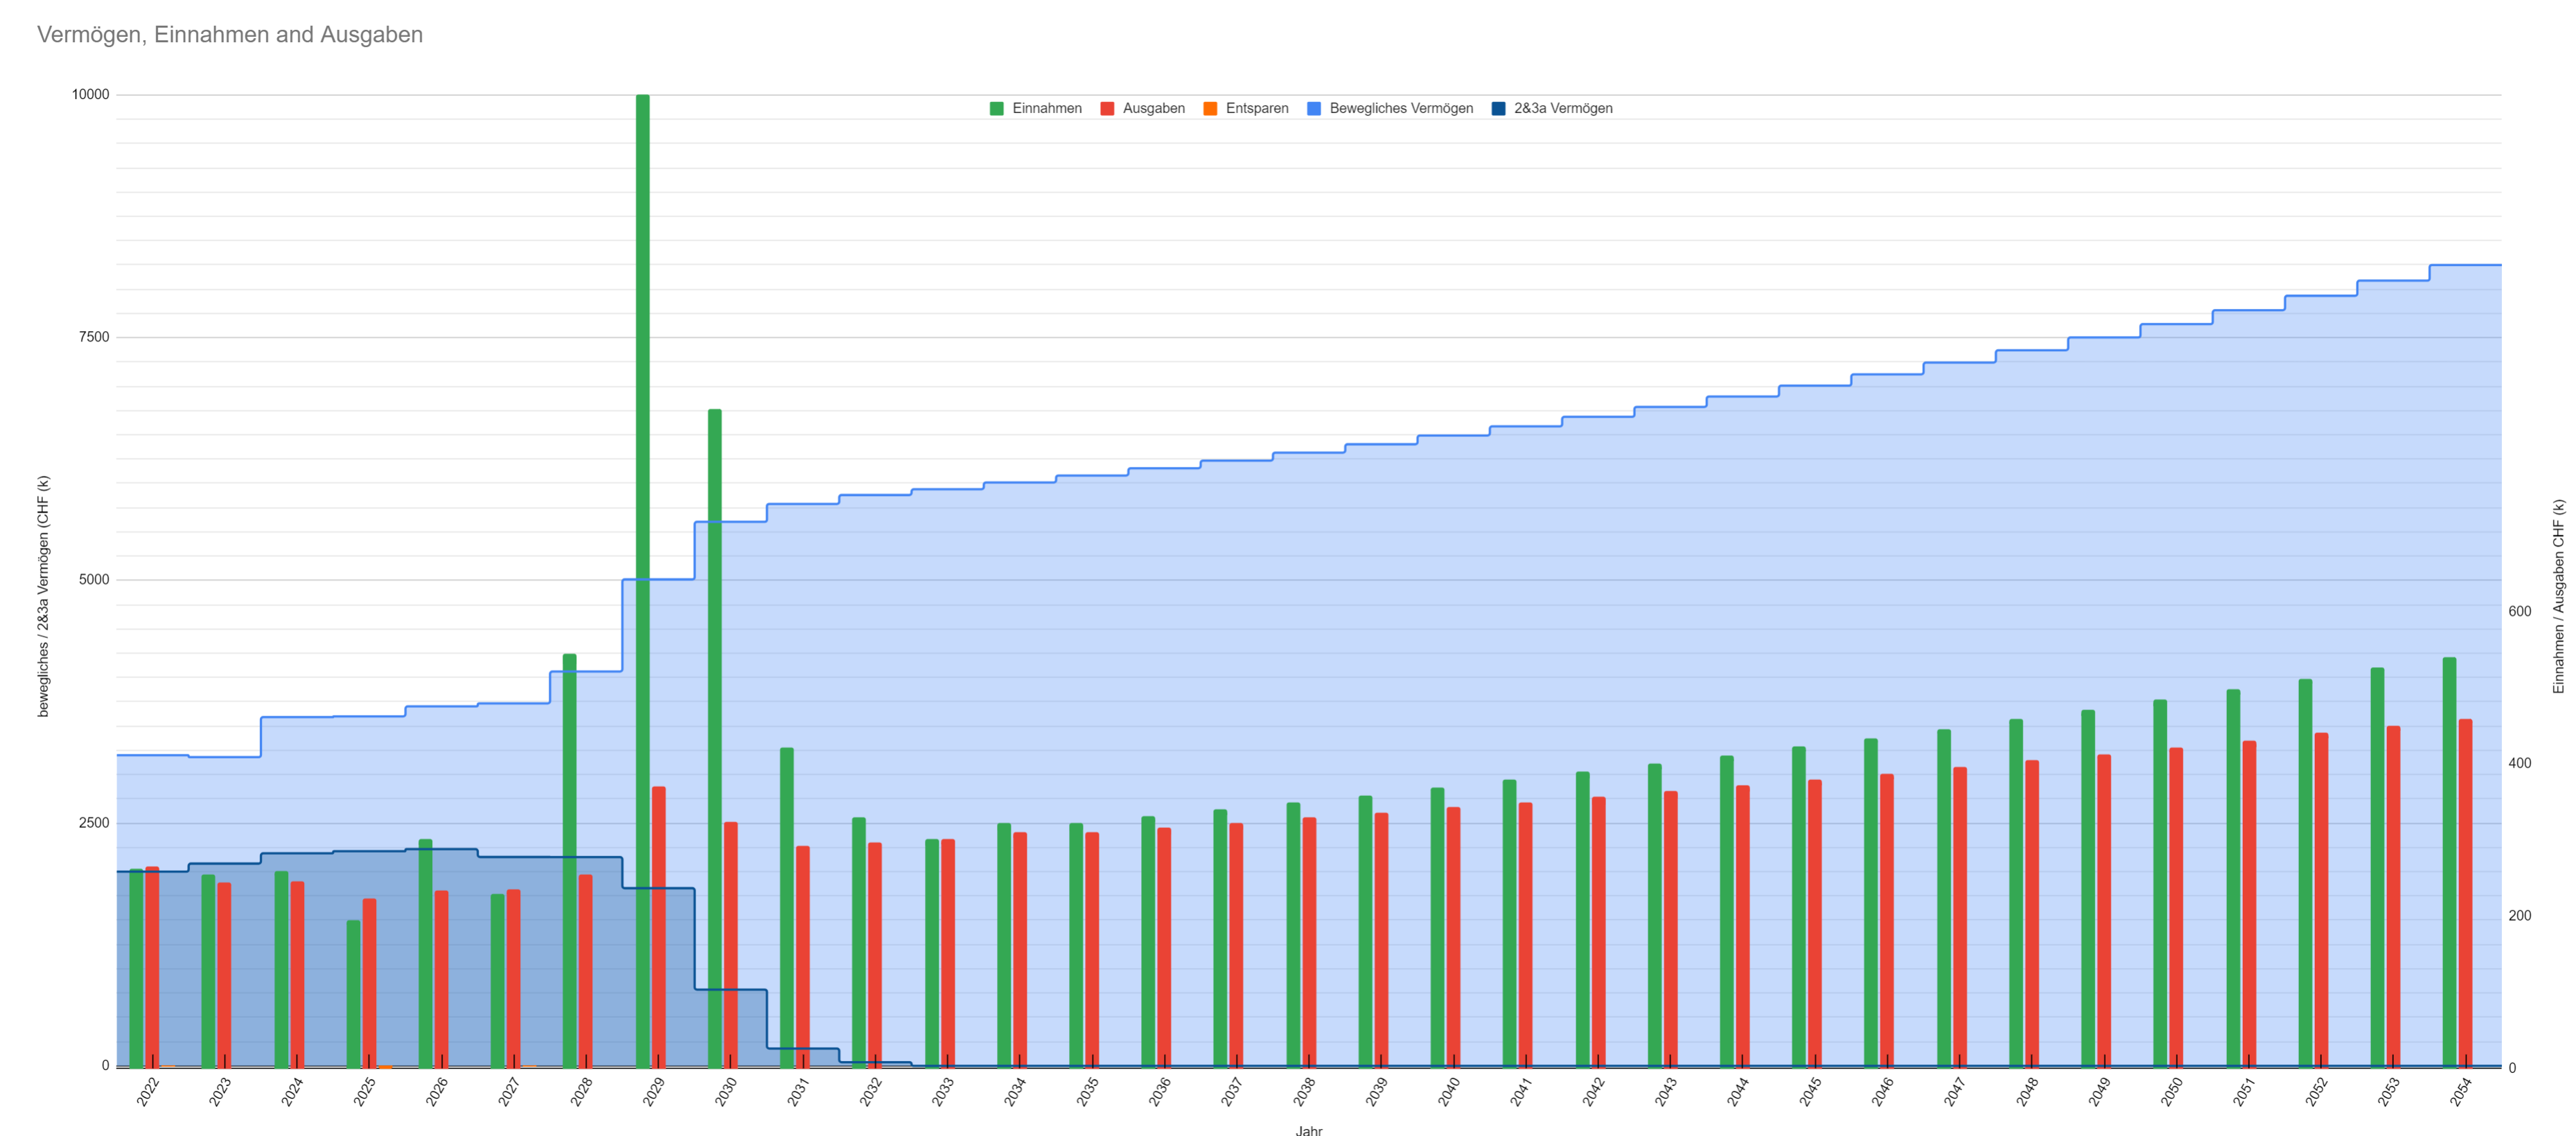
Next couple of years are probably somewhat accurate numbers wise, the rest is projections with these assumptions:
- dividends growing annually by 3%
_Ceteris paribus_ – all other things being equal – dividends have grown
- this year and on average in the past five years: 4.5%
- in the past ten years on average: 6.6%
- capital growing (without dividends) with a CAGR of 1%
(total CAGR – including dividends – has been about 15% since mid June 2019)
- 0.2% housing cost inflation, 1.4% cost of living cost inflation, steady housing and living costs base line otherwise.
- pillar 2 and 3a capital withdrawals are taxed as today
* * *
Just to satisfy my 10 figure (Rappen) target, let’s dial dividends to growing at 4.5% and capital growing at 1.1%:

* * *
Anyone intending to comment that I am not depleting my stack fast enough: you’re damn right, and I hope it remains that way!
🍻
* * *
\* Don’t you gals and guys know that the market will swing another 20% tomorrow on its last 2024 trading day? Sheesh!
---
### Author:  [@gaijin](https://forum.mustachianpost.com/u/gaijin)
#### Post date: [December 30, 2024, 6:41pm UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1011 "2024-12-30T18:41:39Z")
> [@arthur](#):
>
> 80% stocks, 20% VT
Just for my understanding: do you mean 80% individual stocks? I’m asking because VT is an ETF which is composed of stocks, so it could technically also be considerd stocks.
---
### Author:  [@dbu](https://forum.mustachianpost.com/u/dbu)
#### Post date: [December 30, 2024, 7:27pm UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1012 "2024-12-30T19:27:44Z")
> [@anon17469660](#):
>
> 
>
> Next couple of years
I’m confuzzled - You are anticipating 10M CHF income in 2029, then 6M in 2030? 😅
Edit: I am probably reading the axes wrong.
I see the right one is on a different scale (and for Einnahmen).
---
### Author:  [@anon17469660](https://forum.mustachianpost.com/u/anon17469660)
#### Post date: [December 30, 2024, 8:13pm UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1013 "2024-12-30T20:13:37Z")
> [@dbu](#):
>
> You are anticipating 10M CHF income in 2029, then 6M in 2030?
That’s it! I’ll DM you the IBAN details to help me stay on course with those projections.
More seriously:
Yes, cash flows are on the right vertical axis, settled (or desired) balances are on the left vertical axis.
---
### Author:  [@nabalzbhf](https://forum.mustachianpost.com/u/nabalzbhf)
#### Post date: [December 30, 2024, 8:20pm UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1014 "2024-12-30T20:20:37Z")
> [@anon17469660](#):
>
> At my stage I am more forward looking than backward looking. Still, some recent and mostly\* current numbers, as I have just swung onto my horse to ride into a ~~Marlboro like~~ Altria-dividend-paying sunset:
>
> 
btw consider doing a stacked graph for the net worth? (it’s a bit weird to see it go up when it’s actually distributed differently between taxable assets and retirement assets)
---
### Author:  [@arthur](https://forum.mustachianpost.com/u/arthur)
#### Post date: [December 30, 2024, 8:24pm UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1015 "2024-12-30T20:24:05Z")
You are right and as you have correctly figured i simply wanted to say it is 80% individual stocks vs. 20% etf. 🙂
---
### Author:  [@finalcountdown](https://forum.mustachianpost.com/u/finalcountdown)
#### Post date: [December 31, 2024, 8:54am UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1016 "2024-12-31T08:54:53Z")
What is your (target) asset allocation ? You indicate dividend stocks, what stocks do you target here?
If I understand your graph you anticipate in 2033 (at full retirement?) 300k income with a 6M stache? How much is this in terms of (post tax) portfolio return vs AHV/pension?
---
### Author:  [@anon17469660](https://forum.mustachianpost.com/u/anon17469660)
#### Post date: [December 31, 2024, 9:51am UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1017 "2024-12-31T09:51:07Z")
I think I mostly already am at my target allocation (for the taxable assets), which is about 3/4 the stock picked portfolio, 1/8 ex US equity (VXUS) and the rest in bonds (BND, BNDX, VDET).
The allocation doesn’t have some big return theory behind it, it’s just what I feel comfortable with and what produces the cash flow that I need as income.
For dividend (growth) stocks I try to pick those that reliably pay, and ideally keep raising their dividend. I’ve linked to my picks in [this post](https://forum.mustachianpost.com/t/any-stockpickers-out-there/8203/28). The topic of said post also discusses how I (and others) arrive at potential picks.
I haven’t run the numbers to compare to pension return, but I would accept a lower return on my portfolio in order to pass on an inheritance. As it stands today, the (entire taxable) portfolio returns 4.3%. When I’m eligible to withdraw capital from pillar 2 (or the _Freizügigkeitsstiftungen_), I’ll aim at investing with an initial 3% return, most likely into the stock picked portion of the portfolio.
I don’t know how to compare to AHV, as regardless of what I paid in I’ll get a mostly fixed amount out starting 2033.
Full retirement is hopefully earlier than 2033 … I’m reducing from 50% to 10% starting next year (tomorrow!), and depending on how comfortable I’ll feel with this setup I might dump the remaining 10% in a couple of years as well.
---
### Author:  [@Mirager](https://forum.mustachianpost.com/u/Mirager)
#### Post date: [January 1, 2025, 11:25am UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1018 "2025-01-01T11:25:38Z")
YoY sum says 17% gain in stocks and 16% in 3A, pretty damn good. Onwards and upwards.
Edit: probably not super accurate, I’d planned of doing some sort of analysis of what % did the 2023 tranche do, what did individual tranches in 2024 did etc but in the end can’t be arsed, it’s just EoY value of 2023 vs EoY 2024.
---
### Author:  [@Wolverine](https://forum.mustachianpost.com/u/Wolverine)
#### Post date: [January 1, 2025, 11:46am UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1019 "2025-01-01T11:46:51Z")
Well, it’s been an interesting year.
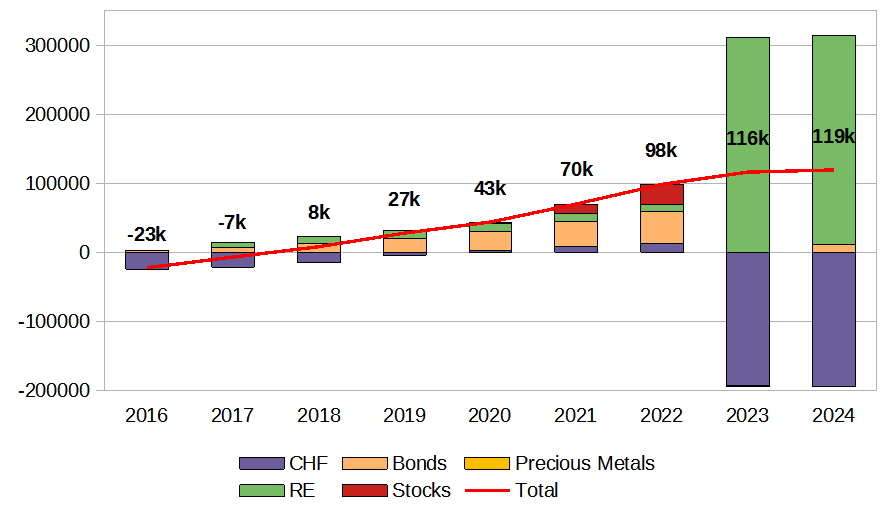
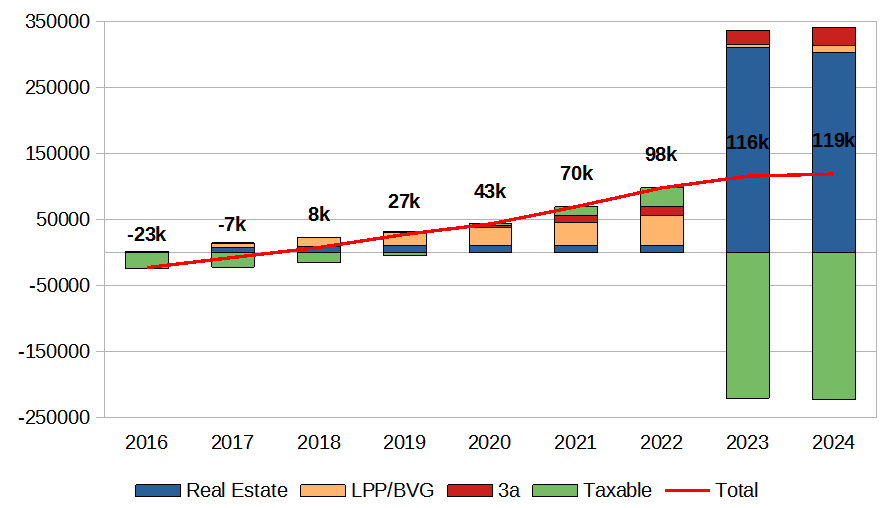
- lower salary (80%);
- two months without salary (between jobs).
I’ll still have to deal with real estate this year so not much will be invested in stocks but things should start to normalize in 2026 if life pretends to be normal until there.
---
### Author:  [@Balaclava](https://forum.mustachianpost.com/u/Balaclava)
#### Post date: [January 1, 2025, 12:59pm UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1020 "2025-01-01T12:59:55Z")
Happy new year folks!
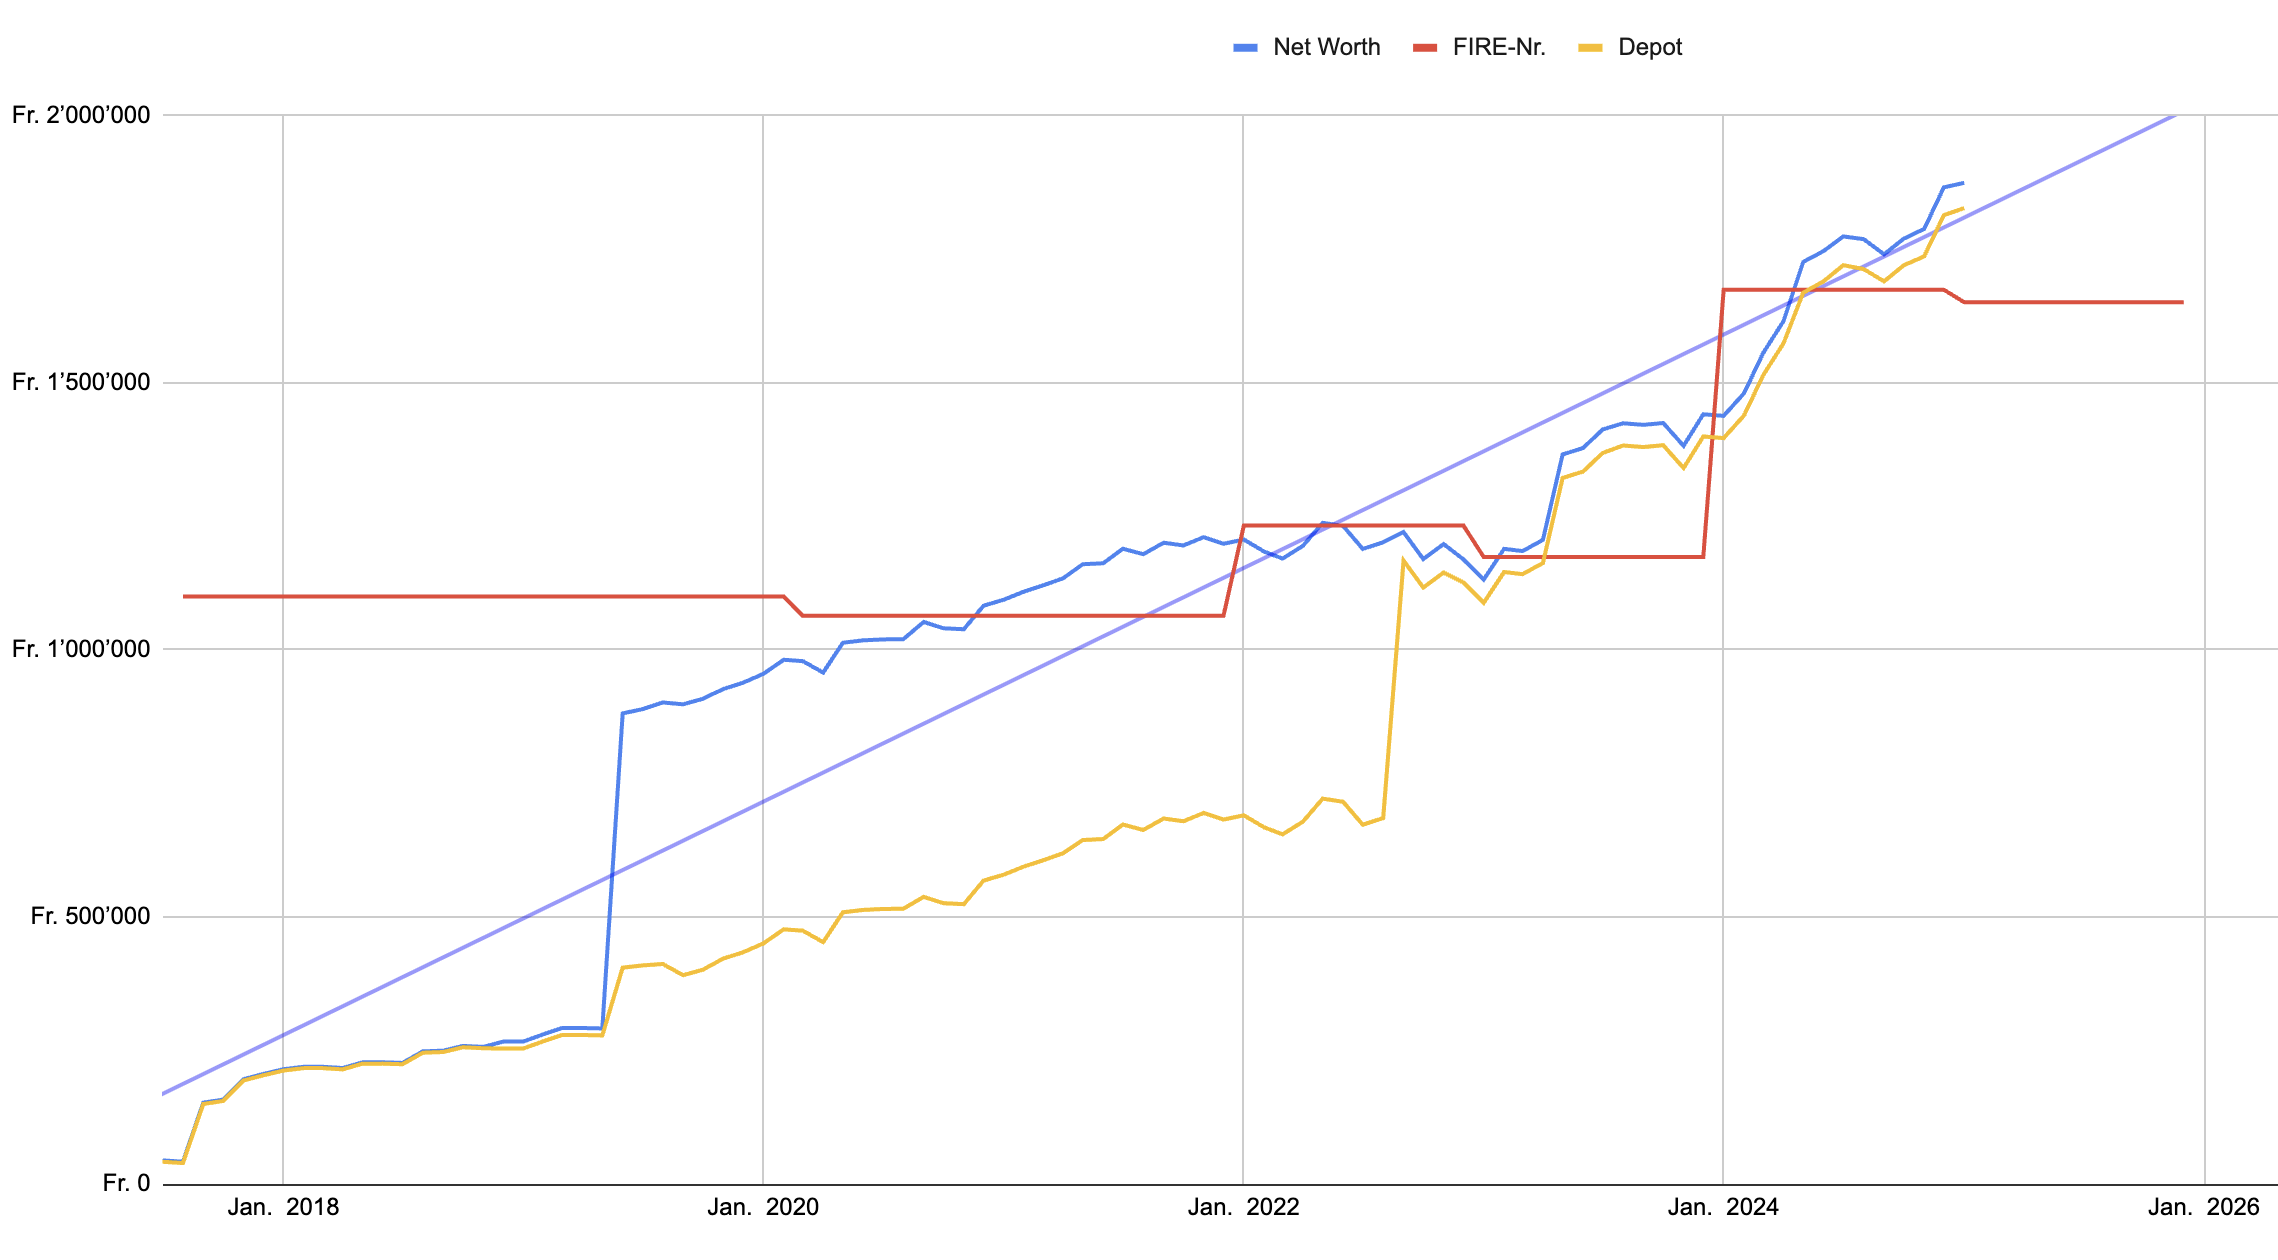
Here’s my update:
YTD 30% + 436k (approx. 150k where savings, the rest stock market performance). Had to raise my expenses due to health issues, but the performance kept me well above my FIRE-Nr. ;-):
---
### Author:  [@1742](https://forum.mustachianpost.com/u/1742)
#### Post date: [January 1, 2025, 4:03pm UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1021 "2025-01-01T16:03:30Z")
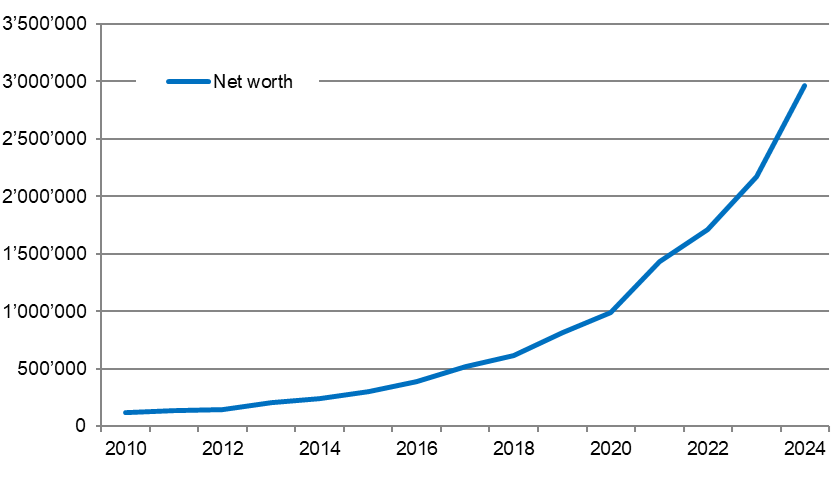
Preliminary, that is +36% YoY, with roughly 21% asset return (with individual stock picks somewhat underperforming) plus new savings. New savings in 2024 went already more towards 1e pension fund with lower equity exposure and increasing share of uninvested cash, and I plan to repeat that in 2025 (market timing, expecting some turmoil once Trump is acting president).
Having reached my lean fire target in early 2024, and given that reaching my actual fire target in 2025 is pretty much guaranteed (unless there is a severe market crash), the main goal for 2025 is to switch to a less demanding job, at the cost of course of also exiting an extremely well paid job. Let’s see if that works out. Happy new year to everyone!
---
### Author:  [@jes](https://forum.mustachianpost.com/u/jes)
#### Post date: [January 1, 2025, 8:22pm UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1022 "2025-01-01T20:22:30Z")
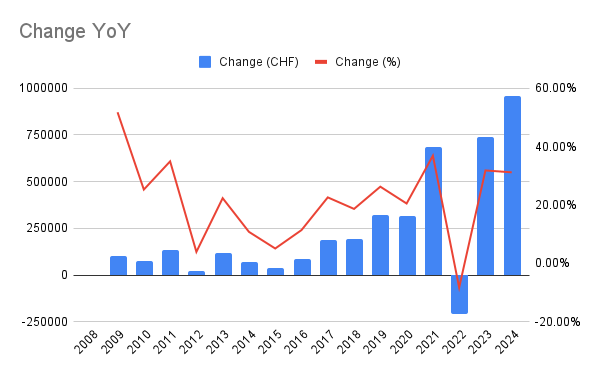
I didn’t think there was much of a chance of 2024 matching 2023, let alone being significantly better. But it was. Milestones reached:
- Broke 4M CHF net worth
- For the first time, made more from investments than from employment, though it’s of course mostly unrealized gains
- For the first time, had enough income from just dividends to pay for my current lifestyle (I’m not really optimizing for dividend yield)
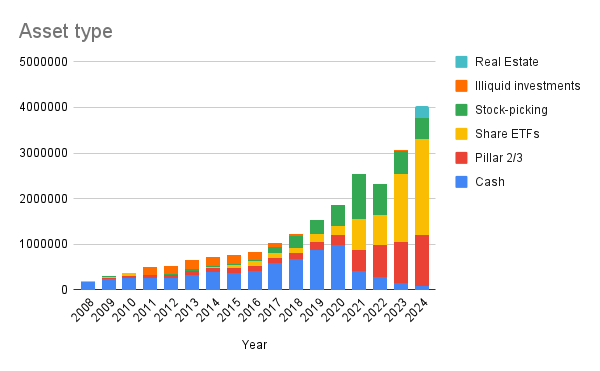
My target allocation was 66% shares, 34% other asset classes, and with at most 500k CHF in the stock-picking portfolio. I undershot the share allocation a little bit in the end (63%) to finance the down-payment for an apartment, but it’s still within acceptable tolerances.
I’m now comfortably over my FIRE target. It might become harder and harder to justify working, but I don’t have a fixed RE date set yet.
---
### Author:  [@Cortana](https://forum.mustachianpost.com/u/Cortana)
#### Post date: [January 1, 2025, 9:15pm UTC](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798/1023 "2025-01-01T21:15:29Z")
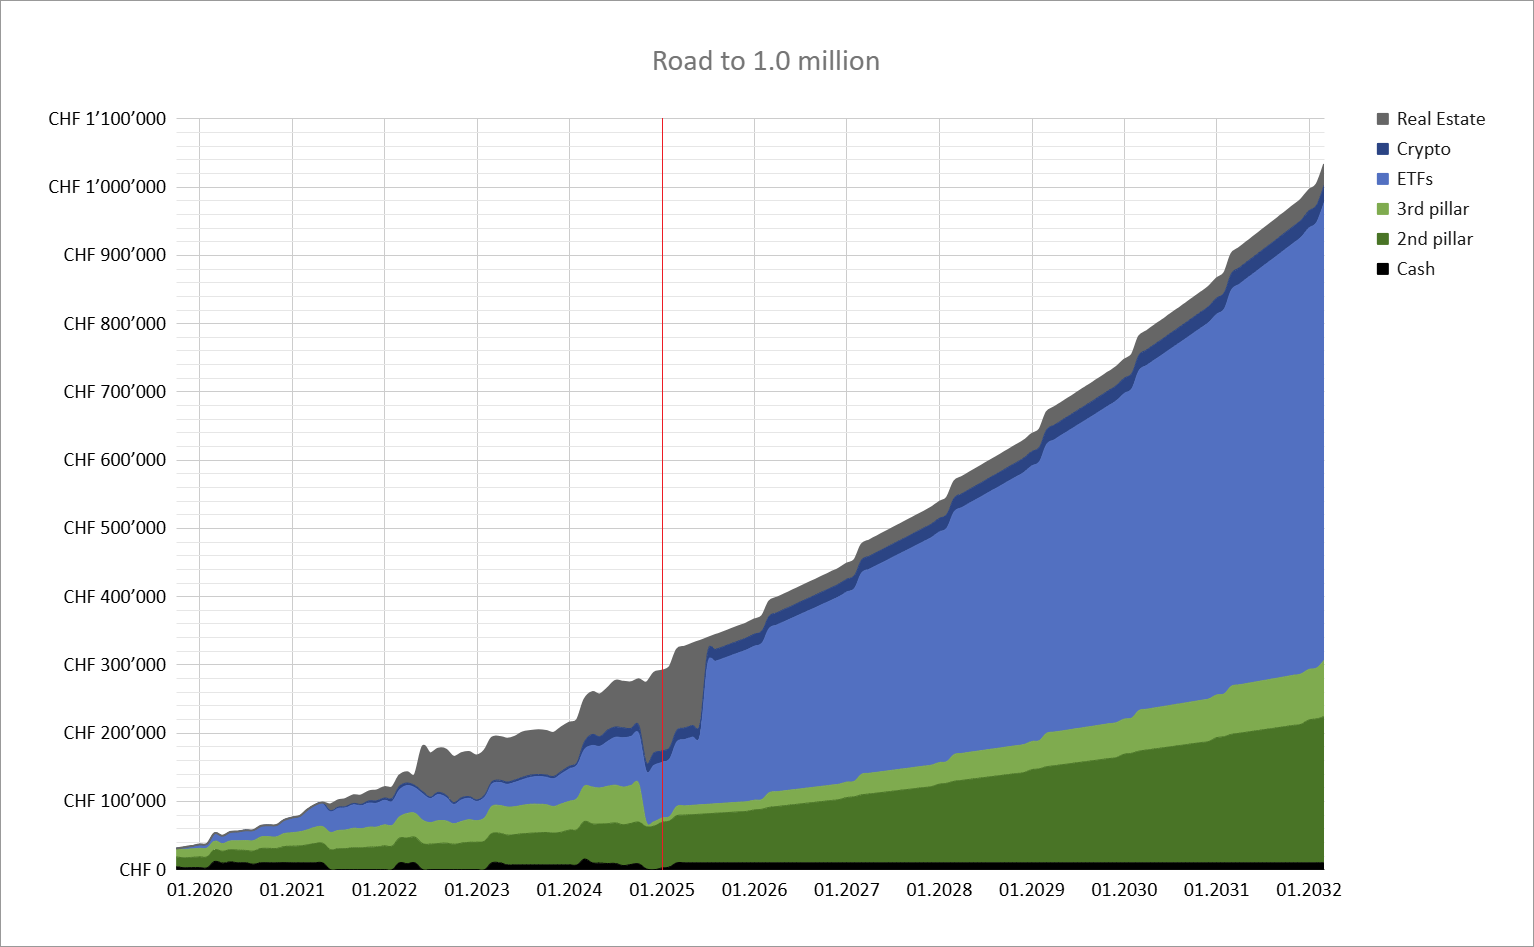
End of each year:
**2018:** CHF 17’595
**2019:** CHF 36’855
**2020:** CHF 76’372
**2021:** CHF 120’874
**2022:** CHF 167’285
**2023:** CHF 215’398
**2024:** CHF 291’378
Quick explanation: In October 2024 I withdrew 50k from my 3rd pillar to reduce the mortgage (thus increase home equity). I did that because I’m in the process of selling this apartment and will use the freed-up funds to invest in ETFs in my taxable account. I’m assuming I’ll sell the apartment by June 2025.
[Previous page](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798.md?page=46)
[Next page](https://forum.mustachianpost.com/t/share-your-net-worth-progression/4798.md?page=48)