Yes! But make them ‚phenomenal‘:
1 Like
A more logical approach is to stick with a standard investment plan and ignore market fluctuations entirely.
An investment plan is a long-term commitment. You select the components and ratios based on your needs (stability vs. returns). You select the size of your recurring investment based on what you can realistically afford to live without. Then you stick with that.
Reducing the cash component in favour of the stock component in order to “buy the dip” would require a complete rethinking of your investment plan.
My personal suggestion is to ignore your portfolio and market news entirely and just let your investment plan run its course.
Or there is the other option of “timing the market” which is, of course, more exciting. But unless you have in-depth/insider information about a specific asset, then it’s akin to a game of roulette. Not exactly a sound investment plan, but it’s great entertainment and you might get lucky.
6 Likes
In tech: I will buy Microsoft if it drops to 320-330. that’s my buy zone as I feel it is still a bit pricey at 359. I really like ServiceNow (strategy, GTM, CEO, etc) but it is way too expensive
Outside tech, I like healthcare because I know med-tech but tarrifs are really impacting these and I need to think a bit more where the opportunity lies
2 posts were merged into an existing topic: Present and Future of Bitcoin [2025]
Here you are wrong. Bear markets are exactly the point where a strategy will have its greatest effect. The problem usually is not the strategy; it is you not behaving according to your strategy. Or worse, not even having a strategy.
I use only mechanical strategies. In hindsight bear markets are where I made most money…after they were over. But it means you have to trade against every fiber in your body and that hurts a lot.
I use margin in bear markets, buy a lot on credit. That is risky and the money management must be very strict. But it works, at least it did work. Even if the bear market goes on for many years, there is enough movement to profit even during this time.
But if you do “buy n’ hold” and probably do monthly buys you should just continue to do so. Because here is the difference to the masses; they sell and lose money.
I don’t know, nobody does. I have my mechanical set of rules to define when to acto how. But yes, the easiest definition is that it starts at 80% of last high and is over at 95%. That was only a few days last time.
If you are interested in the details check for my bear market protocol / crash recovery strategy in this thread: Mechanical investment strategies
If there was a way to know what is a dip to buy, most traders would mint money. But they don’t. So it seems we can conclude there is no way to know what’s the dip and what’s a falling knife.
All of this is known only in retrospect.
Having said that - for a moment of joy, buying on red days gives a feeling of “I timed it well” even though in long run it doesn’t matter much.
1 Like
No, they don’t. It is a behavioral question. Just check margin credit rates: they are lowest in a bear market and highest at the top of a bull market. My personal statistic is exactly the other way round: margin credit is highest in a bear market and lowest in a bull market.
Everybody knows in theory what to do, it is easy… on paper. Buy for less than you sell, that is all really.
But after losing seven figures, more than half of your money probably saved over many years for retirement… not much people stick to the plan. But that are exactly the moments where “sticking to the plan” would and is most profitable and makes the difference to the crowd.
An example I like to cite is Peter Lynch with his Magellan Fund. It was very difficult to lose money with this fund, Peter made the fund an average gain of 29.2% per year. But he once said that most of his clients did lose money with his fund: they bought at the top and sold at the bottom… 
Ask yourself if you are able to stick to a plan when more than half of your money did disappear due to a bear market. Most people cannot do that. But it is the single most important moment to stick to the plan!
1 Like
Many have likely read this a while back already; for those that didnt:
For buying the dip (with ETFs such as VT), there historically was a way to profit (a bit).
But only if you can print money out of thin air when the dip happens (or borrow it from someone; but then you could also have borrowed it before already in theory).
2 Likes
To be fair, wouldn’t be surprised if stock markets became further and further detached from fundamentals.
There was a clear buy the dip from retail in April, and retail keeps plowing money into equity regardless of prices (often with leverage which has more impact on prices)
Not quite sure what’s the end story there.
That’s true too.
Stock market is becoming like a fixed deposit where people simply assume it’s the safest bet of all times
This might also result in returns like fixed deposit
I think the important thing here is not “buy the dip” but “stick to the plan”. If your plan includes some form of buying cheap and selling expensive you always buy the dip, automagically.
There are too little bear markets to get real statistical evidence… of anything. It worked for me, even one time the timing was a bit off (bought too early). That it worked a few times (I think 3 of the last 4 bear markets, the 4th bear market was over too quickly to do anything) but that may be pure luck, too little data.
As I said, the most important thing is you! Can you stick to the plan after losing half or more of your retirement money, probably many years of pay for hard work? Not many can and most do not know their own behavioral risk in those situations. However, if you invest for decades it is almost sure that you will encounter such a situation. And exactly how you behave in this situation is what defines your future.
Isn’t this considered to be the case already, both empirically and theoretically? A 15-year long bull means most of us here and elsewhere haven’t ever seen a bear, but the Ben Felixian data show that “all stocks, all the time” seems to lead to the best outcomes.
What needs to be true for this to happen? Do you mean that, thinking in terms of risk-adjusted returns, retail plowing in money and buying dips will soften all bears and but also dampen all bulls? I don’t think I’d agree to that because the risk taken is a risk out of retail investors’ control.
One issue is that if everyone does that, indiscriminately, you can create a massive bubble (nobody will price equity at the level where it should be). No idea how that bubble then unwinds.
(at some point equity becomes similar to bitcoin, it trades based on faith that more people will buy it later not fundamentals like revenue of companies)
2 Likes
I read we are off fundamentals for a while now, but also recall the video where Felix said you only need very little active investing to keep things efficient.
That’s the part I doubt, within the asset class maybe (stock A vs stock B), between asset classes it seems hard to resist all the money flowing into equity.
As far as I understand the literature.
Investors used to pay lower prices for stocks because they considered them risky and uncertain. That’s why the term equity risk premium because investors used to ask for premium to own stocks a bonds.
Nowadays. People think stocks are the sure thing. And they pay higher and higher prices for same earnings. So I think equity risk premium is reduced. This should also mean returns over risk free assets would also reduce
- Ben Felix says valuations are not market timing tool. I agree because markets can remain irrational for long time.
- But he also says long term returns are correlated with price you pay when you buy. If you pay more for earnings, your returns would be less.
My conclusion is that I don’t need to change my strategy. But I should temper my expectations.
I am kind of inclined to use Vanguard projection for 2-3% returns from global equities (measured in CHF) for the next 10 years.
This is not about risk premiums. This is about price of individual stocks .
I think valuations kind of move in tandem across the board.
If all companies in S&P are trading at 23 times forward PE, then 20 times PE wouldn’t be considered bad. But it’s still much higher than what people paid in past.
People may think stocks are the sure thing, especially unsophisticated people (=most), being battered by investment “advice” from social media, FOMO, and 15 years of bull.
I would strongly challenge that any substantial % of people in the real world are even aware of what “paying for future earnings” or “equity risk premium” even mean.
Why would whatever retail investors are doing impact the equity risk premium? The risk is still there all the time, so a potential for premium should be there too, no?
1 Like
As far as I know for S&P 500 , equity risk premium is calculated as follows
YE = earnings yield from S&P 500
YB = 10 year bond yield
Equity risk premium (ERP) = YE - YB
At this moment it’s negative or close to zero. This number used to be between 4-6%.
You can only say “risk” is still there if people ask premium to take on the risk. If people are buying stocks for same yields as 10Y Bonds, this actually means people are not really concerned or uncertain.
I am talking about people who invest in stocks (active investors or active funds). People who buy index funds are not really setting any price. They are merely providing liquidity to buy stocks based on what other active investors have decided to be the price. So we cannot really look at index fund flows as metric.
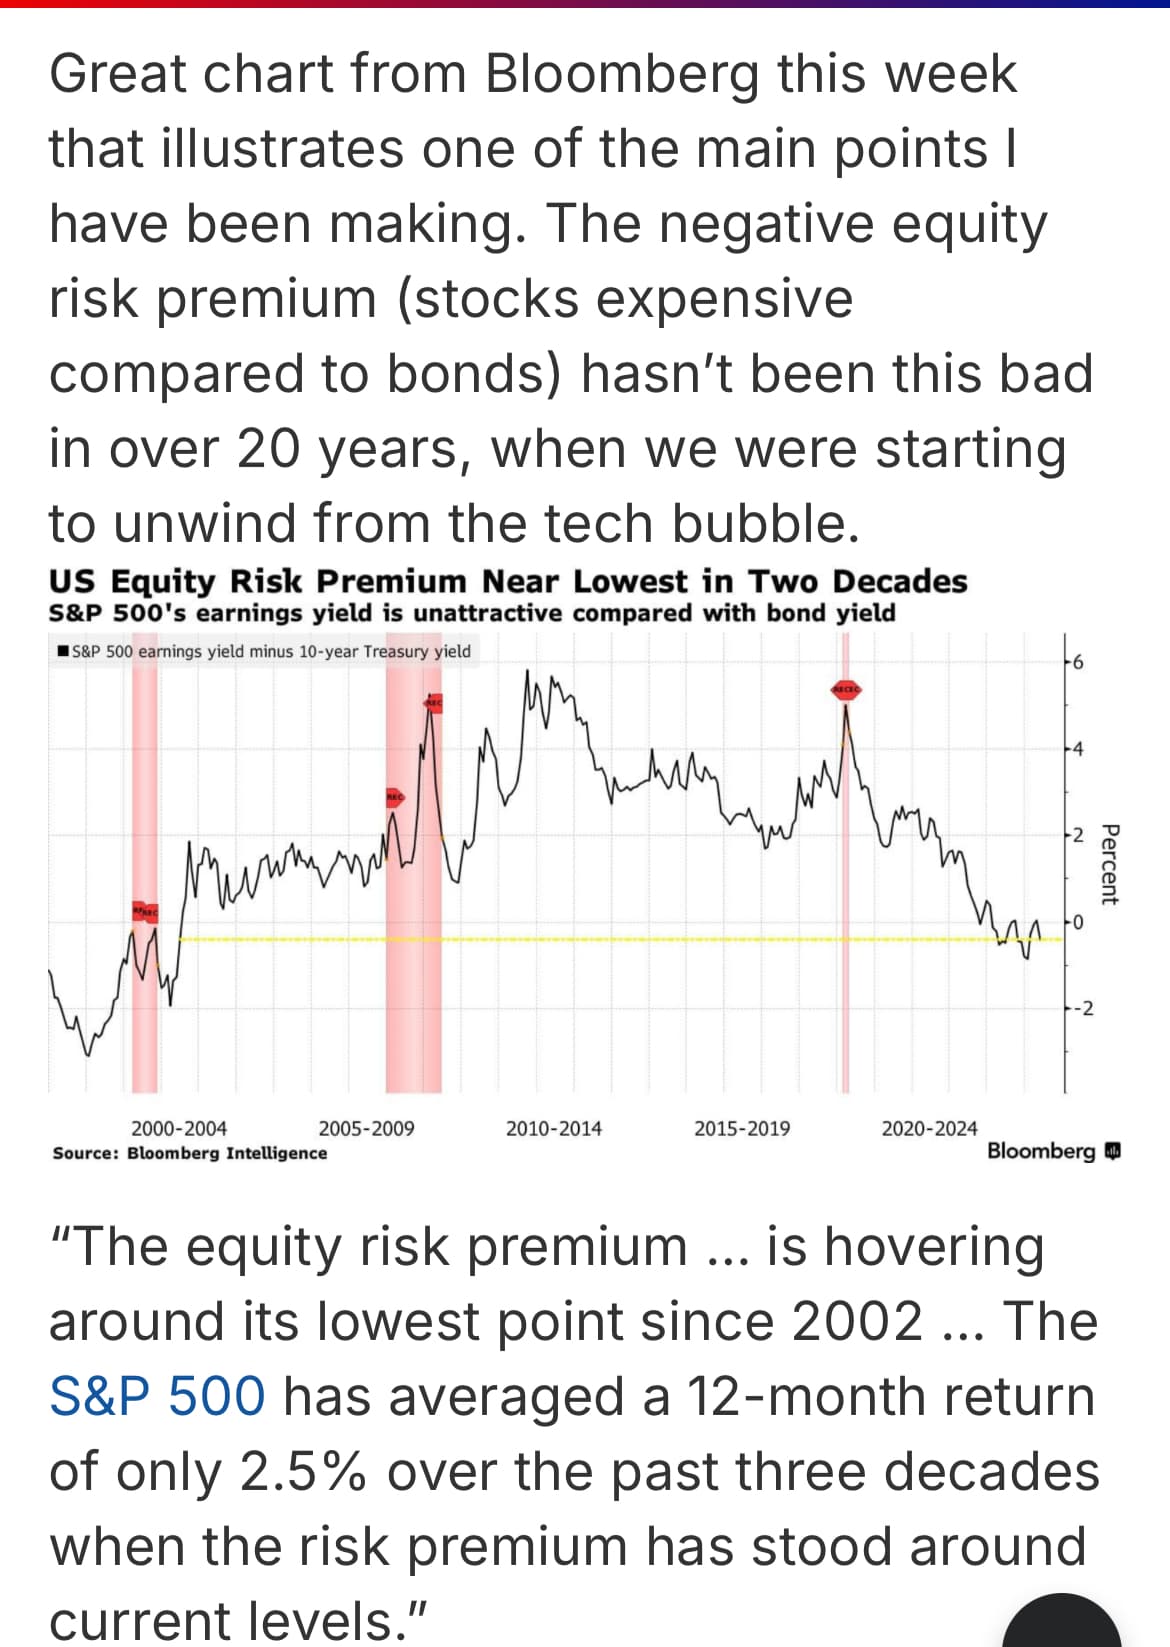
——-
I think this is result of long term strong performance by S&P 500. Investors are okay to get low ERP to buy these stocks. But I think then the same investors shouldn’t be surprised if their returns are similar to 10YR US bonds. That’s all
It can also happen that S&P end up delivering better than bond performance due to excellent earnings growth in future . But that’s the unexpected part of discussion.