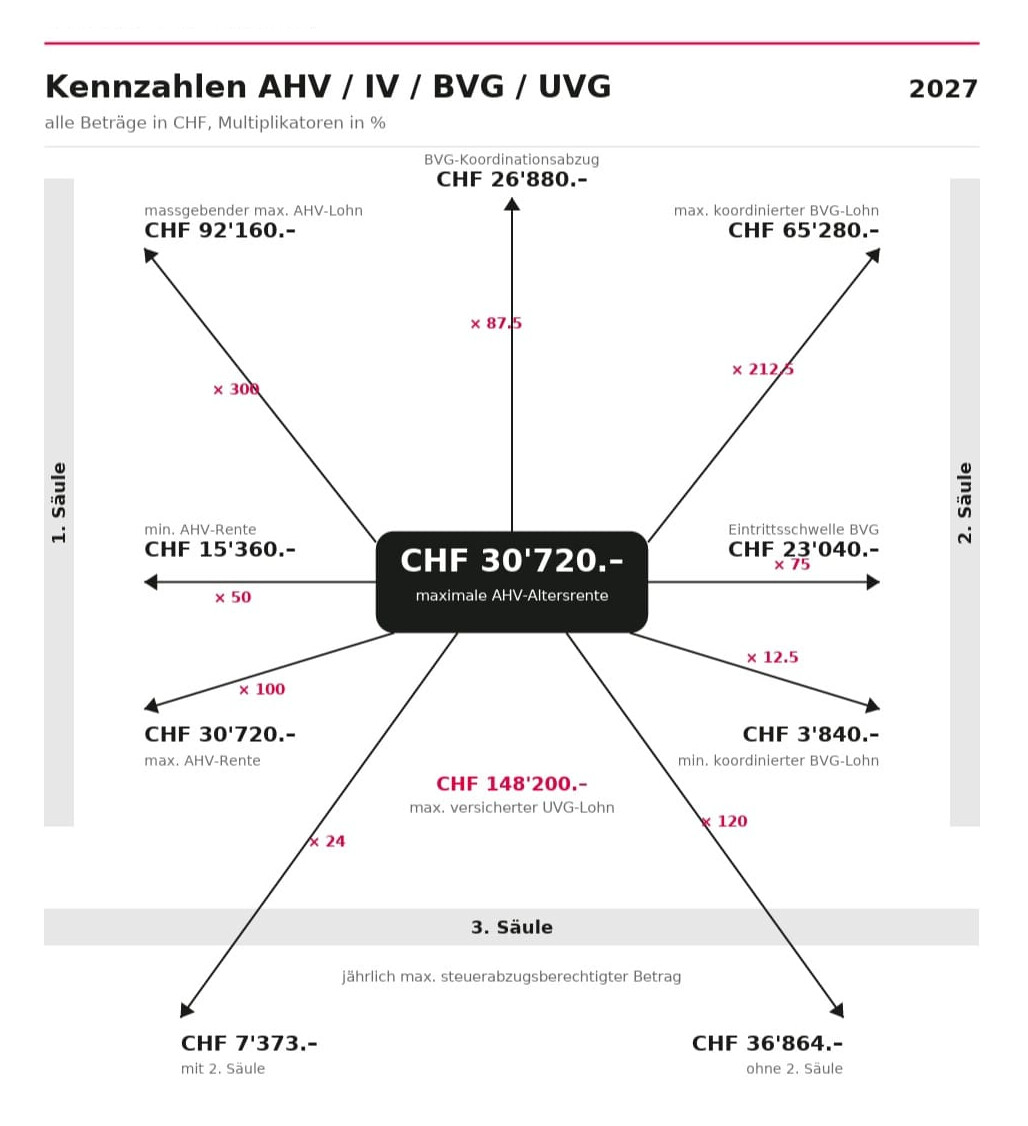
Fantastic, another value that isn’t evenly divisible by 12. 
Yeah CHF 7’374 would have been great. Would have worked for a regular standing order, even for 5 different accounts 
It is crazy how expensive pensions/AHV are. The increase in AHV costs 1B which is 0.1% of GDP. This half the ETH Zurich budget.
Err… the ETHZ doesn’t catter to 20% of the population? (Though, yes, research does cost more.)
I don’t know how it is a relevant metric in this context.
Quick question…
With 2nd pillar withdrawal possible only from age 60… it seems more logical to have 4 x 3a accounts rather than 5… Or I am missing something…
There’s no downside/penalty to having 5 (or more), so I’m not sure it matters.
And hard to know how legislation might evolve, the current state is a bit weird as it allow for tax optimization that don’t make economic sense – and there’s ways to fix it (e.g. always adjust for overall progression, potentially even counting all withdrawal done even early withdrawal for home ownership that haven’t been repaid).
60 up to and including 65, so 6 years. And one is for payout for 2nd pillar.
But this limitation to only being able to pay out a 3a account in full should be gone shortly, passed parliament without resistance.
I thought a withdrawal from 58 is possible, no?
Retiring from a pension fund, yes.
Not for withdrawal from a vested benefits account (such as finpension, VIAC, frankly) though.
Exactly … form pension fund it is still 58
From vested benefits, changed from 58 to 60 in 2024 (as far as I remember)
Not for the 3a. Under OPP 3 art. 3 para. 1, old-age benefits can be paid out at the earliest 5 years before the AHV reference age, so from 60 if your reference age is 65. Payout can be deferred up to 5 years after that age, but only if you’re still working. So the window is 60–65, or up to 70 if you keep working.
Before 60, only specific cases qualify: your own home or mortgage repayment, leaving Switzerland for good, self-employment, a 2nd-pillar buy-in, or a full IV pension when the disability risk isn’t insured.
The 58 is probably the 2nd pillar, and only if your fund’s rules allow it.
Sources: Fedlex · Le troisième pilier
If you’re creative you can spread it across ten years (WEF mortgage repayment), it’s just not always a good deal
We should start a petition. And maybe start an OCD party on the way.
P.S. The amount should be divisible by 60, so that one can pay the same amount in whole francs to 5 different 3a accounts every month.
7373 = 73×101
How could they have done this to us? 
It is on the Rappen level, 8% of 72 * minimum AHV = 7372.8.
Its just rounded from there.
Yes, and the amount is also rounded in the tax declaration. You can contribute 12x 614.40 = 7372.80 (or even 60x 122.88) and still get a deduction for 7373.
I would go as far as paying in 12x614.38 and thus pay in 7372.56 and get the full deduction. The remaining 0.44 can be invested in ETFs.
I am fascinated by the amount of optimization some people put into their finances.
Instead of ETFs I’d invest in 5 gummy frogs though
Yea, but the 0.44 will count in your wealth tax!
Well I‘ll run the numbers in an Excel sheet tonight and also do some monte carlo simulations. Soon we‘ll know for sure what to do with those 0.44 CHF.