Wow, I appreciate this transparency. Would be very interesting to compare to other neo banks.
1 Like
Neon 3rd pillar is out
Fees are quite competitive.
Your opinions on strategies and etf used ?
2 Likes
How much does a pillar 3a with neon cost?
You’ll pay 0.39–0.45% management fees per year for your pillar 3a, depending on how much money is in your 3a portfolios. The fees are charged quarterly. As soon as you reach your next threshold, the fee will be automatically reduced from the beginning of the next quarter.
- 0 - 4’999 CHF: 0.45%
- 5’000 - 9’999 CHF: 0.44%
- 10’000 - 24’999 CHF: 0.43%
- 25’000 - 49’999 CHF: 0.41%
- 50’000 CHF and more: 0.39%
This management fee includes all account and custody account maintenance costs as well as all investments and sales. Our products are also free of stamp duties (this is something you should definitely bear in mind when comparing 3a products).
We do not charge any direct product costs (TER). Some funds may incur minimal «fund of fund» costs. These costs are not charged to you directly, but are factored into the performance of your strategy. You will actually incur these costs through all 3a providers in Switzerland, but they are often not disclosed transparently. With us, these indirect product costs are only incurred for two strategies:
- neon Offensive 100 strategy: 0.04%
- neon Dynamic 80: 0.07%
1 Like
Do you know if you can do a custom strategy or you have to pick one of the presets?
It looks cheaper than VIAC. I might open an account for next year.
Ok so they match Finpension (0.39%) if you have >50k in the 3a.
Didnt dig deep yet, but Finpension did quite a few things to further optimize fees (including WHT) in the background, so I would be surprised if Neon would be on top of this if you consider all of it (but happy to be disproven).
Overall it seems to be a decent offer. I certainly prefer the flexibility of Viac and finpension, however, for a large number of people, the default strategies may be more important.
The default strategies seem reasonable enough at first glance, a much smaller home bias than Viac and finpension in the global strategies. They don’t seem to provide details on the allocations. E.g., how much of the world stock allocation is hedged (which is a questionable choice). Also an odd decision to hedge the gold allocation but I suspect it might be due to (unreasonable) legal requirements with foreign currency exposure (which shouldn’t really apply to gold).
Does anyone know what exactly they are referring to? It seems a bit odd given that the funds used by Offensive 100 are all also used e.g. in Dynamic 65 and Balanced 45. Why would such product costs apply to one but not the other?
2 Likes
What’s the legal structure behind the product?
2 Likes
The main WHT optimization effort of finpension applies to the non-3a finpension Invest.
For 3a, it’s important to use the pension fund variants of the relevant index funds, which Viac and finpension both do, of course. I was expecting neon 3a to do this correctly but according to their fund list, they actually use the regular fund variant, which has a tax drag of about 0.4% p.a. 
7 Likes
VIAC’s fee is capped at 0.40% (if you only use 0% TER funds). The lowest neon 3a fee is 0.39%. You want to switch because of 0.01% p.a.? And finpension is already at 0.39% and has a much larger list of available funds with high flexibility.
2 Likes
First glance at their 3a offering is not giving me good vides:
- No geographical choice possible => no tax arbitrage
- Giving out rewards to people who transfer 1k until the end of the year => the year is almost over and many people have already contributed (and therefore aren’t eligible to participate)
1 Like
In their blog article 3a comparison 2025: Why neon convinces They provide a table comparing the main providers, and they are transparent that their offer is identical to VIAC and Finpension.
It seems like a good solution for people who don’t want to keep things simple, all within one app.
There are some weird choices (why overweigh EM by 2x?), but all in all, nothing too bad.
I’m very happy with finpension and will continue not changing. Neon was shaky enough in the past. At least with my pension I need some stability.
I wish FP had better (performance) reporting though.
1 Like
Didn’t order a new card and it seems, it was automatically initiated.
But I am surprised in a positive way:
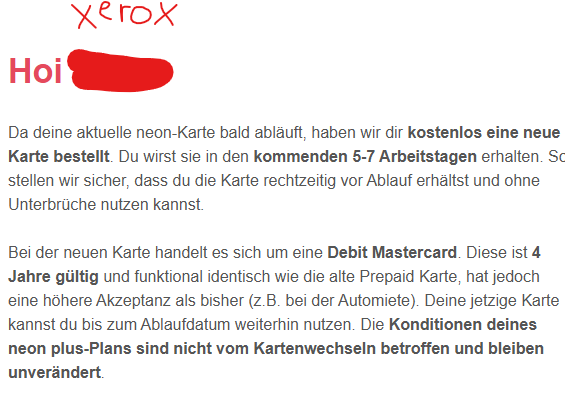
Translation:
Hi xerox,
Since your current neon card is about to expire, we have ordered a new card for you free of charge. You will receive it within the next 5–7 working days. This way we ensure that you get the card in time before it expires and can continue using it without interruption.
The new card is a debit Mastercard. It is valid for 4 years and functionally identical to the old prepaid card, but it has higher acceptance than before (e.g., at gas stations). You can continue to use your current card until its expiration date. The conditions of your neon plus plan are not affected by the card change and remain unchanged.
Unfortunately, it will be a new card with a new number and it could be the case, that I will have trouble with setting it as default payment card with some services (e.g. streaming sites abroad etc.).
This could be an option to check for other alternatives e.g. Revolut. But the probability is high, that I will simply stay with neon since it is a Swiss company.
Apparently, “what pension fundation are you working with?” isn’t a frenquently asked question.
I had to dig a bit:
Your pillar 3a is secure thanks to strong partners
Your money is held with the simply3a pension foundation and managed by the private bank Lienhardt & Partner. It is invested in Swisscanto funds and protected as special assets – so your 3a balance remains secure even in the event of bankruptcy.
Never heard of simply3a, I’ll gladly take whatever info you guys/gals might have on them.
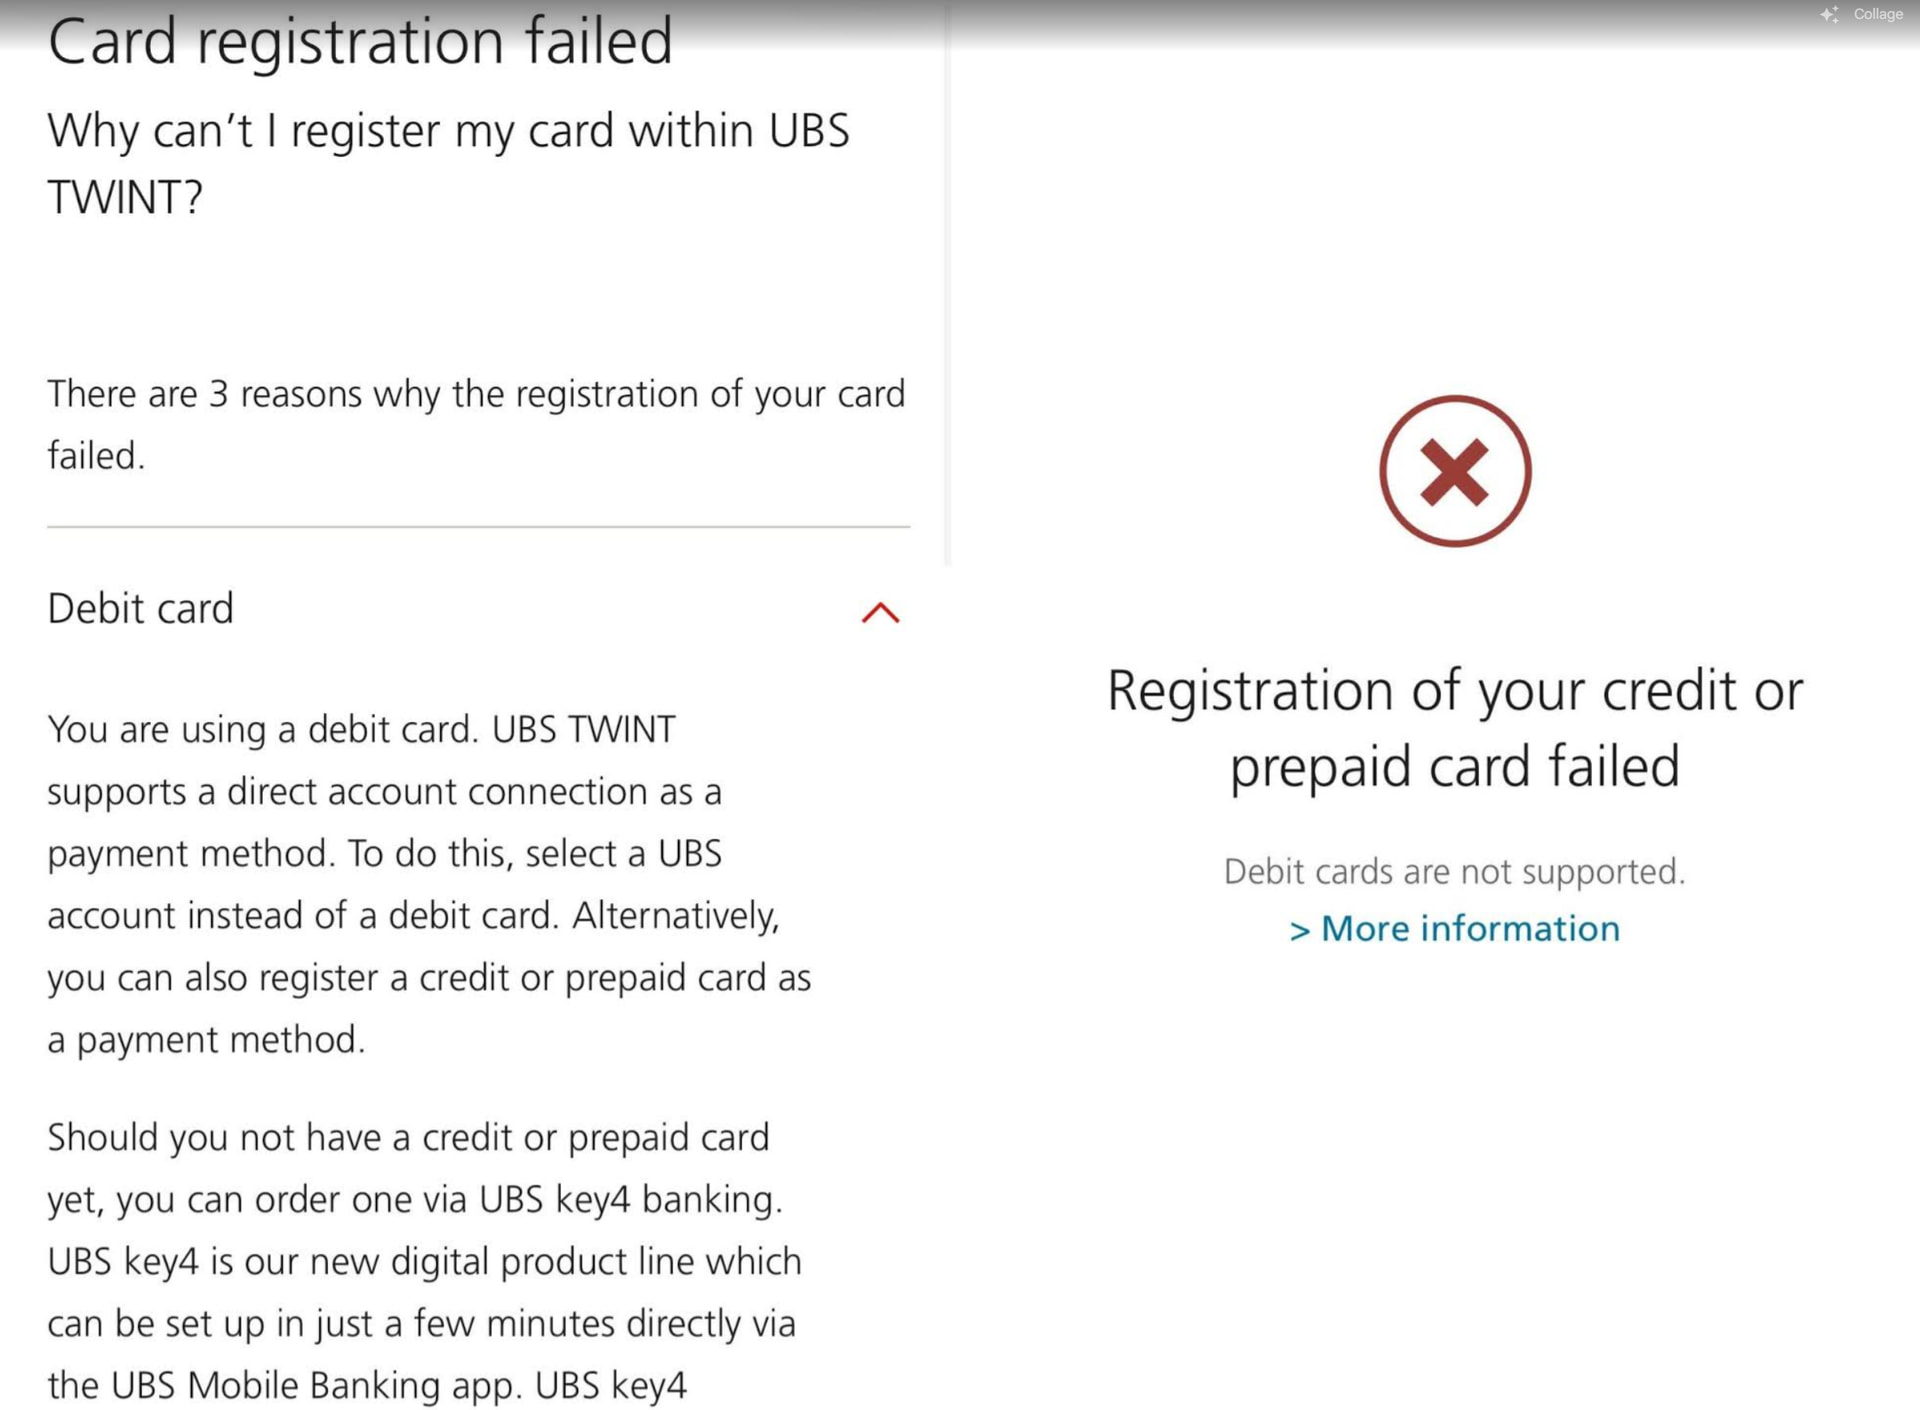
So, no more UBS TWINT from today?? 
Do you have any more context?
3 Likes
TWINT says they don’t take debit or prepaid Mastercard anymore so I can’t register my neon card for them… Am I doing anything wrong?
I don’t want to fall back on TWINT prepaid 
If they changed it, they haven’t updated the website https://www.ubs.com/ch/fr/help/twint/limits.html (still mentions prepaid)