Hi All
I owe someone about 93 EUR. Since I have no EUR at hand, I will pay with my CHF accounts.
when I entered a SEPA transaction in Postfinance, it showed 88.69 CHF total.
For fun I went to my NEON account, where the same 93 CHF would cost me 89.41 CHF, more than with PF. Did I miss something?^^
I just got an email from Neon. They offer Gold and Silver ETF with the usual 0% fee until end of year. Both belong to Swisscanto. Gold CH0139101593 Silver CH0183135976
That Swisscanto Gold ETF has a 0.40% TER. The UBS Gold ETF has a 0.23% TER (and there are cheaper Gold ETFs outside Switzerland). I wouldn’t recommend that if you intend to hold it for many years.
(For silver the difference is similar with a 0.60% vs. 0.45% TER).
I will take a look at this. Unfortunately, these Swiss ETFs are less liquid and have wider spreads than GLD (GLD 0.003%, AUUSIUSD - 0.1-0.5%) and GLDM.
I know there is no buy/sell offer with this one on Neon, but a cheaper TER for long term is better right?
Invesco Physical Gold - 0.12% - IE00B579F325.
I think UBS & ZKB ETFs offer possibility to convert to bullion. Rest of the ETFs are mostly paper trading. Maybe that explains the spread and liquidity.
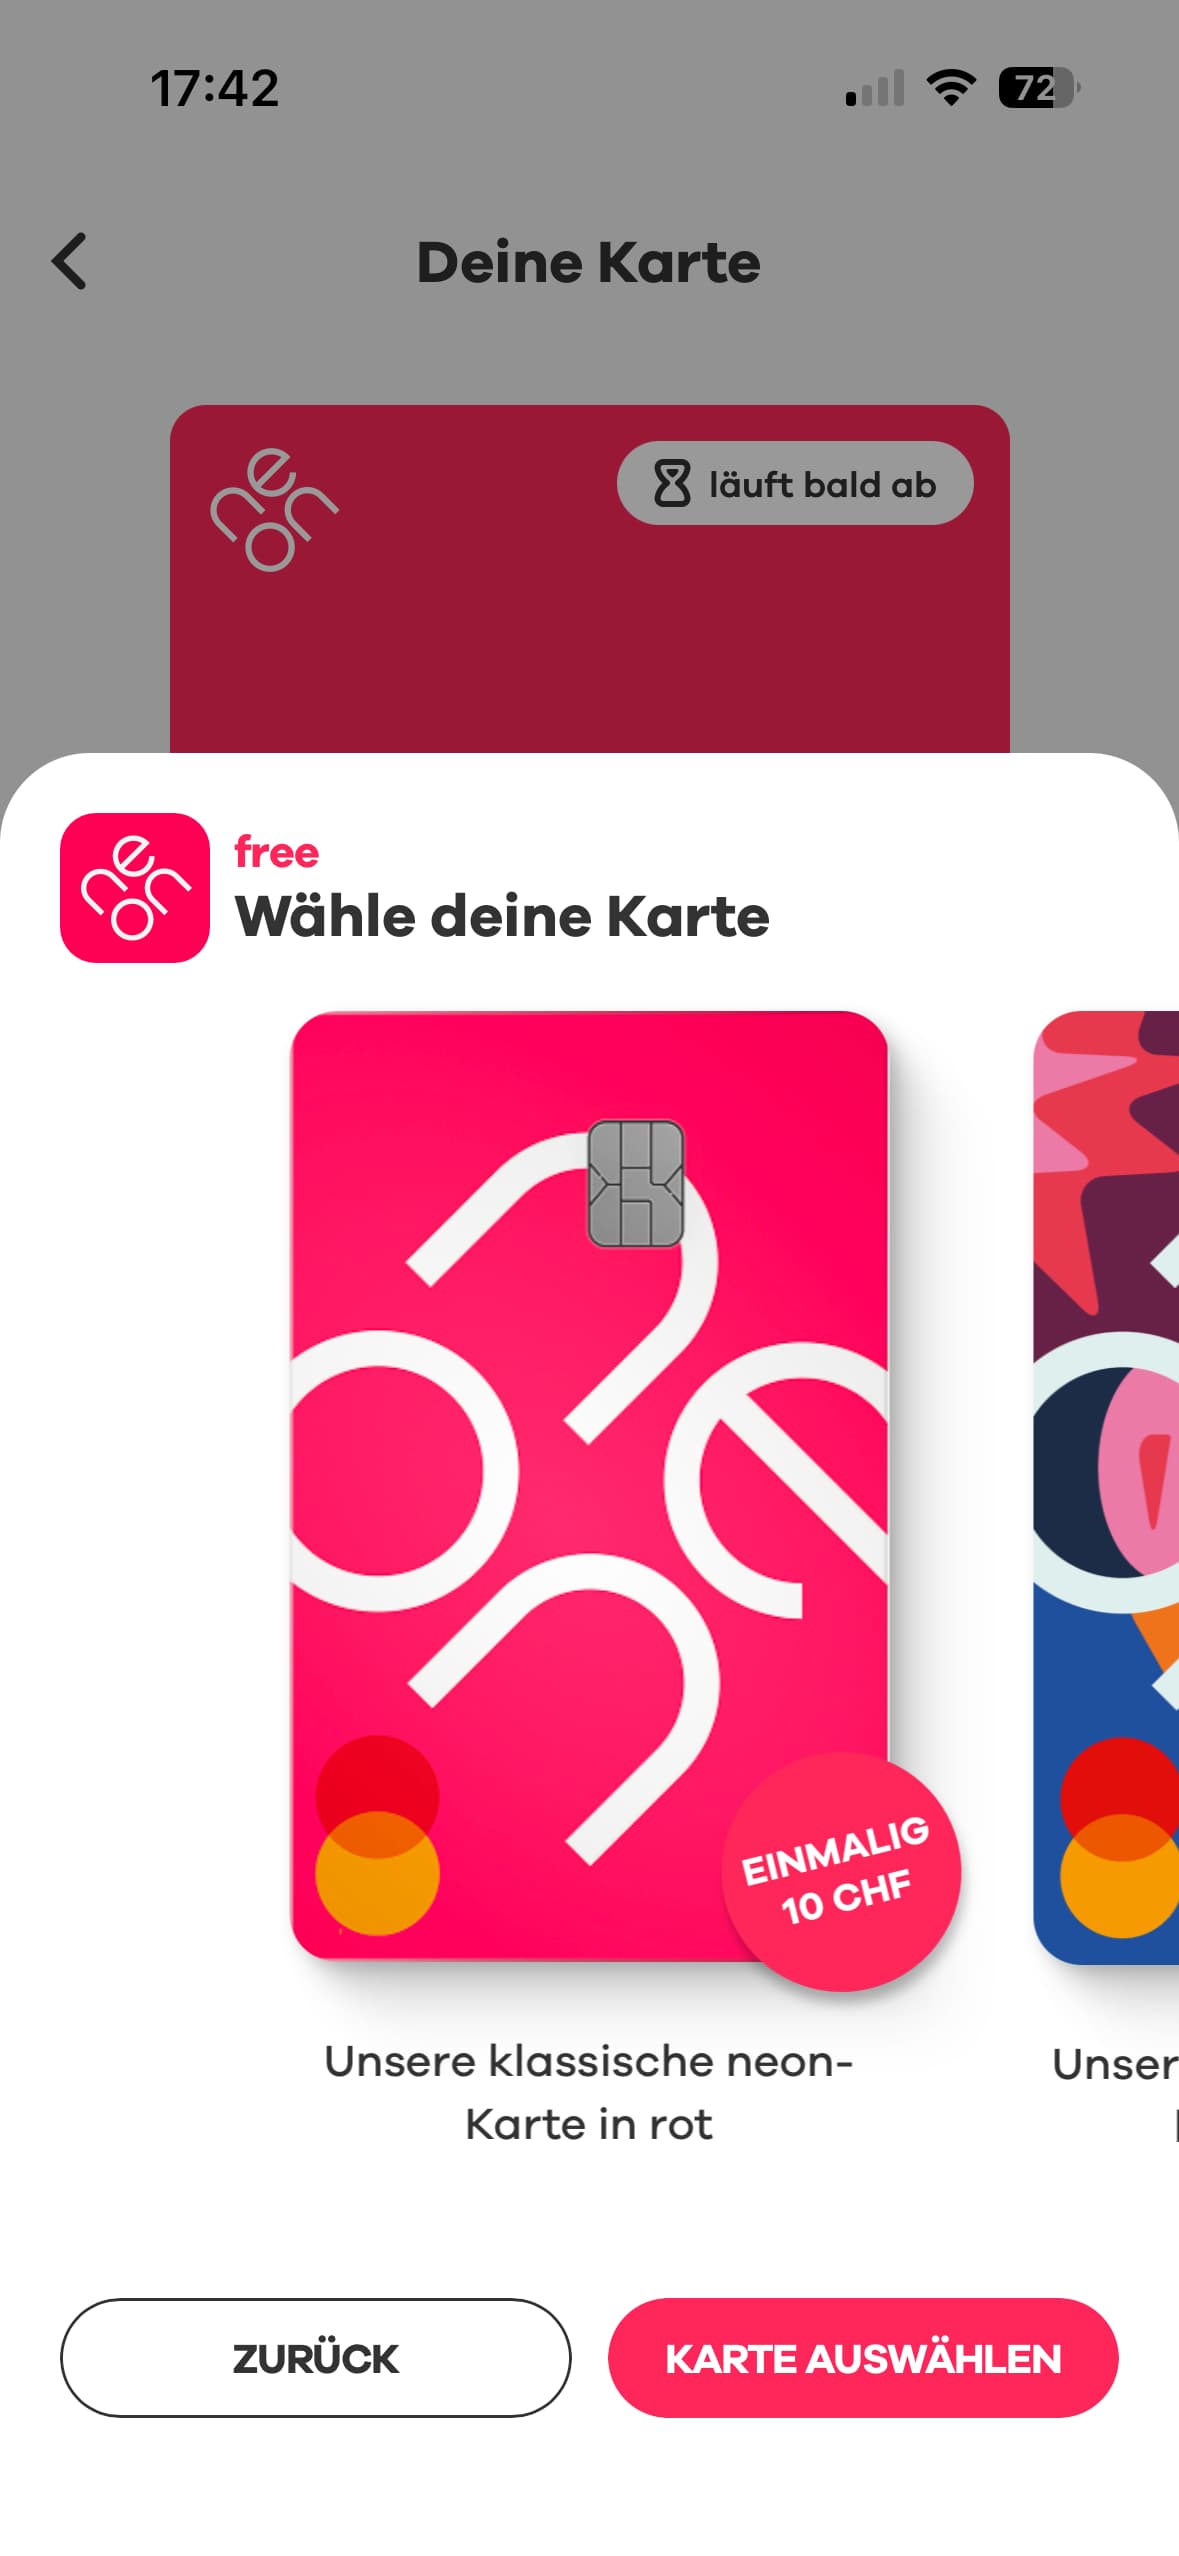
That’s my understanding. My card is about to expire, I was a bit puzzled about this fee at first but didn’t hesitate for long. It’s still an excellent package for me.
In theory, you can change plans monthly and in some plans the replacement card will be free.
So the thought did cross my mind that maybe it’s cheaper to switch plans for a month just for the free replacement card
But I couldn’t find out anywhere whether you could keep the higher-plan card when downgrading, so just coughing up 10 CHF seemed like the safest option to me.
I only use Neon with Apple Pay. I’m curious to see if Apple Pay will continue to work after the card expires. As far as I know, however, this is linked, as Neon does not support virtual cards.
Never had a card that I had to pay for when it expired. Bothers me, not so much 10.- every few years, but that they still have their website as neon-free and not even this is free.
Sorry to crash the party, but try out Yuh-Free.
Ah wait, there is no Yuh-Free as all packages of Yuh are free*. *Yes, I know, forex at Yuh is worse than Neon, but for the basic bank account + card, I only see advantages. I was on the brink between Neon & Yuh a while back before opening an account, but since then the balance tipped more and more towards Yuh.
Multi-currency on same IBAN at Yuh is great and practical as well, especially since you can spend them from the debit card (à la Revolut). Use IBKR for fx once in a while if you want to optimize fees.
As a free package, debit card, twint, bill, Apple Pay, multi currency, it’s great.
Invest, saving plans & 3a are worth a look if you want to shrink everything down in terms of providers. It’s a free mobile-only swissquote for dummies.
Also, it is great to have a low cost low fee for fx, but if you are planning your fx operations in advance, you may as well gain/lose from market timing. Especially nowadays when currency vol is pretty high.
And if you spend once in a while some small amounts abroad directly from chf account and want the least overhead possible when fx occurs, it’s not like a few bips will be the end of the world.
Then there’s the case where there are huge amounts and you don’t want to/can’t plan and just want to save on fees when it occurs.
Mit dem Lesen und der Teilnahme an diesem Forum bestätigst du, dass du die Forum-Richtlinien gelesen hast und damit einverstanden bist sowie den Haftungsausschluss auf http://www.mustachianpost.com/de/ akzeptierst.