# Lombard loan, is it worth it?
**URL:** https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557
**Category:** Investing / Others
**Created:** [October 14, 2020, 7:59am UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557 "2020-10-14T07:59:06Z")
**Posts on this page:** 20
**Page:** 2
### Author:  [@jay](https://forum.mustachianpost.com/u/jay)
#### Post date: [January 8, 2023, 12:01pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/21 "2023-01-08T12:01:27Z")
I’m not commenting on the investment risk of this.
> [@Idonthaveamustache](#):
>
> Are there any Tax benefits? For example if you have a loan for real estate, you get tax benefits.
You can deduct margin interest from your taxable income. I’d suggest making sure that your dividend income remains higher than your margin interest to reduce the risk of being classified as professional trader.
However, depending on your tax rate, your DA-1 tax credit may get reduced due to the margin interest deduction. I.e. if your effective tax rate for income from your wealth is below 15% due to deductions, you won’t get a tax credit for the full 15% US WHT (as the basis is a double taxation agreement).
---
### Author:  [@kane](https://forum.mustachianpost.com/u/kane)
#### Post date: [January 8, 2023, 6:58pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/22 "2023-01-08T18:58:45Z")
As the fed and other central banks have raised interest, most lombard loans increased the rates so it’s very expensive. I ran a 10-15% LTV loan on my IBKR portfolio, however their USD rate is was raised to 5.83% right now, so this is super expensive. I didn’t realize and it cost me quit a bit of fees.
---
### Author:  [@Barto](https://forum.mustachianpost.com/u/Barto)
#### Post date: [January 8, 2023, 7:37pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/23 "2023-01-08T19:37:35Z")
Low rates for the past 10 years heavily stacked the odds in favour of leveraged investing in stocks. It is no longer the case in my view
---
### Author:  [@MrCheese](https://forum.mustachianpost.com/u/MrCheese)
#### Post date: [January 18, 2023, 2:01pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/24 "2023-01-18T14:01:56Z")
Woah good point, looks like I’ve took out some EUR loan at almost 4%, CHF loans are fortunately still at 1.5%
EDIT: easily enough you can then just close the negative position with CHF, so my EUR loan is now a CHF loan instead 😃
---
### Author:  [@jay](https://forum.mustachianpost.com/u/jay)
#### Post date: [January 18, 2023, 2:28pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/25 "2023-01-18T14:28:20Z")
> [@MrCheese](#):
>
> CHF loans are fortunately still at 1.5%
The CHF margin interest rate at IBKR is also no longer 1.5. It’s 2.38% for the first 90k. See [Margin Rates and Financing | Interactive Brokers LLC](https://www.interactivebrokers.com/en/index.php?f=46376&p=m)
---
### Author:  [@MrCheese](https://forum.mustachianpost.com/u/MrCheese)
#### Post date: [January 18, 2023, 2:42pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/26 "2023-01-18T14:42:12Z")
Ah right, the calculator showed me 1.5% for IBKR Pro for some reason
---
### Author:  [@prodent](https://forum.mustachianpost.com/u/prodent)
#### Post date: [January 18, 2023, 2:57pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/27 "2023-01-18T14:57:48Z")
My personal take on IBKR lombard loans:
I used one last year to pay for cooperative shares (I had to cough up a 5-figure amount on relatively short notice) and spent the following months paying it off.
I’d use it again in a heartbeat (e.g. if I suddenly needed to purchase a car) and feel more confident keeping a fairly low emergency fund. I also played with the idea of keeping a few % margin but found that it simply isn’t for me.
---
### Author:  [@Barto](https://forum.mustachianpost.com/u/Barto)
#### Post date: [January 18, 2023, 5:47pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/28 "2023-01-18T17:47:35Z")
I believe the theory says to match the currency of the loan to assets and income, to minimise risk
The market expects that on average FX rates will move to off-set any savings you can make on interest rates. Otherwise there would be an arbitrage opportunity
---
### Author:  [@dom.swiss](https://forum.mustachianpost.com/u/dom.swiss)
#### Post date: [February 8, 2025, 7:11pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/29 "2025-02-08T19:11:06Z")
There has recently been some interest in leveraged investments in the Zurich meetup, so I calculated some numbers for Lombard loans. This is a loan you get and your securities are the collateral. Banks rate your securities with a LTV (loan-to-value) ratio and it can be anything from 10% (for penny stocks) to 90% (for AAA bonds).
I do not want to go into the risk of going into debt, just want to show you how it works.
Let’s say I have CHF 100k and buy 5 dividend stocks. At current market valuations, I might get CHF 3915 of dividends. I now activate the lombard loan facility and can get an additional CHF 70k which I again invest in the same stocks. Doing this iteratively, after 12 loan levels I have an additional 230k of investments, creating CHF 9008 of additional dividends.
Of course, the bank charges me for the lombard loan, let’s assume 2%. I now have 3.91% - 2% = 1.91% of dividend returns on 3.3x of my original capital, yielding 8.32%. The less you pay for the loan, the better is your return. It is a great tool for markets going sideways or up.
| | invested | market price | dividend | dividend return | return | | LTV | loan level 1 | loan level 2 | loan level 3 |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| NOVN | 20,000 | 96.83 | 3.48 | 3.59% | 719 | SMI top-3 | 70% | 14000 | 9800 | 6860 |
| ROGGS | 20,000 | 289 | 9.72 | 3.36% | 673 | SMI top-3 | 70% | 14000 | 9800 | 6860 |
| NESN | 20,000 | 77.5 | 3 | 3.87% | 774 | SMI top-3 | 70% | 14000 | 9800 | 6860 |
| SREN | 20,000 | 141.65 | 6.2 | 4.38% | 875 | dividend stock | 70% | 14000 | 9800 | 6860 |
| SLHN | 20,000 | 755.4 | 33 | 4.37% | 874 | dividend stock | 70% | 14000 | 9800 | 6860 |
| | | | | | | | | | | |
| own assets / equity | 100,000 | | | 3.91% | 3,915 | Return | | 70000 | 49000 | 34300 |
| Lombard loans | 230,104 | Threshold amount at LTV and 12 iterations | 70% | 3.91% | 9,008 | |
| --- | --- | --- | --- | --- | --- | --- |
| Cost of loan | | | | 2% | -4,602 | Large banks btw. 0.5 and 1.5%, discount brokers 2-4% |
| | | | | 1.91% | 4,406 | additional returns |
| | 330,104 | | | | 8,321 | Total Dividend Return |
| | | | | | 8.32% | Return on Equity (without any capital gains) |
---
### Author:  [@1742](https://forum.mustachianpost.com/u/1742)
#### Post date: [February 8, 2025, 8:27pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/30 "2025-02-08T20:27:35Z")
> [@dom.swiss](#):
>
> It is a great tool for markets going sideways or up.
…and a 100% loss of your capital if the market drops 30% 😁
My point is: No one should need a leverage investment strategy explanation. If you aren’t able to figure out how it works yourself, you shouldn’t use it.
---
### Author:  [@Wachwitz](https://forum.mustachianpost.com/u/Wachwitz)
#### Post date: [February 8, 2025, 8:29pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/31 "2025-02-08T20:29:58Z")
So you have 330’000 worth of equity and a loan of 230’000 (your 100’000 is leveraged by 3.3).
Say, against expectations, the value of the equities drops 30.5%, approaching the value of the loan. That’s when your entire position gets liquidated and you end up with an empty account, right?
If it doesn’t drop 30.5%, but just 15%, you’re forced to sell 33’650 worth of equities to re-establish the 0.7 LTV, at an inopportune time: you bought high, you’re selling low.
Whereas without leverage, you can simply ignore all noise and keep on holding 😉
---
### Author:  [@anon17469660](https://forum.mustachianpost.com/u/anon17469660)
#### Post date: [February 8, 2025, 8:44pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/32 "2025-02-08T20:44:18Z")
> [@dom.swiss](#):
>
> the bank charges me for the lombard loan, let’s assume 2%.
These are SQ’s current terms:
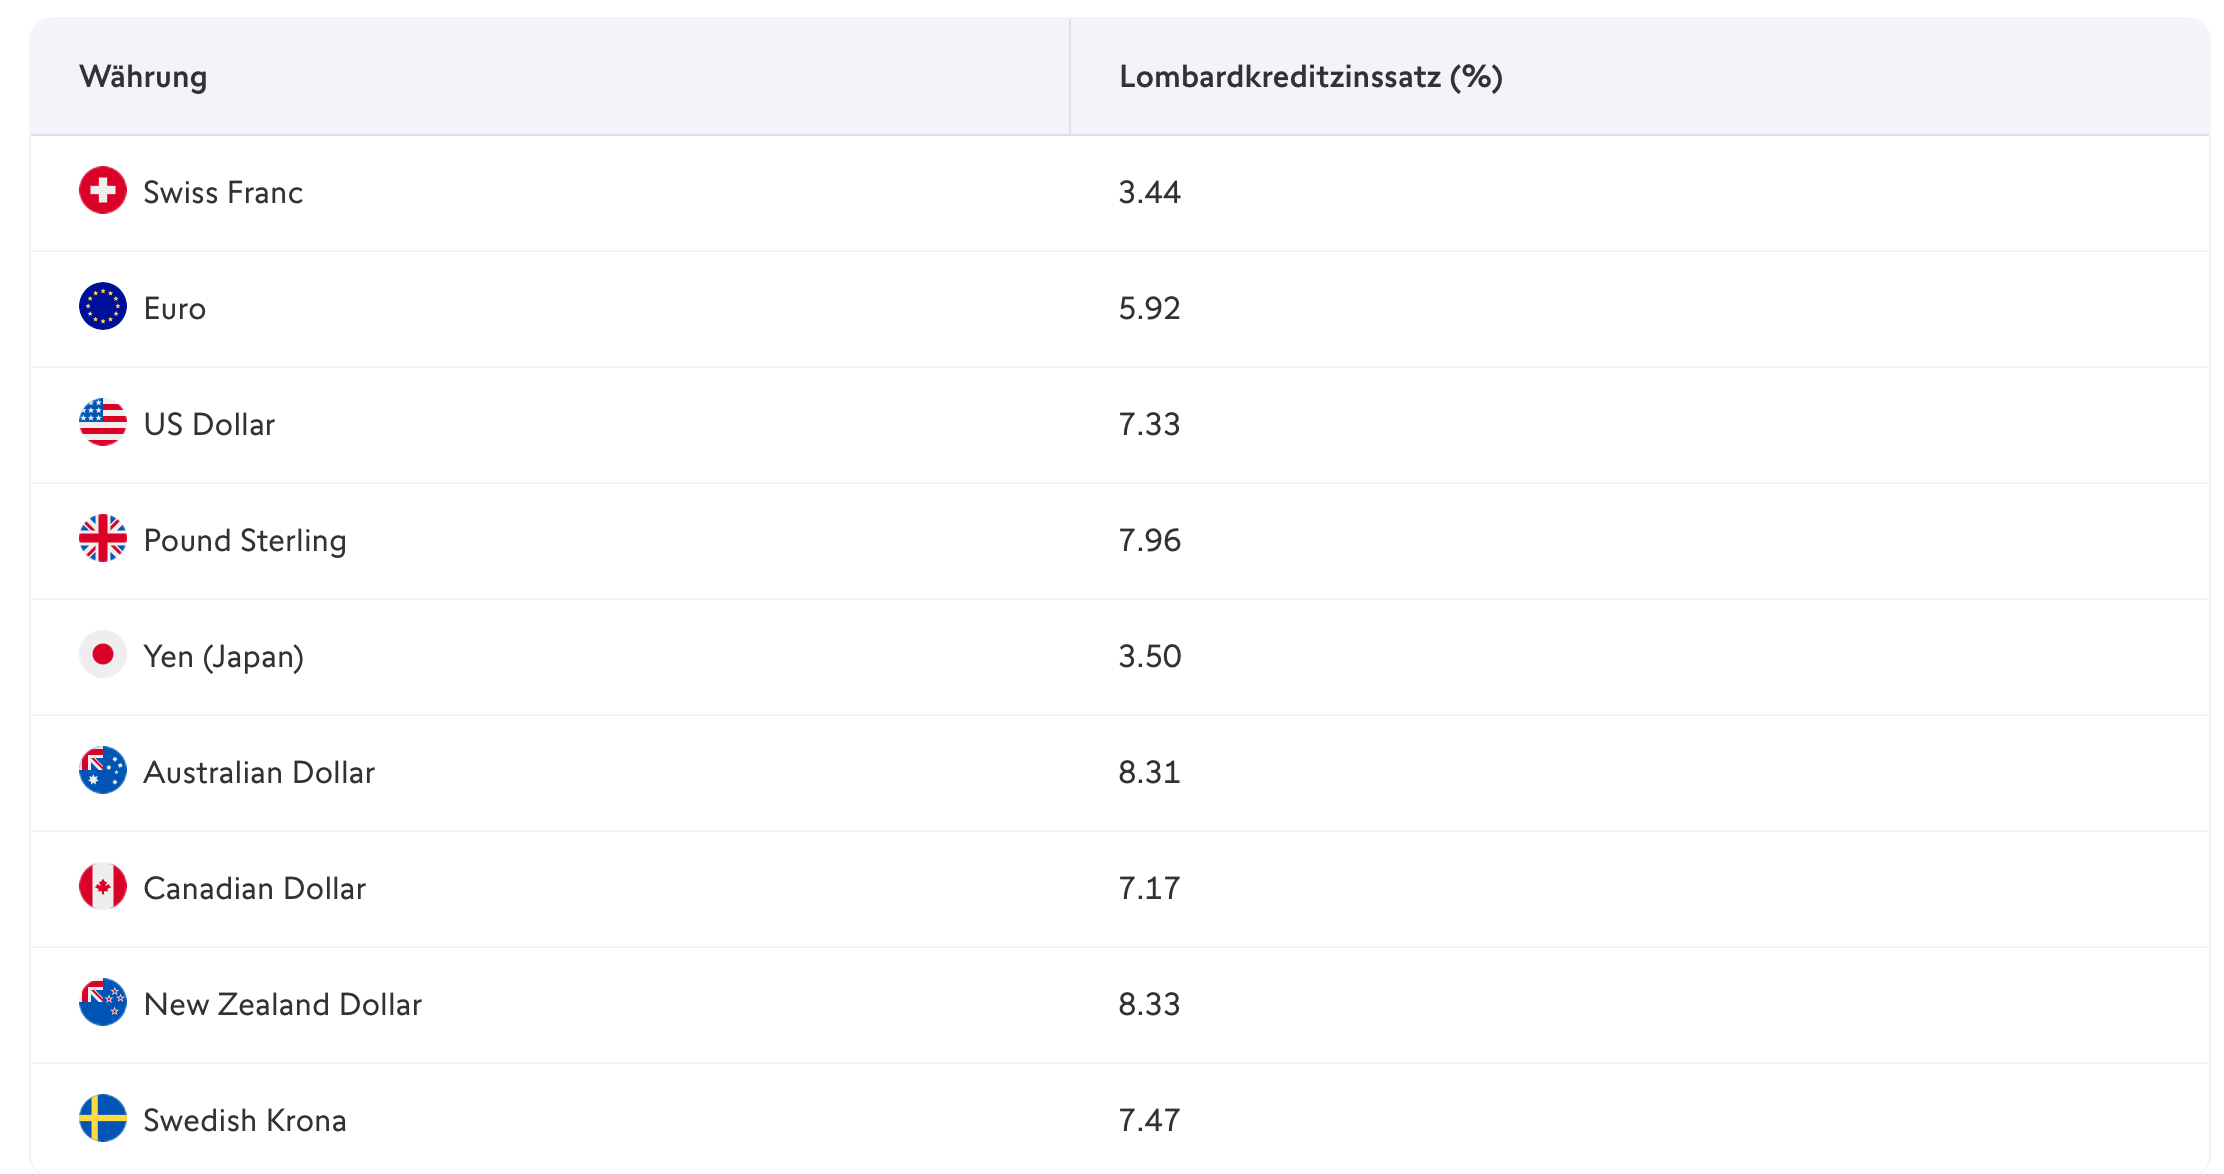
([Source](https://www.swissquote.com/de-ch/private/trade/products/securities/lombard-loan))
---
### Author:  [@oswand](https://forum.mustachianpost.com/u/oswand)
#### Post date: [February 8, 2025, 8:58pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/33 "2025-02-08T20:58:30Z")
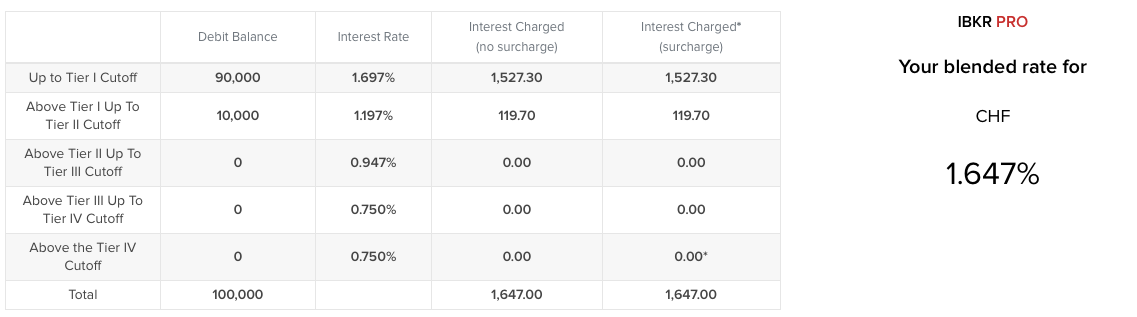
IBRK Pro
---
### Author:  [@dom.swiss](https://forum.mustachianpost.com/u/dom.swiss)
#### Post date: [February 8, 2025, 9:28pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/34 "2025-02-08T21:28:16Z")
> [@1742](#):
>
> No one should need a leverage investment strategy explanation
Private Banking clients are interested.
> [@Wachwitz](#):
>
> Say, against expectations, the value of the equities drops 30.5%, approaching the value of the loan. That’s when your entire position gets liquidated and you end up with an empty account, right?
Exactly, that’s why I would not consider it from a) my age 59 and b) my wealth.
> [@anon17469660](#):
>
> These are SQ’s current terms:
> [@oswand](#):
>
> IBRK Pro
Interesting to know, thanks!
---
### Author:  [@Wachwitz](https://forum.mustachianpost.com/u/Wachwitz)
#### Post date: [February 8, 2025, 9:38pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/35 "2025-02-08T21:38:35Z")
Anyone considering leverage in investing should listen to five minutes starting 15:52 of [Warren Buffet’s speech at Florida University](https://www.youtube.com/watch?v=2MHIcabnjrA&t=950s) about the downfall of [LTCM](https://en.wikipedia.org/wiki/Long-Term_Capital_Management). One of the people he mentions is Victor Haghani, who since wrote [The Missing Billionaires](https://annas-archive.org/md5/9ef6c7ee9670f58ed050affb3ff58135).
It’s a great read about how you should calculate bet sizing in games, or how much of your net worth you should put in risky assets. Putting in more than 100% is leverage. There are situations where that is the right move. ‘Expected Lifetime Utility’ is an interesting concept. If you then still want to strictly maximize expected return, be a full [Kelly](https://en.wikipedia.org/wiki/Kelly_criterion) bettor.
---
### Author:  [@cubanpete\_the\_swiss](https://forum.mustachianpost.com/u/cubanpete_the_swiss)
#### Post date: [February 9, 2025, 7:24am UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/36 "2025-02-09T07:24:46Z")
I do use leverage in one of my strategies when in “crash recovery mode” and in another strategy I use it constantly with a different multiplier depending on the state of the market. IBKR has the cheapest interest rates as mentioned.
My strategies are mechanical and checking the margin in real time is part of it. It is quiet easy done in a spreadsheet. Details I did describe in my “mechanical investment” thread:
> [@Mechanical investment strategies](https://forum.mustachianpost.com/t/mechanical-investment-strategies/15184/1):
>
> I could not find a thread on mechanical investments, so I start this one. Here is a simple definition: [Mechanical investing - Investment strategies - Moneyterms: investment, finance and business explained](https://moneyterms.co.uk/mechanical-investing/#:~:text=A%20mechanical%20investment%20strategy%20is,judgement%2C%20making%20them%20less%20subjective). The book [https://www.google.ch/books/edition/What\_Works\_on\_Wall\_Street](https://www.google.ch/books/edition/What_Works_on_Wall_Street) gives some ideas and testing results. However, they vary from edition to edition and may be kind of biased. Most people here invest in ETF and that is OK. There are ETF that use mechanical investment strategies, some ind…
A word of warning: without leverage you have a “stress tolerance” of 100%. That is how much your equities can fall in price. When using leverage you have to define an emergency exit where to sell and this must be way before your broker starts selling or issues a margin call.
At this point you are obliged to sell at the worst possible moment: when stocks are down!
---
### Author:  [@cubanpete\_the\_swiss](https://forum.mustachianpost.com/u/cubanpete_the_swiss)
#### Post date: [February 9, 2025, 8:02am UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/37 "2025-02-09T08:02:14Z")
> [@cubanpete\_the\_swiss](#):
>
> At this point you are obliged to sell at the worst possible moment: when stocks are down!
A remark to leveraged ETF, they seem to be quiet en vogue at the moment, which is normal after such a long bull market.
Those ETF must sell whenever the underlying stock goes down and must buy whenever it goes up. They usually do this once a day to maintain a constant leverage. This is a suboptimal strategy; instead of buying a leveraged ETF one could implement a better strategy with margin.
Volatility kills the performance of leveraged ETF as they buy high and sell low. And markets have become much more volatile in my opinion.
---
### Author:  [@ternes11](https://forum.mustachianpost.com/u/ternes11)
#### Post date: [February 9, 2025, 9:48am UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/38 "2025-02-09T09:48:10Z")
I have always wondered if some conservative use of leverage might be beneficial for my portfolio. Conservative margin in the range of 20-30% of one’s invested capital (100% stock). So margin part of the portfolio would be covered 3-5x by the unlevered portfolio. Margin loan would be invested the same way as the unlevered portfolio.
I often hear about the alleged great performance of Private Equity. In my view most of their performance comes from financial engineering and multiple expansion, less from the often promised operational improvements. In this case, financial engineering is simply the use of debt (leverage) to acquire businesses. As they don’t report the values mark to market and conveniently value their companies themselves, risk is reduced.
---
### Author:  [@oswand](https://forum.mustachianpost.com/u/oswand)
#### Post date: [February 9, 2025, 5:43pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/39 "2025-02-09T17:43:58Z")
> [@ternes11](#):
>
> As they don’t report the values mark to market and conveniently value their companies themselves, risk is reduced.
It doesn’t matter what you value your asset, it’s upon the person that lends you the funds.
---
### Author:  [@Wachwitz](https://forum.mustachianpost.com/u/Wachwitz)
#### Post date: [February 10, 2025, 7:17pm UTC](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557/41 "2025-02-10T19:17:43Z")
Makes no sense to me. How would it reduce wealth tax or income tax? It would only increase leverage.
[Previous page](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557.md?page=1)
[Next page](https://forum.mustachianpost.com/t/lombard-loan-is-it-worth-it/4557.md?page=3)