# Buying a property - Some questions
**URL:** https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397
**Category:** Real Estate
**Created:** [January 31, 2025, 8:20pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397 "2025-01-31T20:20:15Z")
**Posts on this page:** 20
**Page:** 2
### Author:  [@cubanpete\_the\_swiss](https://forum.mustachianpost.com/u/cubanpete_the_swiss)
#### Post date: [February 3, 2025, 5:08pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/21 "2025-02-03T17:08:41Z")
Financial institution, mainly pension funds, are one reason for the bubble. But not the only one. I would say immigration, land scarcity (mainly artificial due to some votings) and the good financial general state of Switzerland are the others.
Could not find the total value of all Swiss real estate, but found the average person occupies 45m2, the price per m2 is CHF 8’200 average and we are probably around 9 million people living here. That is 45_8200_9, more or less 3.3 trillion. 2nd pillar in 2022 was 1.066 trillion, grows 8% per year so lets say it is now around 1.25 trillion. I suppose it will start to shrink sometimes in the future. And not everything is invested in Swiss real estate, let’s say 1 trillion. So it is about 30% of all Swiss real estate. That is quiet a lot!
There is a tendency to limit immigration and the birth rate is sinking. So that factor could cool down too.
Now, inflation and general problems in the financial industry and tariffs could hurt the good financial general state of Switzerland. We have not much industry left and almost always are the most expensive place to produce anything.
We still have enough building land but it is limited due to various votings. I don’t think politicians will touch that, so land scarcity will stay an important factor to support the sky high prices.
But only one or two of the four factors (pension funds, immigration, general good financial state and land scarcity) have to change to make the bubble pop. And then it will happen very fast, as the private debt is sky high.
P.S. to the pension fund investments one probably has to add debt, so it may be more. At 50% mortgage it would be 60%. That is scary…
---
### Author:  [@cubanpete\_the\_swiss](https://forum.mustachianpost.com/u/cubanpete_the_swiss)
#### Post date: [February 3, 2025, 5:15pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/22 "2025-02-03T17:15:07Z")
Hmm, difficult question. We are definitively in a boom, 40 years of rising prices. The last part of a boom I would call the bubble, everything speeds up. No idea if we are there already.
I think you can say we are in a real estate boom. The bubble will not be in sight after it pops. And the chances for it to pop are highest when nobody says that we are in a bubble…
---
### Author:  [@OogieBoogie](https://forum.mustachianpost.com/u/OogieBoogie)
#### Post date: [February 3, 2025, 5:32pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/23 "2025-02-03T17:32:13Z")
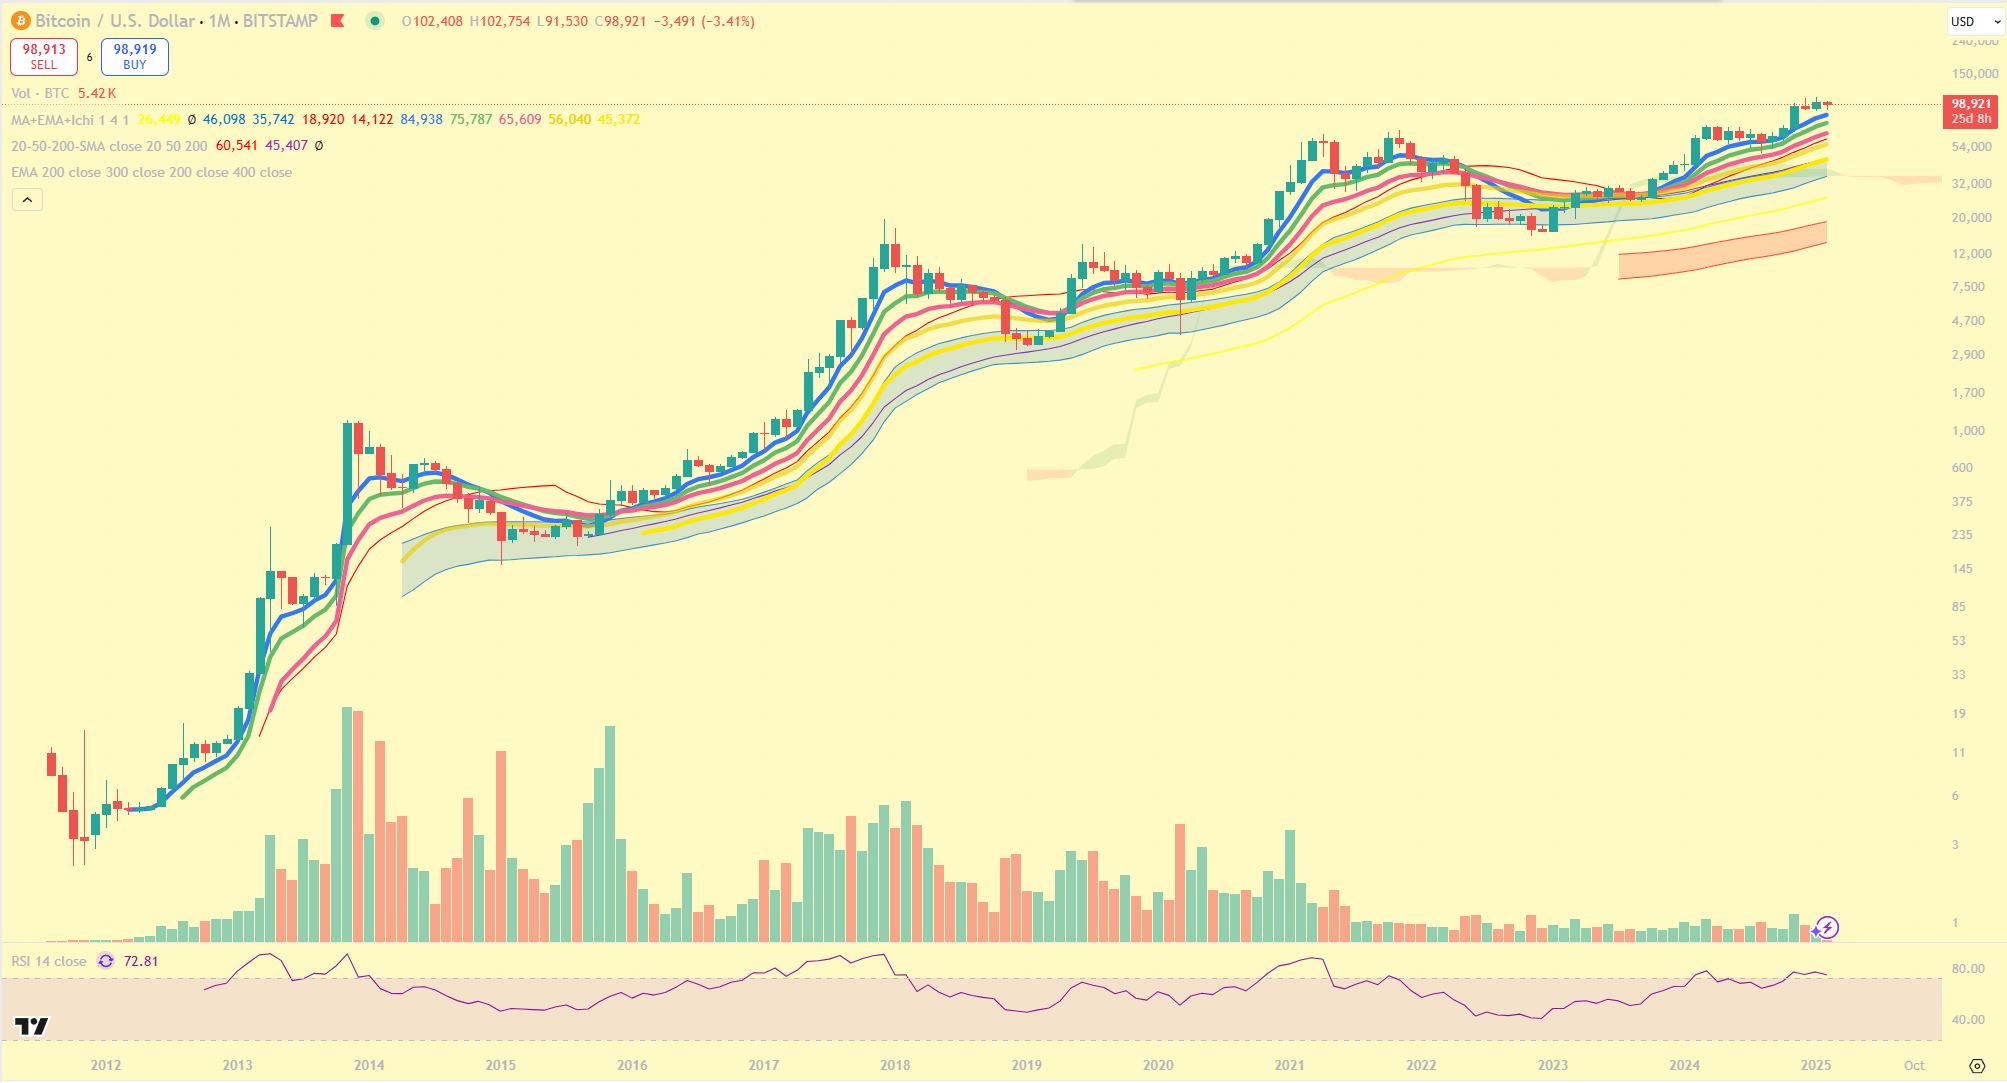
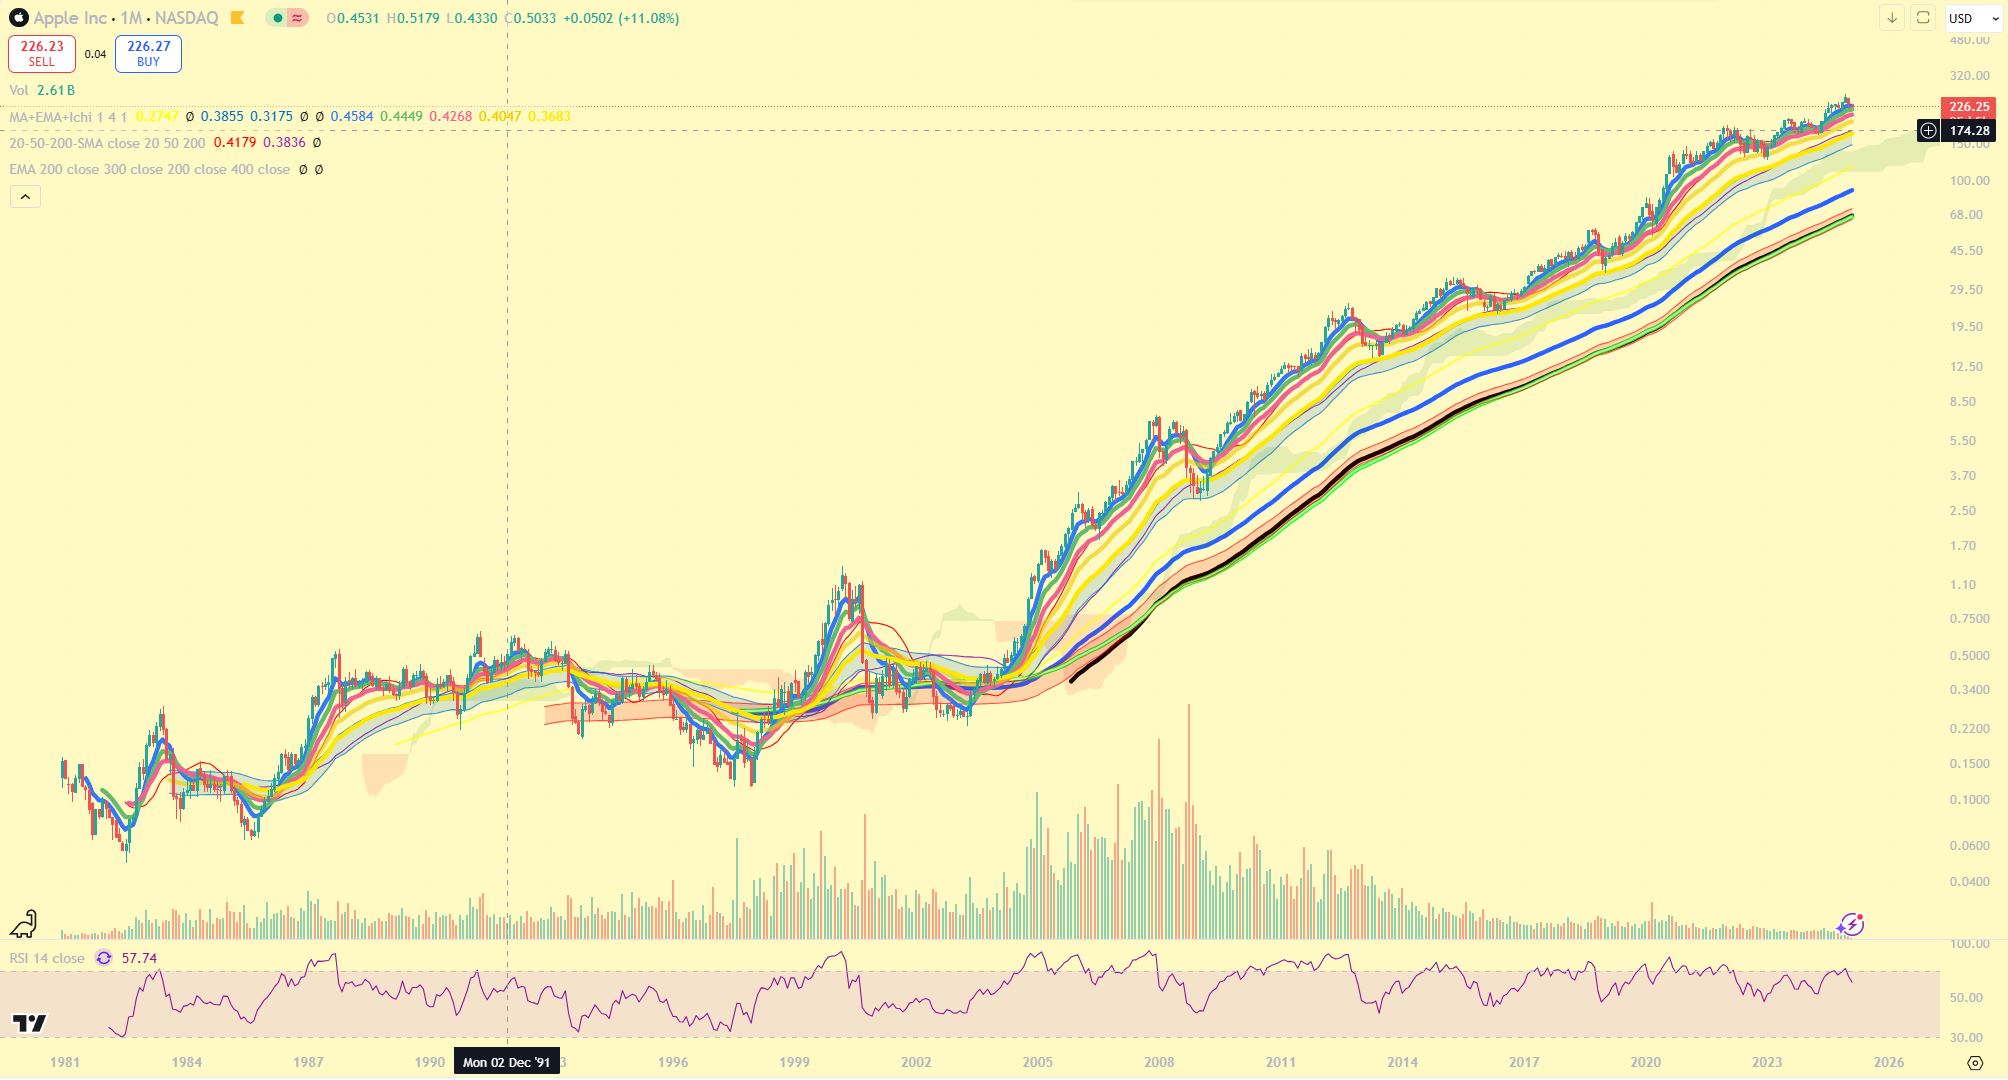
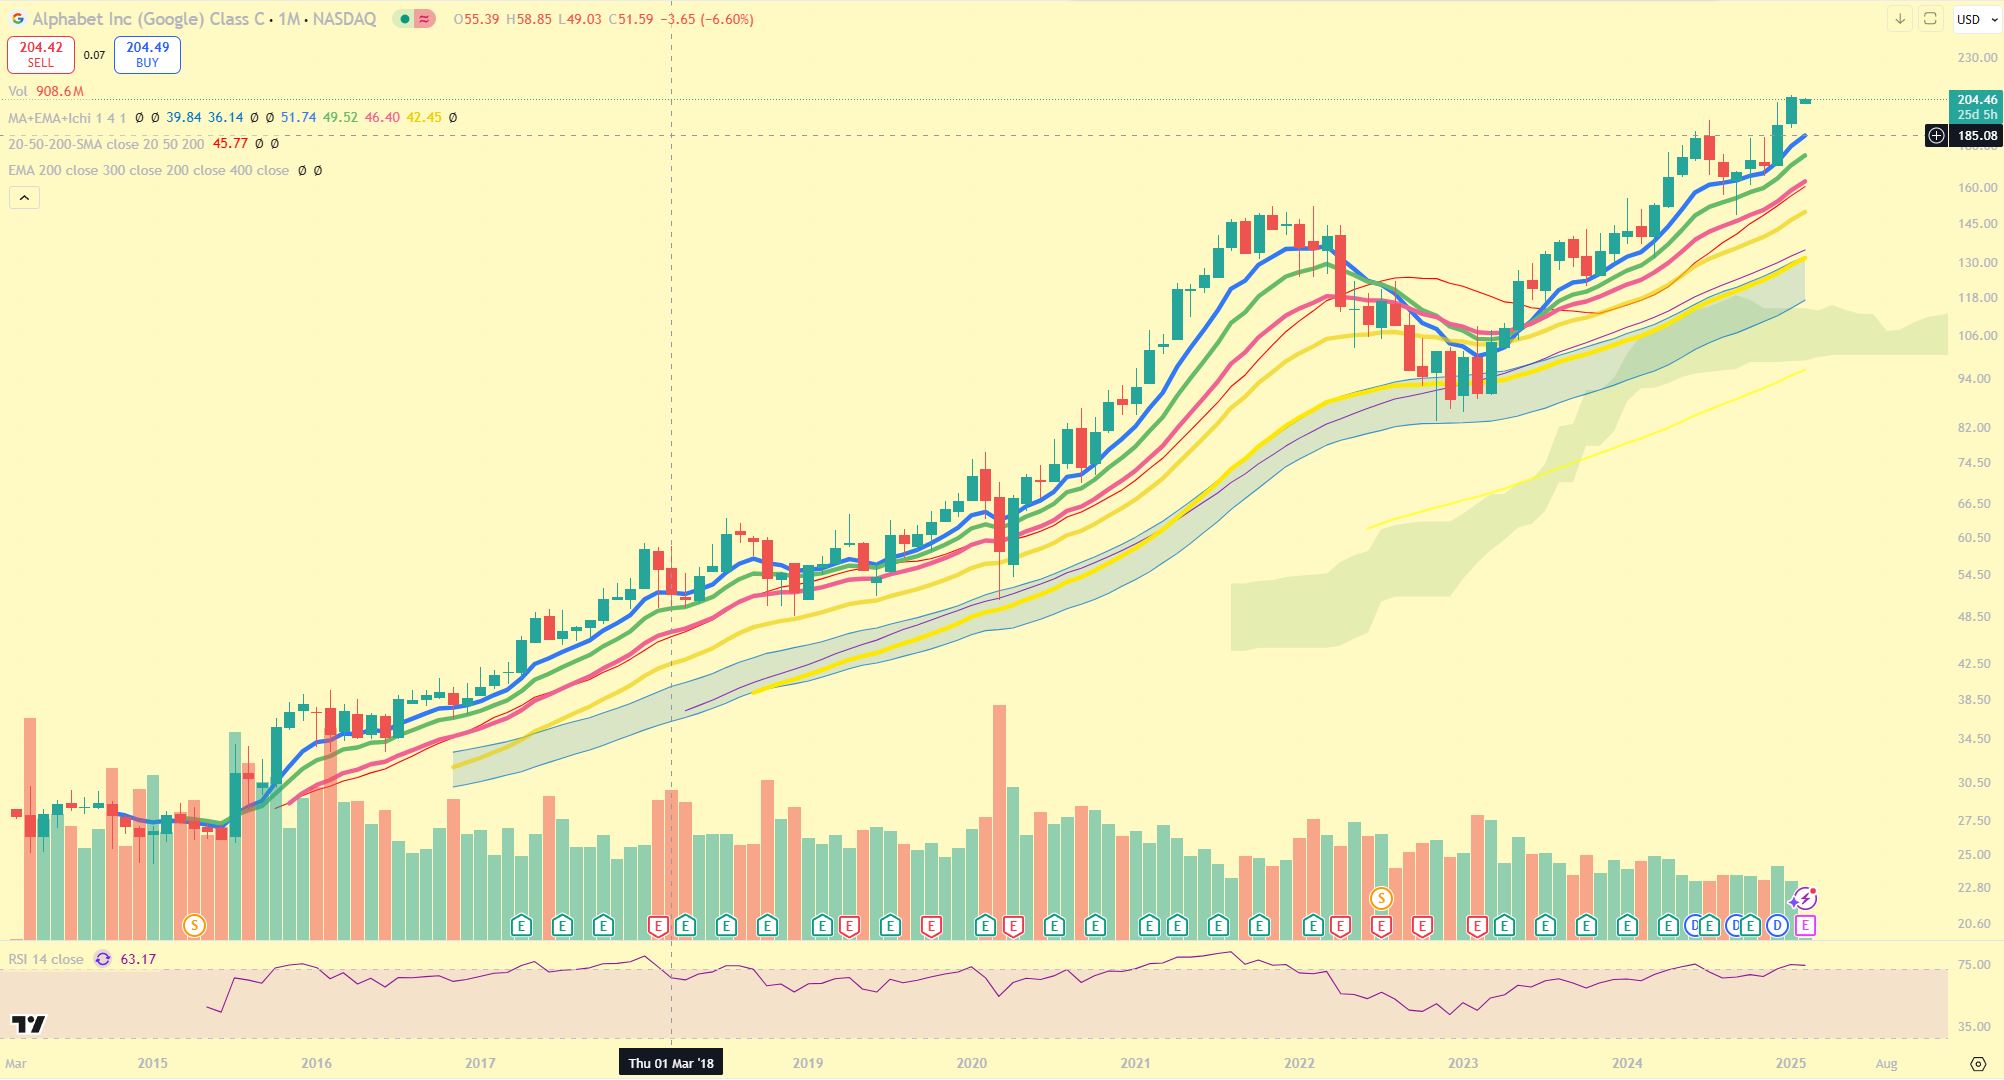
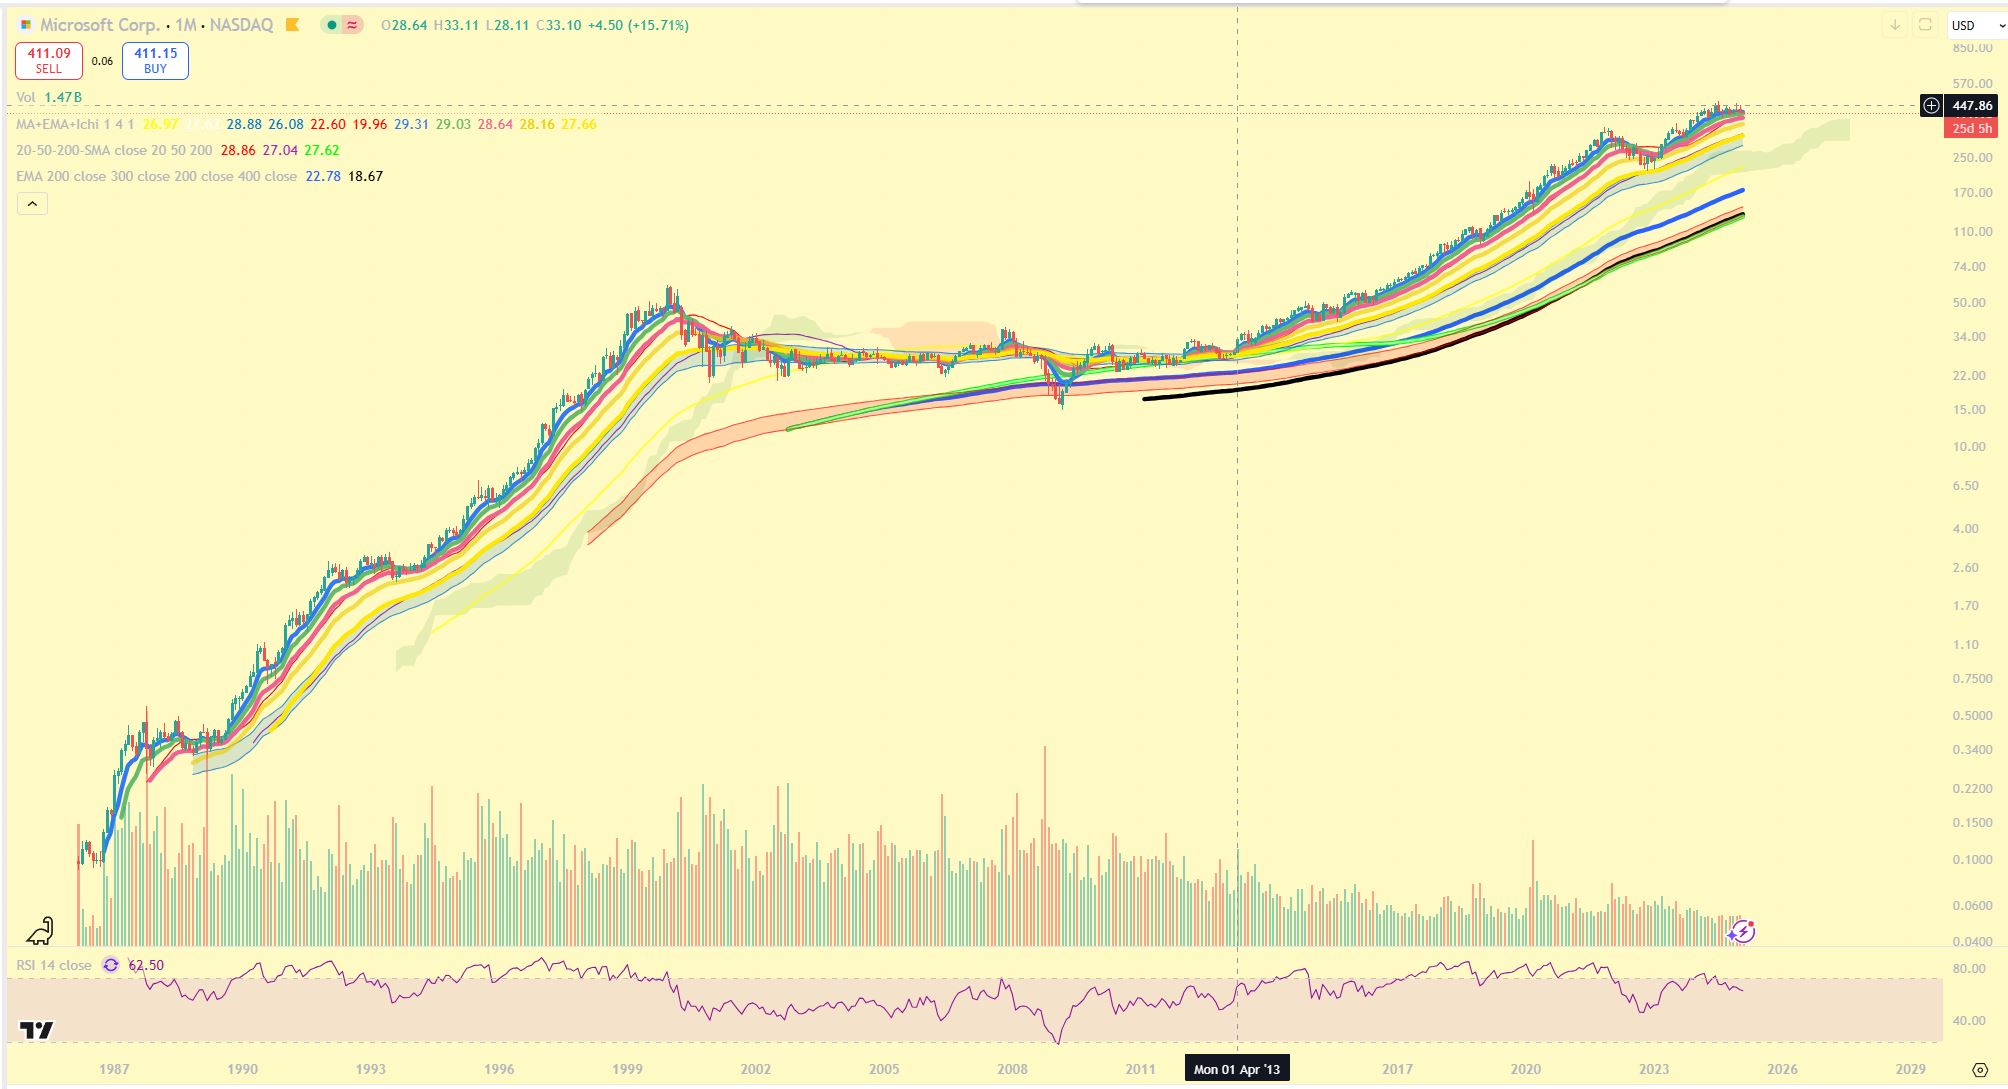
I show some pictures of a longterm logarythmic chart - Bitcoin (who most think that is a bubble), Apple, Google and Microsoft. On a longterm logarythmic chart they all just look very strong and none of them like a bubble. So maybe the Swiss real estate market is just really strong, with constantly additional financial potent people coming to Switzerland and pushing the prices up and up.
---
### Author:  [@cubanpete\_the\_swiss](https://forum.mustachianpost.com/u/cubanpete_the_swiss)
#### Post date: [February 3, 2025, 6:23pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/24 "2025-02-03T18:23:59Z")
Good idea with the log chart. Unfortunately I cannot find one long term for swiss real estate.
The Swiss real estate total return goes only back to 2010 on TradingView. Log Chart:
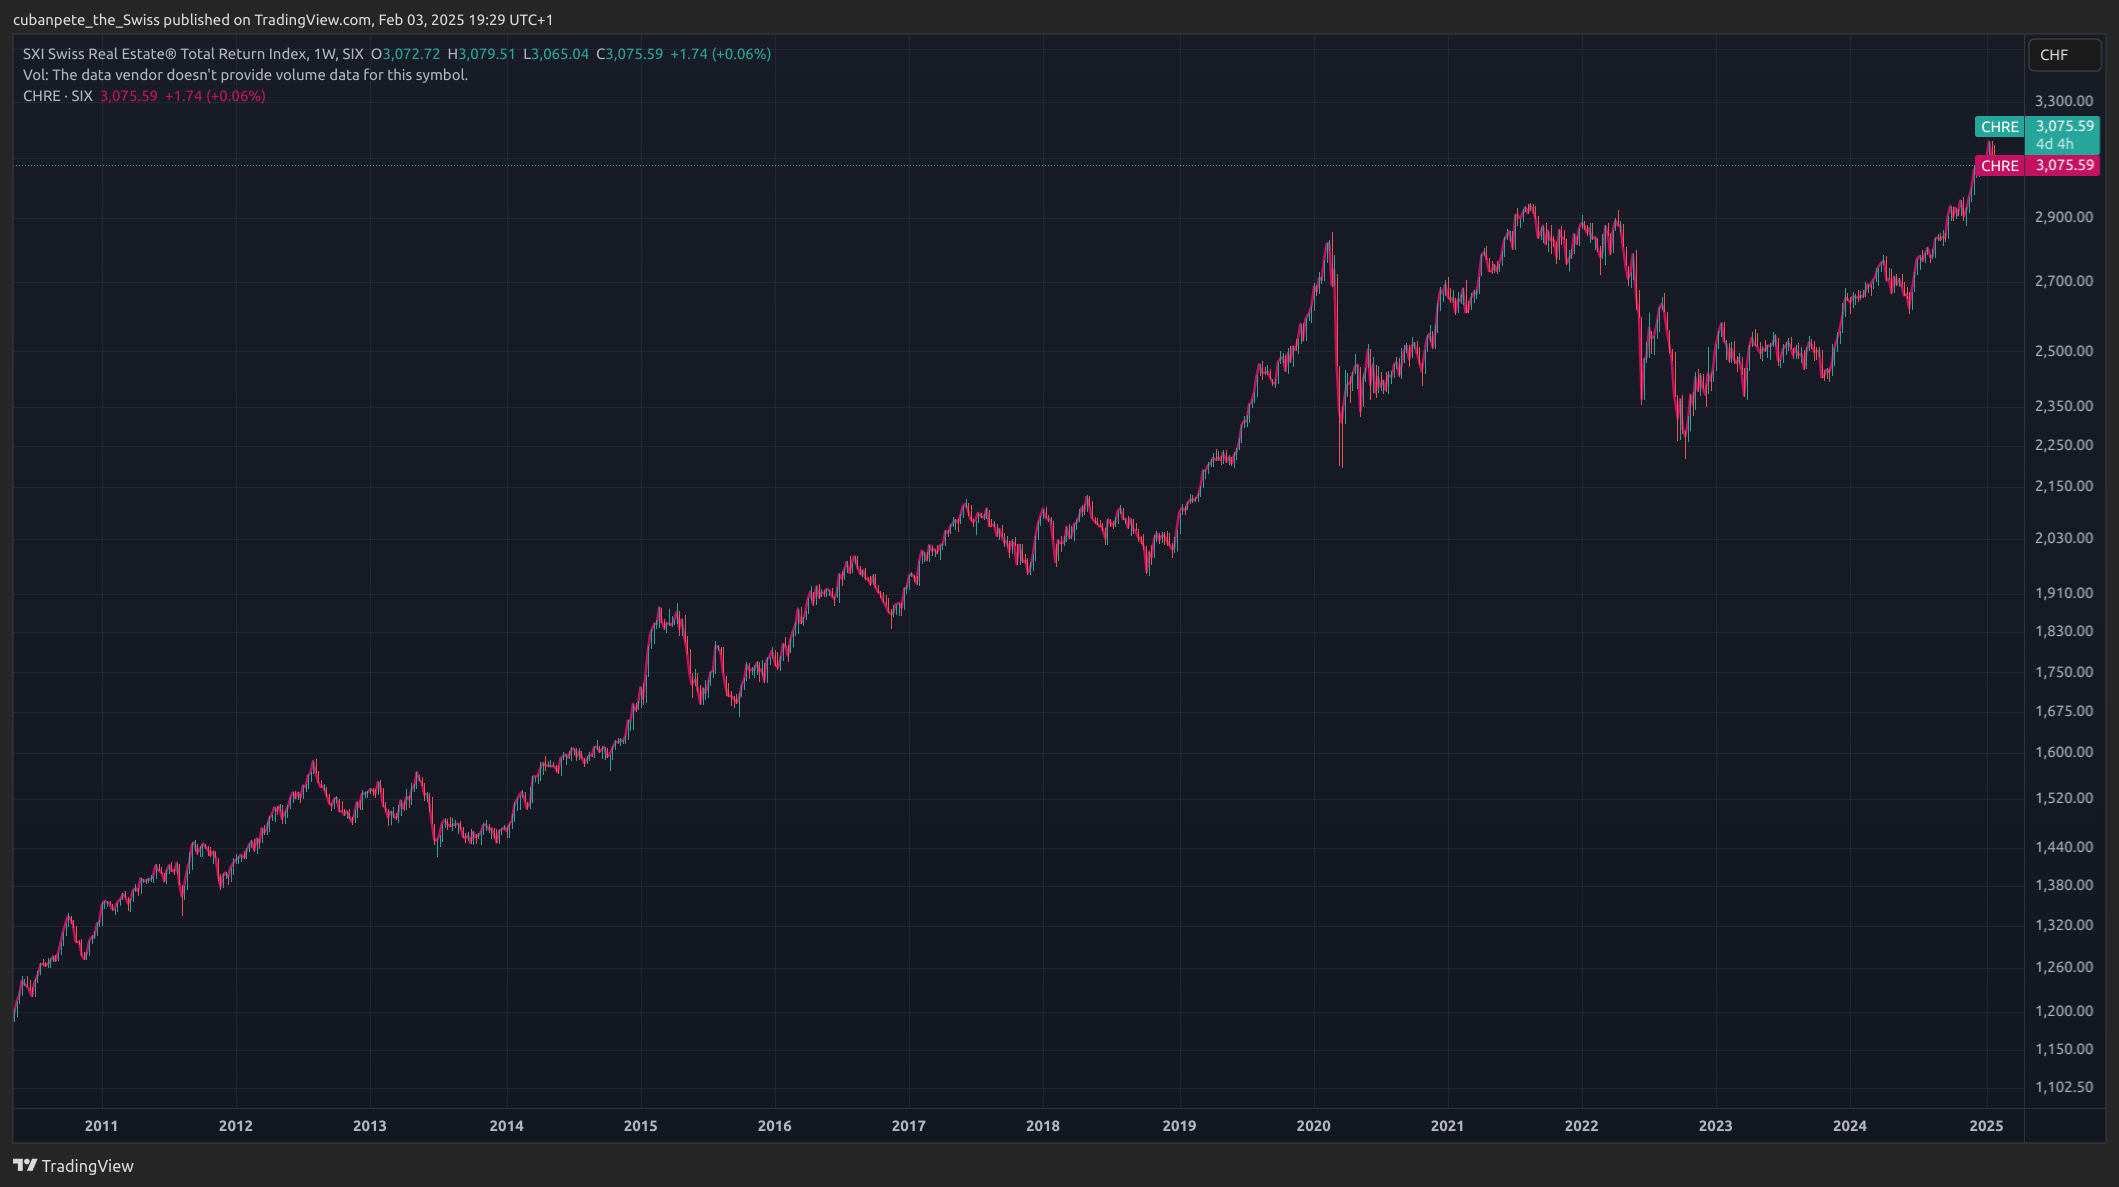
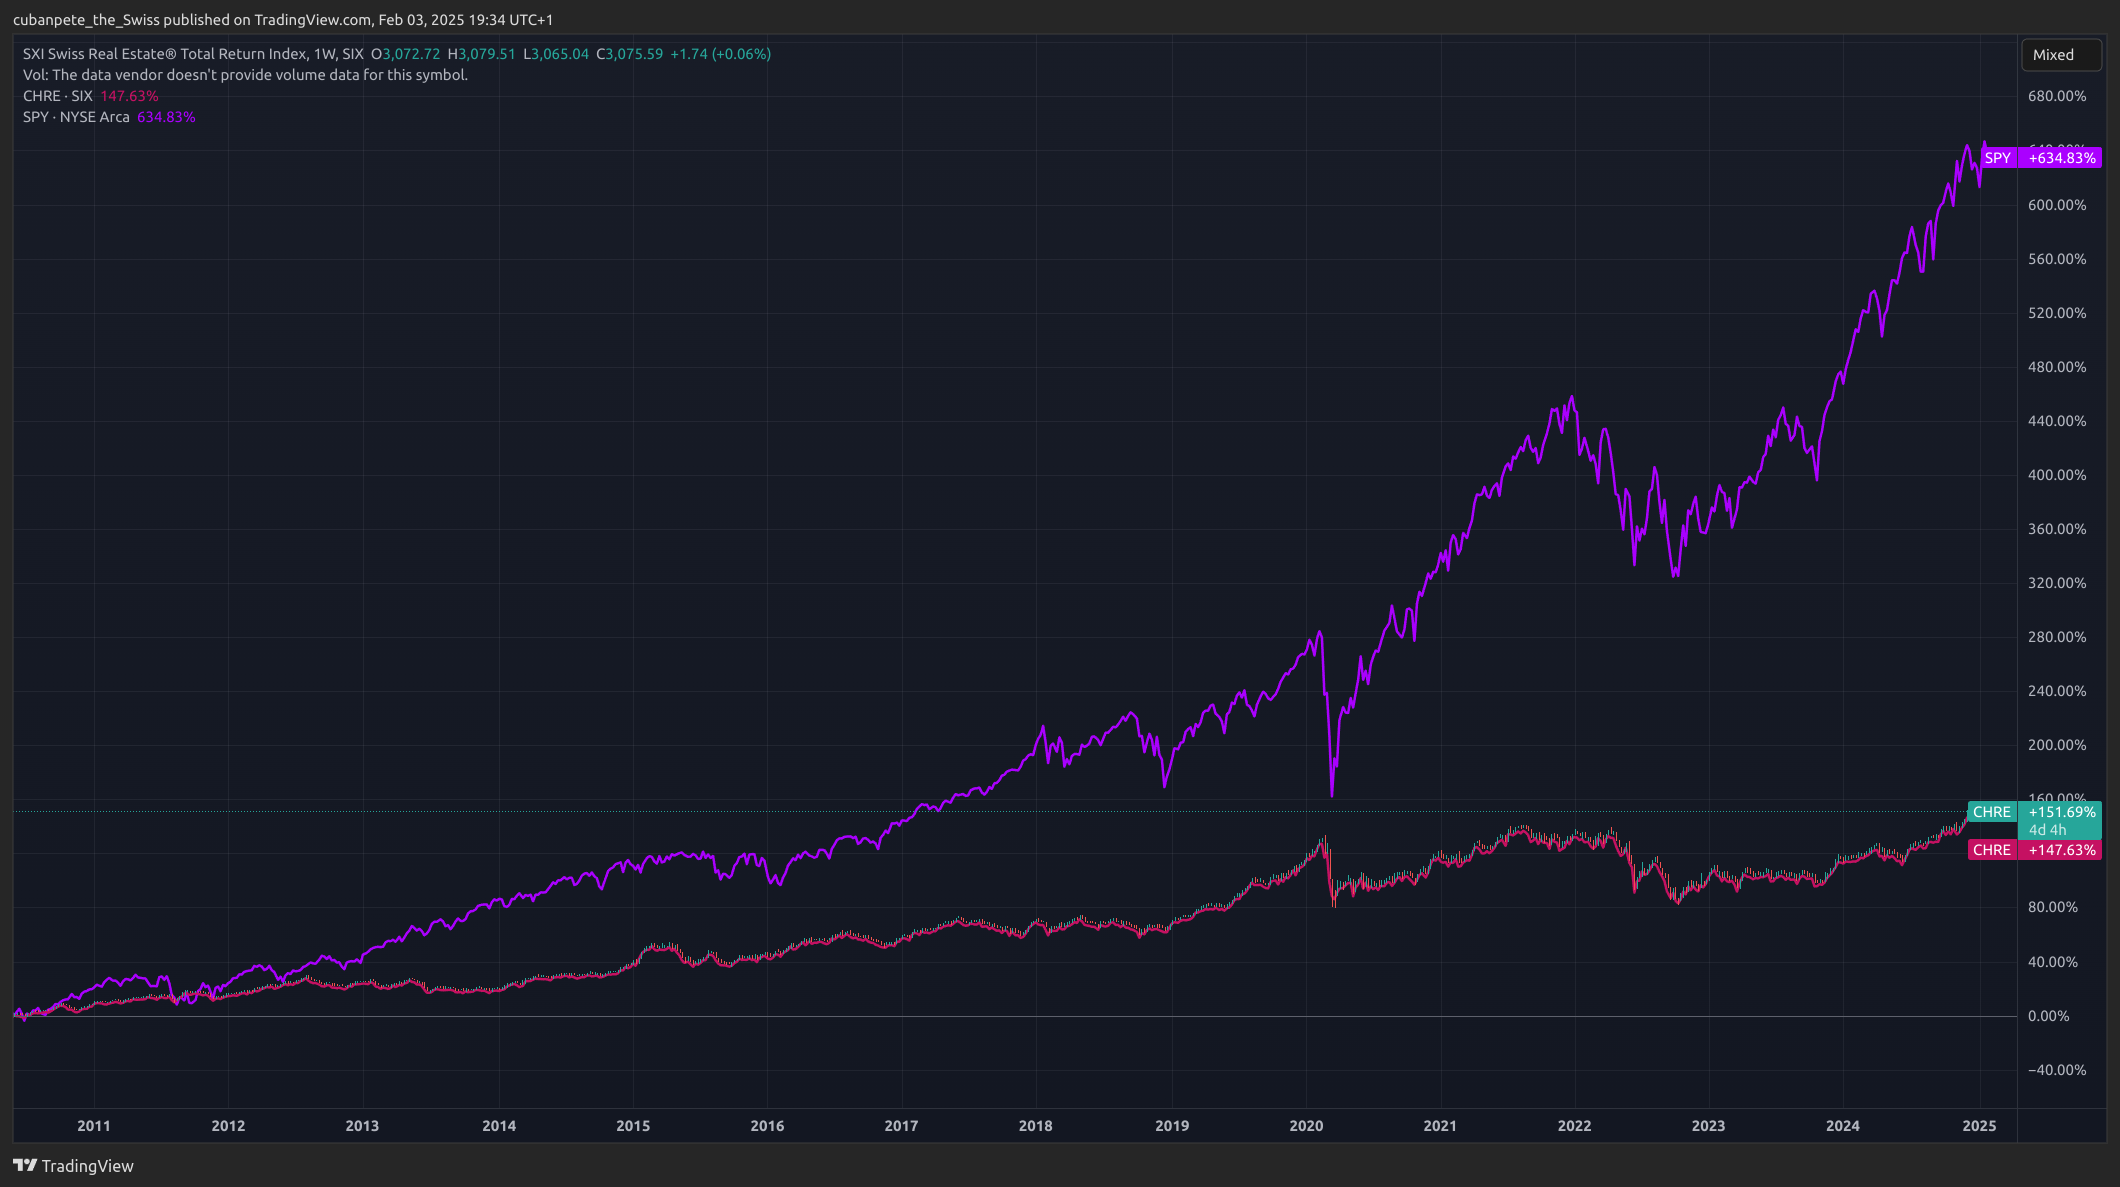
Looks nice, but to repeat, comparing apples with apples including returns (that would be saved rent) and with the same leverage, stocks did way better:
---
### Author:  [@cubanpete\_the\_swiss](https://forum.mustachianpost.com/u/cubanpete_the_swiss)
#### Post date: [February 3, 2025, 7:08pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/25 "2025-02-03T19:08:39Z")
The last chart is interesting, think about it:
On 20% capital many people buy real estate in Switzerland, that is a margin of 500%. Deducting mortgage interest the return would be more or less the same like stocks at 100%. But at what risk?
With 100% margin on stocks you can hardly go bankrupt. With 500% margin on real estate you can… and will if there is a bust. You end up without a home and with debt.
And as I said, even if you go to more than 100% margin on stocks, you can micromanage the risk; you cannot do that with real estate you are living in.
---
### Author:  [@Dr.PI](https://forum.mustachianpost.com/u/Dr.PI)
#### Post date: [February 3, 2025, 7:11pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/26 "2025-02-03T19:11:59Z")
Your data are represented in different currencies, see “Mixed” label in the top right corner.
You can plot SPY\*USDCHF instead for a quick comparison.
---
### Author:  [@cubanpete\_the\_swiss](https://forum.mustachianpost.com/u/cubanpete_the_swiss)
#### Post date: [February 3, 2025, 8:37pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/27 "2025-02-03T20:37:18Z")
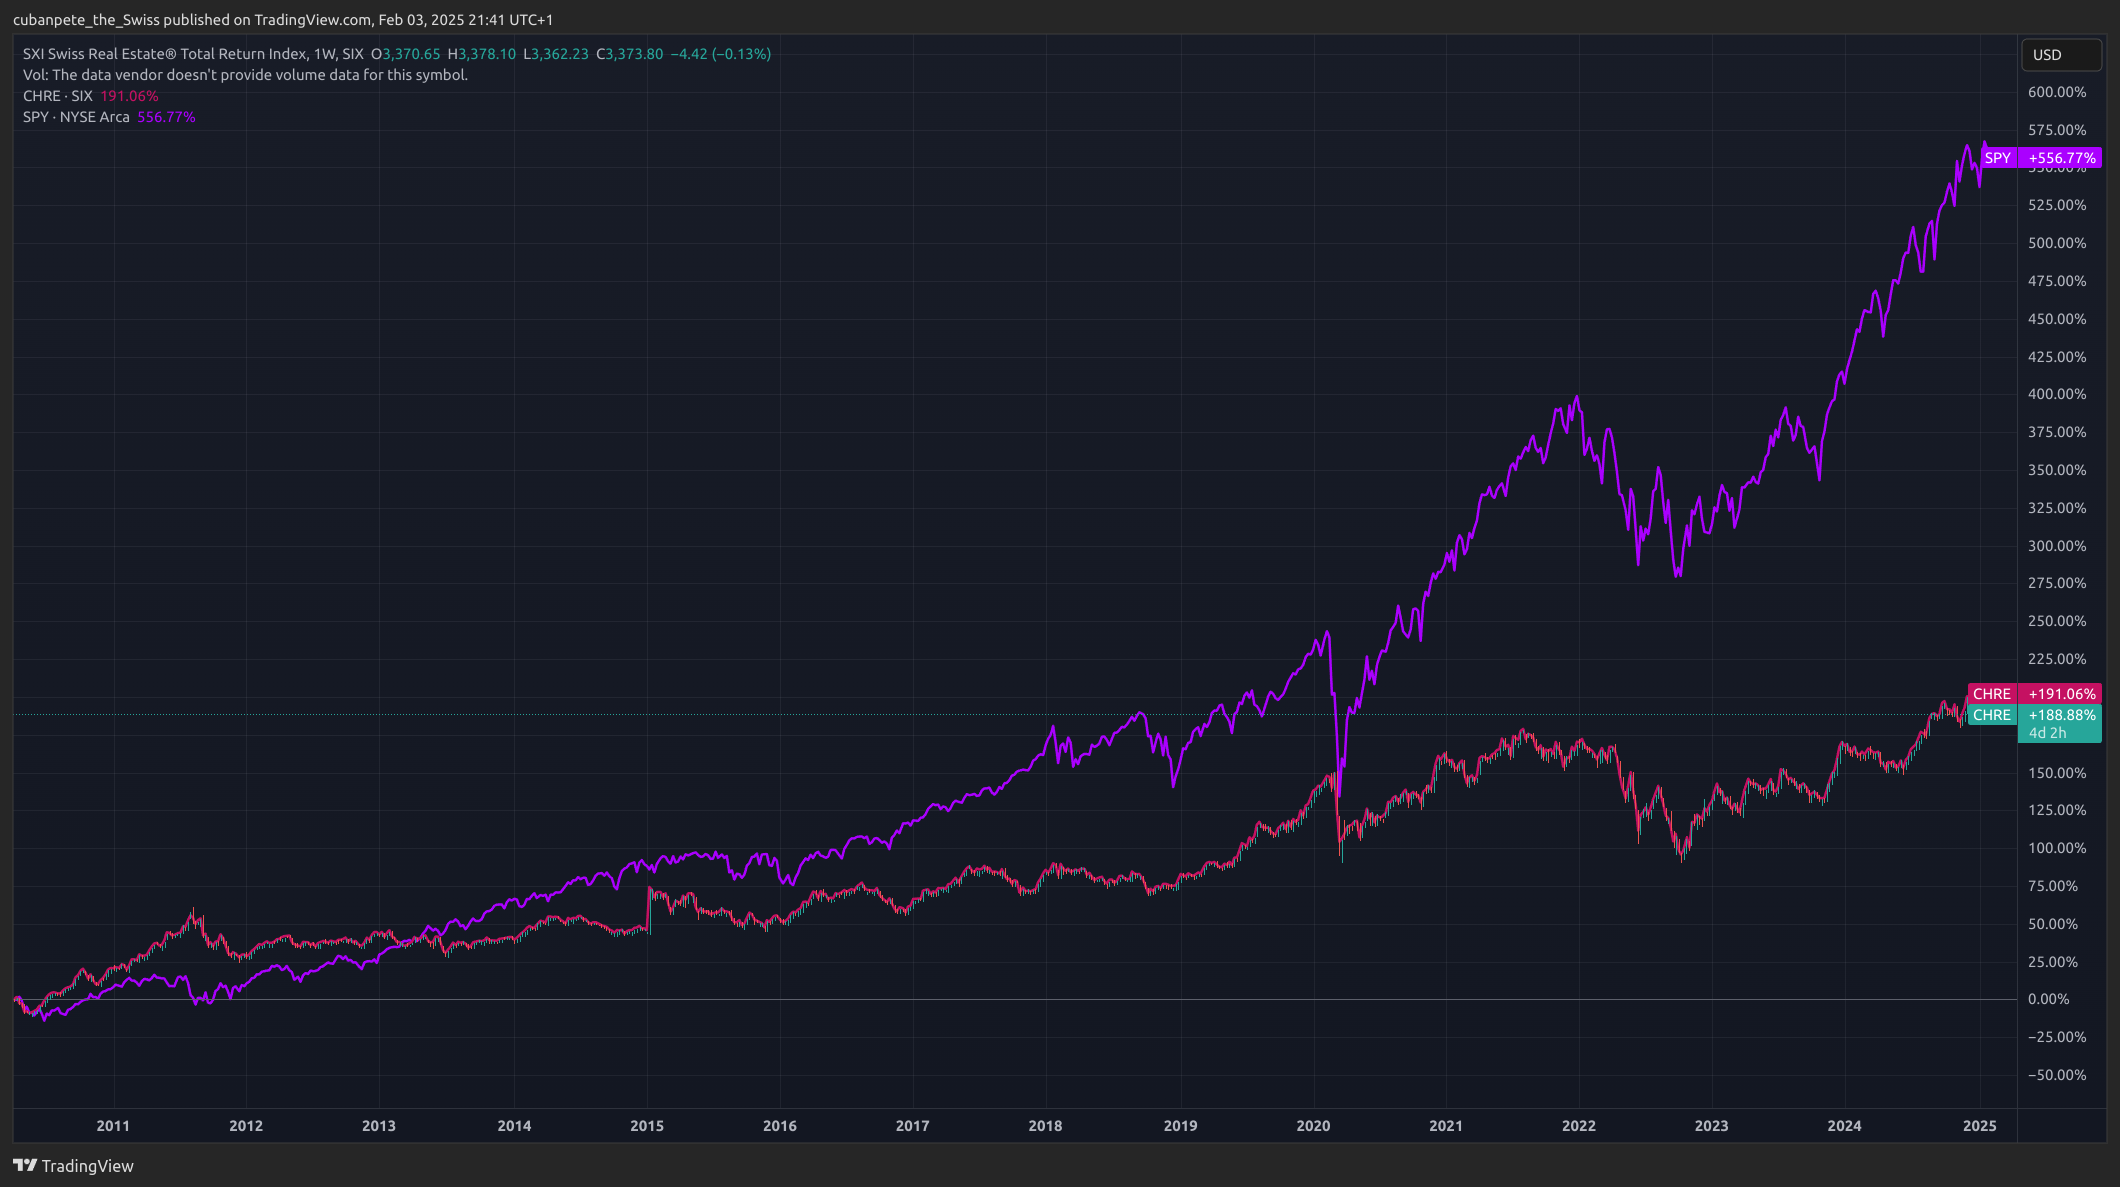
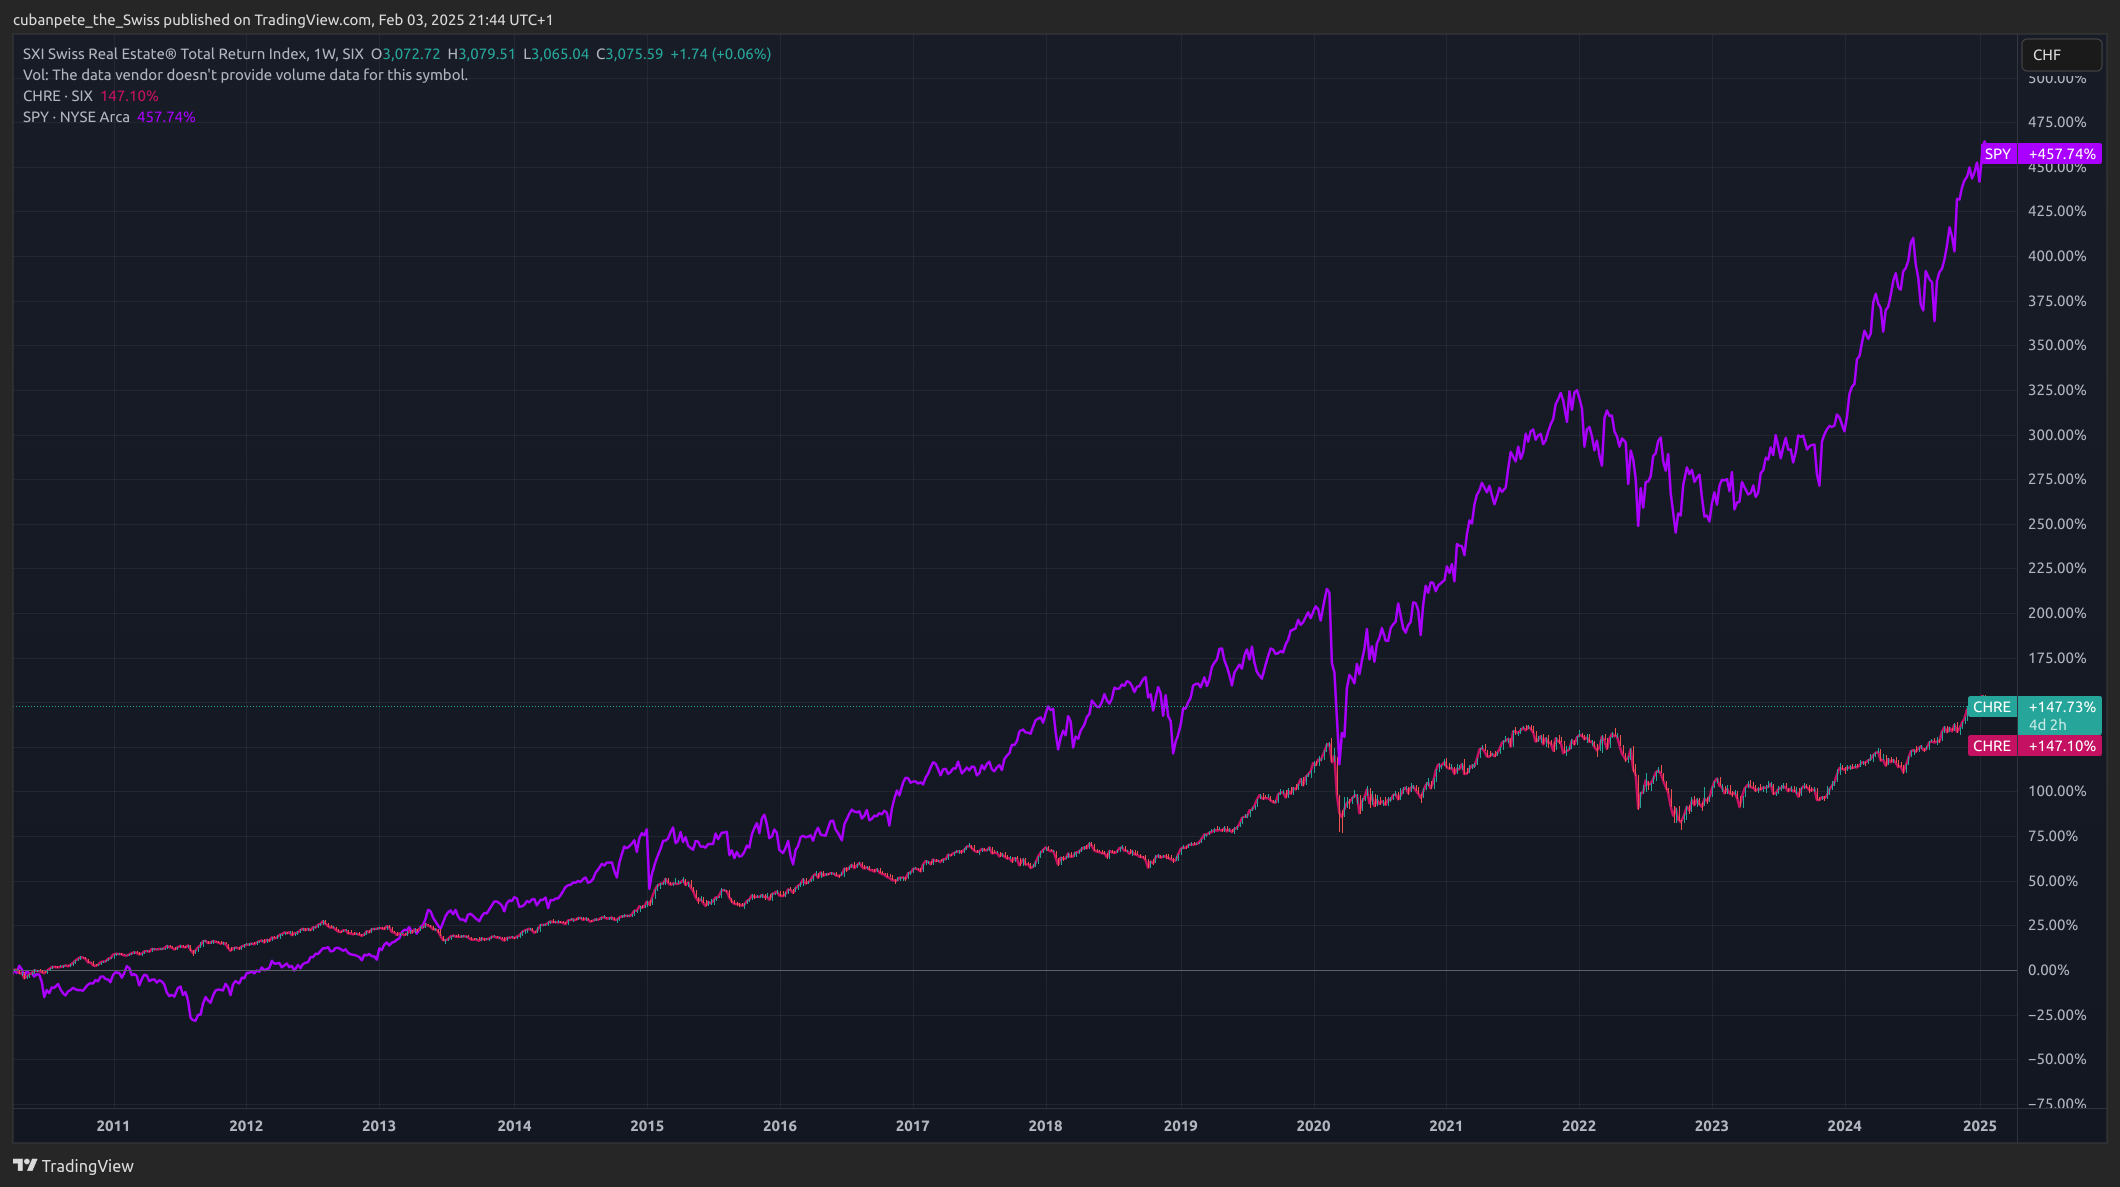
Thanks, for that info. of course you are right. TradingView can compare including different currencies, didn’t know that feature, here it is in USD and CHF:
---
### Author:  [@Wolverine](https://forum.mustachianpost.com/u/Wolverine)
#### Post date: [February 3, 2025, 10:01pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/28 "2025-02-03T22:01:54Z")
With 100% margin on stocks using a margin loan on standard terms, your position can get liquidated the moment the market blinks 1%. It is a rather risky position to take.
Of course, way higher leverage can be achieved using futures, options or other products.
---
### Author:  [@ChickenFat](https://forum.mustachianpost.com/u/ChickenFat)
#### Post date: [February 3, 2025, 10:33pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/29 "2025-02-03T22:33:26Z")
> [@ach](#):
>
> As only ~40% of swiss residents own their home, you would need a lot of them in need to sell quickly to make any difference in the market
I think once the external factor which makes the bubble burst it on the table, some might want to sell quickly while no one wants to buy. AFAIK prices can also sink like a rock because the demand is gone and then no extra supply is needed
---
### Author:  [@cubanpete\_the\_swiss](https://forum.mustachianpost.com/u/cubanpete_the_swiss)
#### Post date: [February 3, 2025, 11:06pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/30 "2025-02-03T23:06:08Z")
Sorry, my English: with “margin of 100%” I meant no debt. A margin of 500% means 20% down payment, 80% debt. Probably there is a better word for that. I remember the word cash margin, which was used as a multiplier, 1 or 100% means all cash, 500% means multiplied by 5 as 100% cash and 400% on debt.
Actually I think with stocks “margin” is the collateral. So probably I should use “margin multiplier”? But then collateral is always 100%, so I left out the word multiplier.
Sorry for the confusion caused.
---
### Author:  [@Wolverine](https://forum.mustachianpost.com/u/Wolverine)
#### Post date: [February 3, 2025, 11:20pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/31 "2025-02-03T23:20:23Z")
Actually, it’s my mistake: I tried to adapt to your numbers (I use leverage mulipliers myself, that work like your margin % and that I find easier to grasp) and failed to consider that by that logic, 100% margin means x1, so no leverage.
I’m no specialist but by my understanding, margin is the collateral. It applies to the total assets so someone who owns X stocks and borrows X ends up with 2X assets and X collateral (or 2X/2), for a margin of 50%.
My 100% really was all over the place.
---
### Author:  [@cubanpete\_the\_swiss](https://forum.mustachianpost.com/u/cubanpete_the_swiss)
#### Post date: [February 4, 2025, 9:25am UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/32 "2025-02-04T09:25:25Z")
> [@Wolverine](#):
>
> margin is the collateral. It applies to the total assets so someone who owns X stocks and borrows X ends up with 2X assets and X collateral (or 2X/2), for a margin of 50%.
OK, in my wording it would be a margin (collateral) multiplier of 2 aka 200% (actual value divided by collateral). In your wording the collateral is compared to the total value in reverse and therefore it would be 50% (collateral divided by actual value). Both are OK for me, but probably somebody can help with the exact wording…
My last job was with oil tanker shipments, involved futures, insurance and regular re-evaluation of margin during the transport time. But it is so long ago, I cannot even remember the correct wording. I think it was like cash margin, (actual value divided by collateral). But it is too long ago, sorry.
My broker, Interactive Brokers, says I have 800% stock trading margin available, portfolio margin. So it seems like they use the same wording as I do.
---
### Author:  [@Dr.PI](https://forum.mustachianpost.com/u/Dr.PI)
#### Post date: [February 4, 2025, 10:58am UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/33 "2025-02-04T10:58:19Z")
> [@cubanpete\_the\_swiss](#):
>
> actual value divided by collateral
I call it “leverage ratio” or “leverage factor”, \>=1.
> [@cubanpete\_the\_swiss](#):
>
> the collateral is compared to the total value in reverse and therefore it would be 50% (collateral divided by actual value).
This is what e.g. IBKR is using, “margin requirements” for securities, \<=100%.
---
### Author:  [@Makis4321](https://forum.mustachianpost.com/u/Makis4321)
#### Post date: [May 8, 2025, 7:25pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/34 "2025-05-08T19:25:18Z")
Hi all
We are a family of 4 moved to Geneva 1y ago.
We are renting a 3 bedrooms 105m2 flat (2004 construction) for 4400 CHF with a double garage included.
Before someone assumes that this a crazy price I would like to mention that prices for 3 bedroom flats in Geneva are pretty much the same (see Champel, St Jean, Saconnex, etc). Especially when you sign first time in 2024.
Having said that we have now started thinking the option to buy something.
However we don’t have the liquid capital required now and we would have to sell a flat we own in Europe to use this as downpayement for the Swiss mortgage. In a best case scenario this would be around 400k euros
According to the UBS [calculator](https://www.ubs.com/ch/en/services/mortgages-and-financing/calculators/mortgage-calculator.html?campID=SEM-MORTGAGES_HYPOTHEKENRECHNER_EXACT_BRAND_LEADS-CH-ENG-GOOGLE-EXACT-RSA-ubs%20mortgage%20calculator-e-m_19772640226_147495518580_650203638456_kwd-306597122590&dtid=paid-google_19772640226_147495518580&ps_kw=ubs%20mortgage%20calculator&gad_source=1&gad_campaignid=19772640226&gbraid=0AAAAADp3lsYWI-mb_hai7riBNsuTBh1cJ&gclid=Cj0KCQjwrPHABhCIARIsAFW2XBNgXOIiKf3P1FxS3vvC_RmUDmB2YL9136FhGNqoNoBu6vpFDmaF8XYaApzXEALw_wcB) our maximum purchase price is
CHF 1’522’917
And monthly costs
Interest
CHF 1’529
Amortization
CHF 783
Incidental expenses
CHF 1’353
Monthly cost in total
CHF 3’665
So this is almost 1K per month lower than what we pay now.
I am missing anything striking here? Any insights from home owners would be highly appreciated!
---
### Author:  [@Abs\_max](https://forum.mustachianpost.com/u/Abs_max)
#### Post date: [May 8, 2025, 7:49pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/35 "2025-05-08T19:49:14Z")
Are you sure you can buy a 3 bedroom (105 m2) apartment in Geneva for 1.55 million? These are quite interesting rental yields (4400 CHF rent on 1.55 million apartment). I always thought Geneva city is like Zurich city where yields are very low
Or are you planning to move to a smaller apartment?
---
### Author:  [@Makis4321](https://forum.mustachianpost.com/u/Makis4321)
#### Post date: [May 8, 2025, 8:14pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/36 "2025-05-08T20:14:52Z")
Yes for a flat it is possible.
Example in Satigny (expensive commune in Geneva):
> **[Splendide duplex entièrement rénové !](https://www.immobilier.ch/fr/acheter/appartement/geneve/satigny/cayden-immobilier-1671/splendide-duplex-entierement-renove-1268547)**
>
> Laissez-vous séduire par le charme de l'ancien associé au confort du contemporain à travers cette ancienne auberge qui fut entièrement réhabilitée avec goût en 2018. Entourée de vignes et de nature, la bâtisse datant du XVIIIe siècle offre un cadre...
We would not fit into a 2 bedrooms so we would always stay at a 3 bedrooms one. Square meters can vary.
---
### Author:  [@Abs\_max](https://forum.mustachianpost.com/u/Abs_max)
#### Post date: [May 8, 2025, 8:29pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/37 "2025-05-08T20:29:44Z")
Good to know . Thanks
---
### Author:  [@Dr.PI](https://forum.mustachianpost.com/u/Dr.PI)
#### Post date: [May 8, 2025, 9:25pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/38 "2025-05-08T21:25:52Z")
> [@Makis4321](#):
>
> So this is almost 1K per month lower than what we pay now.
>
> I am missing anything striking here?
Opportunity costs. Your downpayment, say, 300k CHF, invested in a low cost portfolio that would grow by 4% p.a., would bring you 12k per year, conservatively estimated.
---
### Author:  [@Wolverine](https://forum.mustachianpost.com/u/Wolverine)
#### Post date: [May 8, 2025, 10:24pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/39 "2025-05-08T22:24:57Z")
Amortization is not a cost. It is savings that are forcefully directed toward reducing debt.
CHF 1529 for interests means a ~1.5% interests, that can be obtained for the next 10 years but there’s no telling where rates will be in 10 years. Banks usually stress test our affordability by using 5% interests as a test.
Incidental expenses tend to not happen much most years but when they do, do so by potentially big chunks at once. Be sure to provision that.
Taxes and fees should be assessed. Both one time if there are (notary, land register, mortgage creation, withdrawal of pension assets if applicable - some may not apply and there might be others, it varies by canton) and recurring ones (own ownership, which might change this autumn, and the effect on wealth and income tax of the mortgage and the taxable value of the asset).
Co-ownership inside a building might not be frictionless and it’s harder to move away from the hassle once you are a owner. See for example: [Problem with neighbor :)](https://forum.mustachianpost.com/t/problem-with-neighbor/13969)
Otherwise, if you can find an appartement you enjoy for 1.5M, that might be a good deal for you. There is an opportunity cost but it’s hard to compare savings on rent vs stock returns due to the different risk profile of both (the appartment may appreciate or loose value too so there’d be fluctuation there too if you’d need/want to sell at some point).
---
### Author:  [@ZHCycle](https://forum.mustachianpost.com/u/ZHCycle)
#### Post date: [May 8, 2025, 11:28pm UTC](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397/40 "2025-05-08T23:28:29Z")
Think about indirect amortization.
Think about buying in a bigger building (rather than a house or smaller building), it has its drawbacks, sure, but your monthly incidentals will be far lower. Fwiw in Zurich for just 1 bedroom I pay less than 300 a month on incidentals (not including the quarterly EWZ because that is separate always, also as a renter). However, I also got ‘lucky’ in the sense that the contractors including for heating were chosen well, it is EWZ in most cases where the service is something they offer. I know someone in a much smaller building (2 houses, I think 8-10 apartments in total), the building company very likely received kickbacks or something because they have some shitty long ass contract with the heating provider and prices have gone up a lot every year. But overall were also more expensive, not just the heating part. In a bigger building, costs distribute better. So find out, if it’s an older place, what current prices are, and if it’s new, make sure to get an overview of who has been contracted to do what and check their offerings.
Saying all this, I absolutely do not think buying a big place in CH is a good financial decision. As someone else already said yields are typically low, meaning renting is good value versus buying. The amount of capital you put into this one asset is huge and has a big CoC. Also, owning can be a hassle if something bad happens.
[Previous page](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397.md?page=1)
[Next page](https://forum.mustachianpost.com/t/buying-a-property-some-questions/15397.md?page=3)