# 3a solution from Finpension
**URL:** https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522
**Category:** Banks, Insurances & Third Pillar
**Created:** [October 8, 2020, 2:00pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522 "2020-10-08T14:00:27Z")
**Posts on this page:** 20
**Page:** 5
### Author:  [@Cortana](https://forum.mustachianpost.com/u/Cortana)
#### Post date: [November 1, 2020, 12:45pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/95 "2020-11-01T12:45:42Z")
Better to have more accounts than less. 5 is ideal under the current rules. My plan for withdrawing my 2nd/3rd pillar accounts:
61: 3a 1
62: 3a 2
63: 3a 3
64: 3a 4
65: 3a 5
69: 2nd pillar 1
70: 2nd pillar 2
Assuming I stop working before 60 and leave my current pension fund, thus transfering my 2nd pillar assets to someone like ValuePension. Gives you the opportunity to withdraw it till 70 instead of 65.
But of course everything can change in 30 years.
---
### Author:  [@Cortana](https://forum.mustachianpost.com/u/Cortana)
#### Post date: [November 1, 2020, 12:49pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/97 "2020-11-01T12:49:14Z")
I would take it to the Bundesgericht if they start playing games with me. I still don’t get which law prevents me from doing something like this?
---
### Author:  [@San\_Francisco](https://forum.mustachianpost.com/u/San_Francisco)
#### Post date: [November 1, 2020, 12:59pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/99 "2020-11-01T12:59:07Z")
> [@Beisat](#):
>
> For a house (WEF), a partial withdrawal is possible.
Yes, didn’t I mention it as an exception above?
No, I didn’t. 😳
> [@ProvidentRetriever](#):
>
> And yet worth 10,000s of CHF in tax savings upon retirement
What amounts are you assuming here? 😲
If you are employed and restricted to lower yearly (around CHF 7k) pay-in amounts of approximately 7000/year, you’ll maybe contribute a total 300k to pillar 3a over a lifetime of work (and that doesn’t account for considerably earlier retirement).
It depends on the end value of your investments. Saving multiple “10,000s” in tax seems a bit optimistic (for pillar 3a alone), cause the [progression isn’t that high](https://www.123-pensionierung.ch/de/rente-oder-kapital/kapitalauszahlungssteuern/).
Still, as there is no drawback except a bit more paperwork, I see no good reason _not_ to split.
---
### Author:  [@MrRIP](https://forum.mustachianpost.com/u/MrRIP)
#### Post date: [November 1, 2020, 1:11pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/100 "2020-11-01T13:11:48Z")
> [@ProvidentRetriever](#):
>
> And yet worth 10,000s of CHF in tax savings upon retirement. 🙂 I’ll gladly do such things for such amounts.
Yeah, why not also turn around three times and say out loud “How much wood would a woodchuck chuck if a woodchuck could chuck wood?” everytime you want to check your balance? I’d do that for 10k in tax savings, so why didn’t they add other extra useless annoying stuff in their flow?
> [@ProvidentRetriever](#):
>
> I don’t think this is a big problem in the long term. I heard several times that 50k is the amount from which it is worth starting with a new 3a portfolio.
40.7k CHF will more than double in a 22 years horizon.
> [@San\_Francisco](#):
>
> I just signed up with Finpensions, and the risk assessment is just a few clicks and a slide with the finger in-app. Honestly not trying to be snarky or anything, but could take less time than you trying to worry about it on the forum 😉
Good point 🙂 Still I have problems with stupidity 😃
> [@San\_Francisco](#):
>
> PS: In your case, the per-account risk assessment actually makes sense, because you want to do staggered or early withdrawals.
Again, good point. I’m the stupid 😜
> [@Cortana](#):
>
> Actually there is. Withdrawing it for buying a house or amortize a mortgage.
Thanks! I didn’t know you can partially withdraw from a portfolio/account in case of buying a property (which is usually the only early withdrawal case where they ask you for a fee)
> [@Cortana](#):
>
> 69: 2nd pillar 1
> 70: 2nd pillar 2
How can you have more than one Pillar 2 accounts?
Are you playing with fire and leaving money on a Vested Benefits Account while having a fill time job with Pillar 2 contributions?
---
### Author:  [@San\_Francisco](https://forum.mustachianpost.com/u/San_Francisco)
#### Post date: [November 1, 2020, 1:16pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/101 "2020-11-01T13:16:52Z")
> [@Cortana](#):
>
> I still don’t get which law prevents me from doing something like this?
_"Theoretisch können auf diese Weise Gelder aus der gebundenen Selbstvorsorge sogar in **elf** unterschiedlichen Steuerperioden abgerufen werden (wenn die Säule 3a bis zum 69. Altersjahr bei Frauen bzw. 70. Altersjahr bei Männern bestehen bleibt)._
_ **Jeder Kanton hat seine eigene Besteuerungsregelung bezüglich der Staffelung von Kapitalleistungen aus der zweiten Säule und der Säule 3a**. Das StHG sieht diesbezüglich keine Regelung vor. Es gibt beispielsweise Kantone, die gestaffelte Kapitalleistungen aus der zweiten Säule gleich wie einen einzigen Kapitalbezug im Jahr der ersten Zahlung besteuern. Andere Kantone wiederum fassen alle im Verlauf von fünf Jahren bezogenen Kapitalleistungen aus der gebundenen Selbstvorsorge zusammen, so dass der gestaffelte Bezug die Progression nicht durchbricht. Da die Möglichkeit der Staffelung **nicht gesetzlich sondern in der Praxis geregelt ist** , ist die zur Anwendung gelangende Regelung für die Steuerpflichtigen nicht immer sehr transparent"_
> **[35843.pdf](https://www.newsd.admin.ch/newsd/message/attachments/35843.pdf)**
If the federal tax administration acknowledges that there are limits and anti-circumvention rules/rulings on tax optimisation through staggered withdrawals, I wouldn’t discount the possibility that that will also hold up at the Bundesgericht.
Hopefully you’re at least 10 years older than me and keep us updated on this forum when the time comes.
---
### Author:  [@Dtrogen](https://forum.mustachianpost.com/u/Dtrogen)
#### Post date: [November 1, 2020, 2:26pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/102 "2020-11-01T14:26:42Z")
> [@San\_Francisco](#):
>
> I just signed up with Finpensions, and the risk assessment is just a few clicks and a slide with the finger in-app. Honestly not trying to be snarky or anything, but could take less time than you trying to worry about it on the forum
So I have to make separate account which are not connected to each other ? I mean, can’t I have an account where I can see all my accounts ?
---
### Author:  [@Beisat](https://forum.mustachianpost.com/u/Beisat)
#### Post date: [November 1, 2020, 3:09pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/103 "2020-11-01T15:09:16Z")
> [@MrRIP](#):
>
> How can you have more than one Pillar 2 accounts?
> Are you playing with fire and leaving money on a Vested Benefits Account while having a fill time job with Pillar 2 contributions?
When retiring early, you get a vested benefits account. You can completely officially tell you PK to send the money to two different vested benefit accounts (split). Just make sure they are at different foundations.
A vb account will not automatically trigger payment when you reach 65.
---
### Author:  [@Cortana](https://forum.mustachianpost.com/u/Cortana)
#### Post date: [November 1, 2020, 3:09pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/104 "2020-11-01T15:09:34Z")
> [@MrRIP](#):
>
> How can you have more than one Pillar 2 accounts?
> Are you playing with fire and leaving money on a Vested Benefits Account while having a fill time job with Pillar 2 contributions?
No you can actually ask your pension fund to split it in 2 once you leave your last employer.
---
### Author:  [@San\_Francisco](https://forum.mustachianpost.com/u/San_Francisco)
#### Post date: [November 1, 2020, 3:45pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/105 "2020-11-01T15:45:43Z")
> [@Dtrogen](#):
>
> So I have to make separate account which are not connected to each other ? I mean, can’t I have an account where I can see all my accounts ?
You can have multiple accounts (or “portfolios”, if you prefer the term), which can be seen an administrated under the same user account and login.
Each does have its own portfolio composition though.
---
### Author:  [@Lonair](https://forum.mustachianpost.com/u/Lonair)
#### Post date: [November 1, 2020, 4:16pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/106 "2020-11-01T16:16:58Z")
> Viac opens 5 portfolios for you automatically, am I right?
In VIAC you have to create an account 5 times, and if I remember well, have to go through the list of questions each time, but it’s just a few clicks. Not possible to open 5 accounts in one shot. Once you create the first account, it’s quite quick to create the 4 remaining, something like 10mins.
---
### Author:  [@Lonair](https://forum.mustachianpost.com/u/Lonair)
#### Post date: [November 1, 2020, 4:20pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/107 "2020-11-01T16:20:19Z")
Thank you so much for sharing this! I will have a look as soon as I find the time. Cheers
---
### Author:  [@finpension](https://forum.mustachianpost.com/u/finpension)
#### Post date: [November 2, 2020, 7:27am UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/110 "2020-11-02T07:27:01Z")
@MrRIP I have seen that the questions have already been answered in the Forum. I just wanted to add one comment: We create a risk profile for each portfolio, as the investment horizon can vary for each portfolio (e.g. in the case of a planned advance withdrawal for home ownership). The other questions from the risk profile are related to loss management and financial knowledge and are recorded at client level. A modified answer to these questions will therefore update all existing risk profiles.
Kind regards
---
### Author:  [@MrRIP](https://forum.mustachianpost.com/u/MrRIP)
#### Post date: [November 3, 2020, 8:51am UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/111 "2020-11-03T08:51:44Z")
So you’re self employed today, and you plan to never be employed for the rest of your working life?
Or… are you early retired in Switzerland?
---
### Author:  [@MrRIP](https://forum.mustachianpost.com/u/MrRIP)
#### Post date: [November 3, 2020, 8:52am UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/112 "2020-11-03T08:52:44Z")
Thank you so much for your answer, it makes sense.
---
### Author:  [@Cortana](https://forum.mustachianpost.com/u/Cortana)
#### Post date: [November 3, 2020, 9:13am UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/113 "2020-11-03T09:13:29Z")
No I’m still working. But after my last day I’ll ask my pension fund to split it up.
---
### Author:  [@rolandinho](https://forum.mustachianpost.com/u/rolandinho)
#### Post date: [November 3, 2020, 8:56pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/114 "2020-11-03T20:56:15Z")
> [@Cortana](#):
>
> split it up
Is the split defined by the obligatorisch & über-obligatorisch parts (i.e. for most people that’ll be about 80:20 or 70:30) , or can you choose any split you’d like (typical choice would then most probably be 50:50)?
---
### Author:  [@San\_Francisco](https://forum.mustachianpost.com/u/San_Francisco)
#### Post date: [November 3, 2020, 8:59pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/115 "2020-11-03T20:59:31Z")
You can split 50:50.
(I’m not sure if you can split between mandatory and non-mandatory part. Though I think I have reversely seen such from AXA as payment instructions for incoming transfers into some of their pension funds).
---
### Author:  [@MFV91](https://forum.mustachianpost.com/u/MFV91)
#### Post date: [November 4, 2020, 4:45pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/116 "2020-11-04T16:45:38Z")
Hi! Very interesting topic, I’m definitely thinking about a switch from VIAC towards finpension…just a quick question that I look and didn’t find an answer for : does someone have an idea about the costs of the switch?
I mean, they would probably sell everything on VIAC and rebuy everything in Finpension…no?
---
### Author:  [@xorfish](https://forum.mustachianpost.com/u/xorfish)
#### Post date: [November 4, 2020, 5:59pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/117 "2020-11-04T17:59:19Z")
For me, the cost difference in ongoing costs is too small to make up for the cost of a transfer.
Being out of the market for a month is already around 0.5% lost expected return plus a decent portion of uncompensated risk.
---
### Author:  [@MrLeanLife](https://forum.mustachianpost.com/u/MrLeanLife)
#### Post date: [November 5, 2020, 1:21pm UTC](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522/118 "2020-11-05T13:21:34Z")
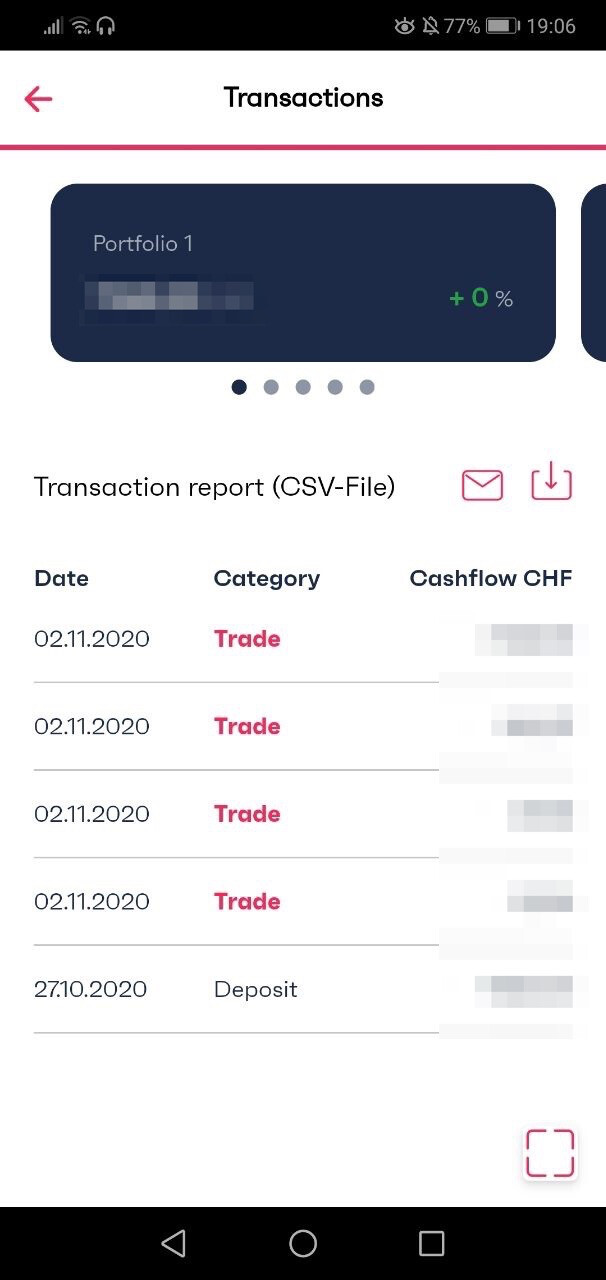
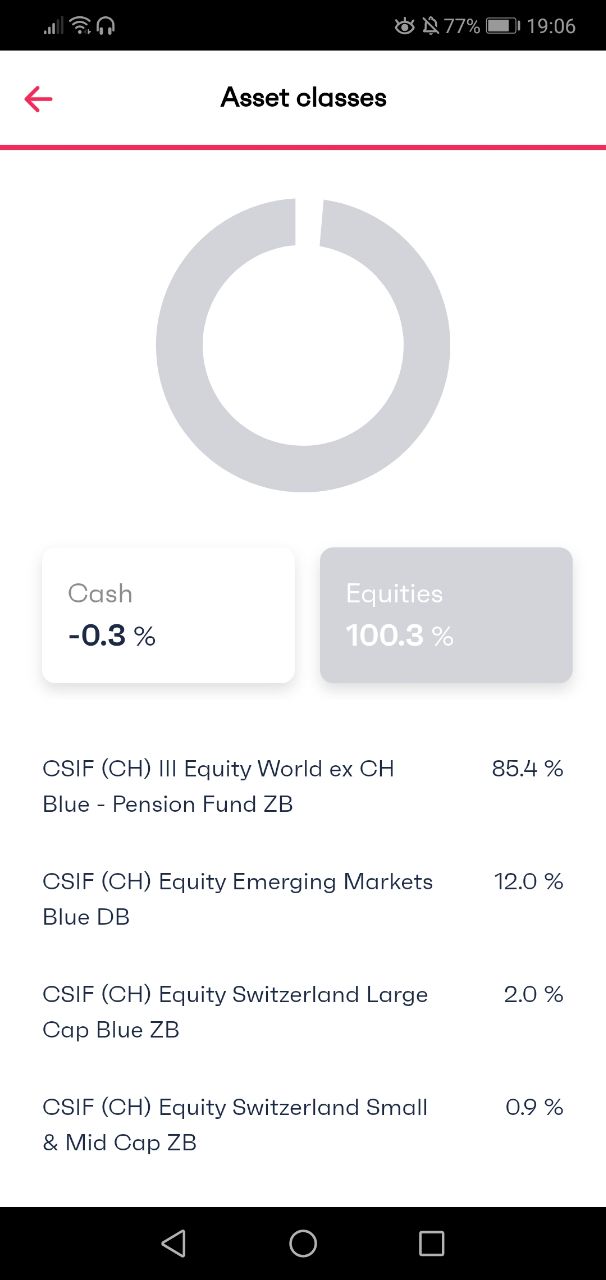
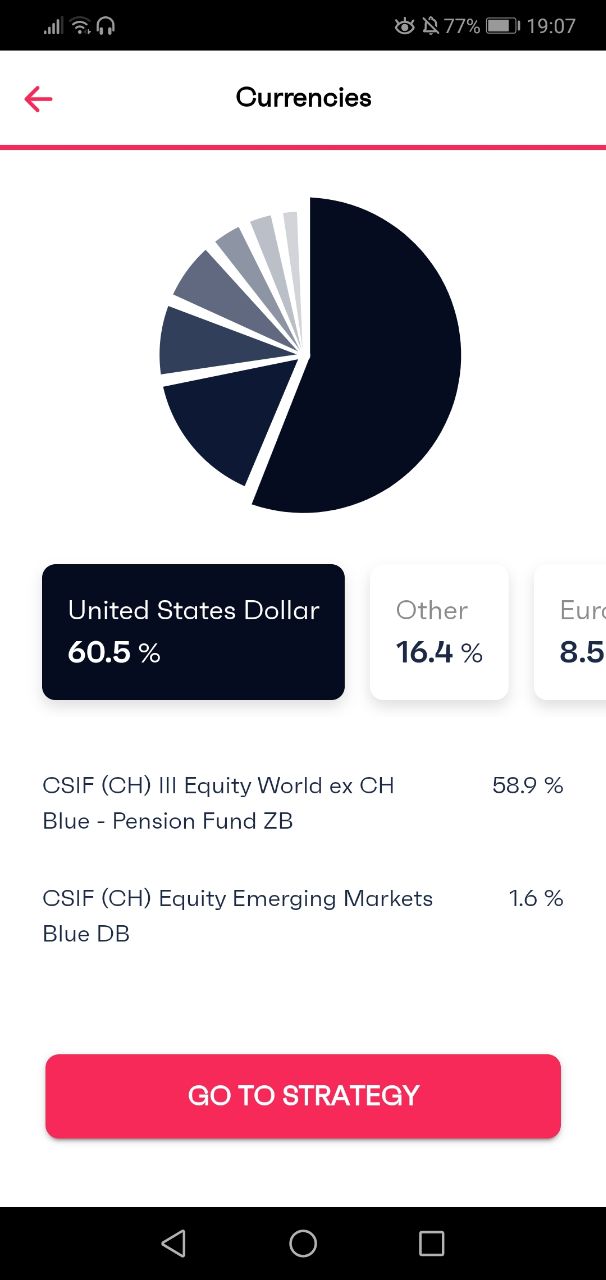
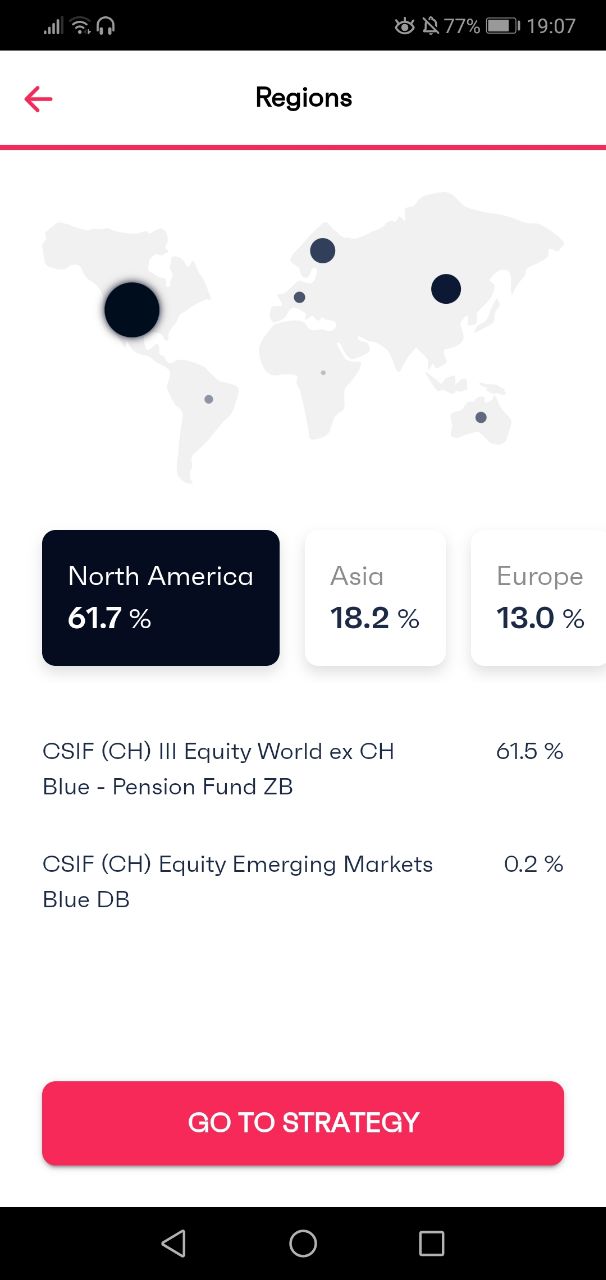
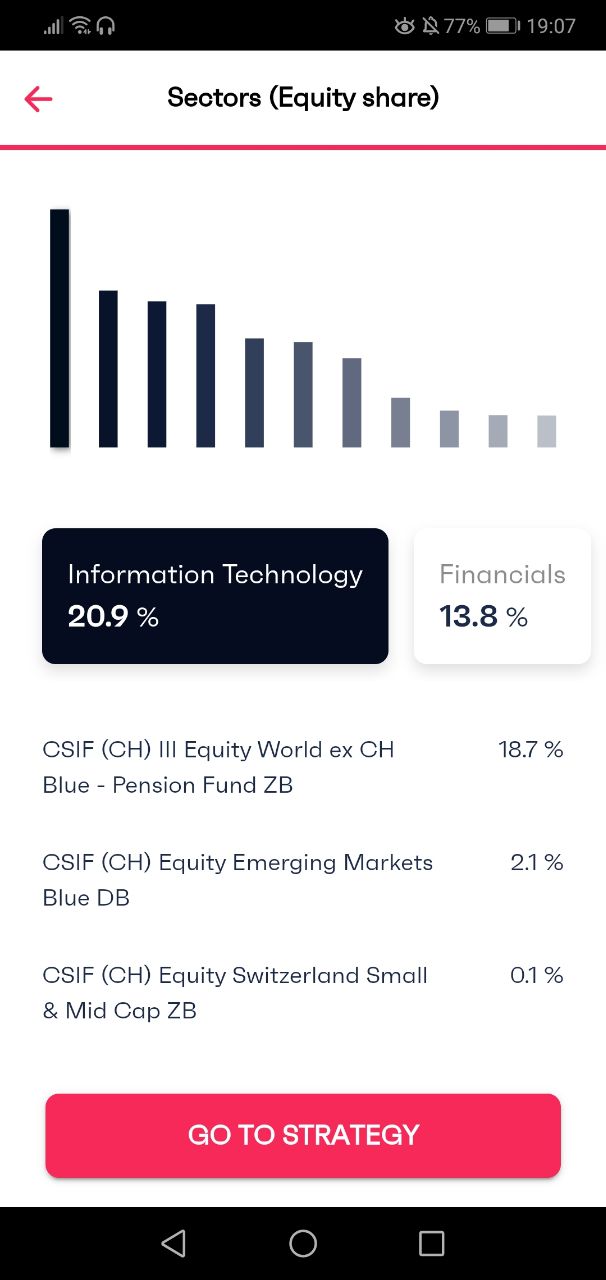
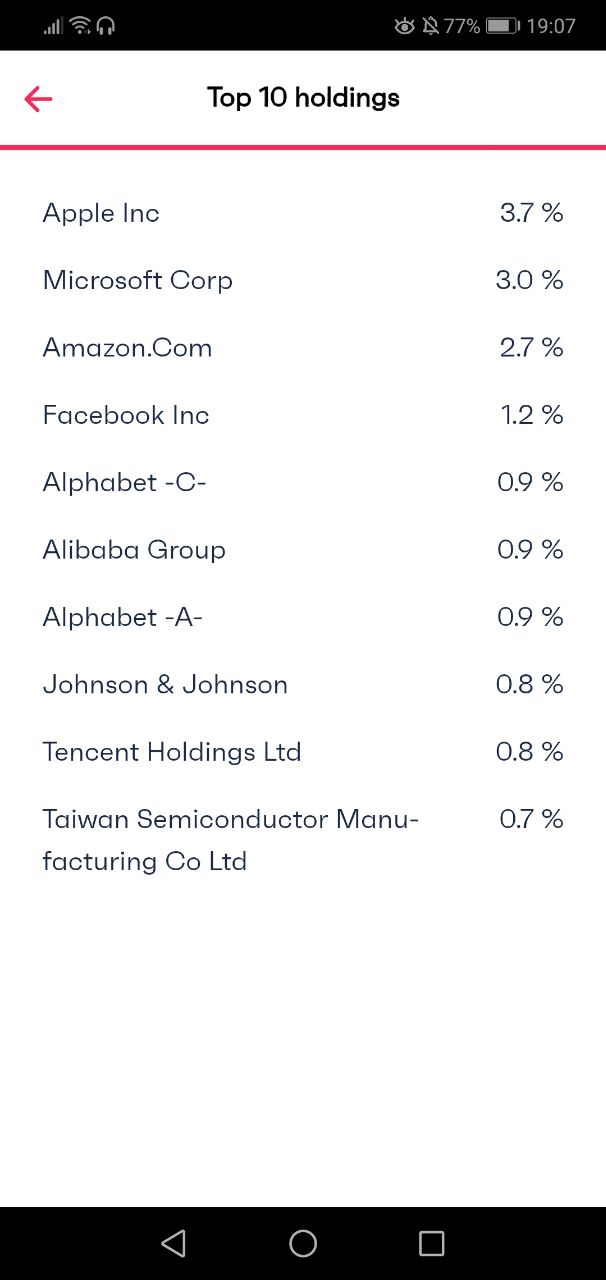
Below some screenshots from my first experience with finpension. The trades correctly occurred on 02.11.2020. Please note that it took around 3 days to update the information in the app.
[Previous page](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522.md?page=4)
[Next page](https://forum.mustachianpost.com/t/3a-solution-from-finpension/4522.md?page=6)